



Original Author: Azuma
Original Source: Odaily Planet Daily
U.S. investors are one step closer to legally trading perpetual futures on U.S. stocks on domestic regulated exchanges.
On November 3, U.S. Commodity Futures Trading Commission (CFTC) Chairman Michael S. Selig issued a statement formally approving the listing and trading of Equity Perpetual Futures on regulated U.S. exchanges.
For a long time, "Perpetual Futures" have been a hallmark innovation native to the crypto market — no expiration date, no need for frequent rollovers, and spot price anchoring through funding rates. With the CFTC giving the green light, this trading product born in offshore crypto markets will officially cross asset boundaries and break into the tightly regulated traditional U.S. stock market. This means U.S. investors will soon have the opportunity to go long or short on the stock prices of listed companies such as Apple, Nvidia, and Tesla through perpetual futures without having to directly hold the shares.
For trading platforms that have been trying to bring on-chain derivatives markets to the U.S., this is undoubtedly a historic breakthrough; at the same time, Wall Street's reaction has been one of alarm — as soon as the CFTC's approval landed, the traditional Wall Street finance camp led by Citadel Securities and the Chicago Board Options Exchange (Cboe) swiftly filed a lawsuit in federal court seeking to press pause.
Regulators Open the Gates: Four Exchanges First in Line
According to Selig's statement, these equity perpetual contracts are classified as Security Futures Products under the U.S. Commodity Futures Modernization Act (CFMA) and are deemed approved under CFTC Regulation 40.3 procedures. This means they are not regulated solely by the CFTC, but are simultaneously subject to the relevant laws and regulatory frameworks of both the CFTC and the U.S. Securities and Exchange Commission (SEC).
Selig stated that in the past, due to a lack of coordination between the CFTC and SEC, innovative products such as security futures had long existed in a regulatory gray zone. This year, the two agencies have signed a Memorandum of Understanding (MOU), and this approval is part of their joint effort to advance regulatory coordination.
Although the regulatory direction is set, not all platforms can immediately list U.S. stock perpetual futures. According to a summary by Bankless founder David Hoffman, platforms expected to list immediately must simultaneously meet four hard requirements:
Hold a CFTC-registered Designated Contract Market (DCM) license; clear through a registered Derivatives Clearing Organization (DCO); complete dual registration with the SEC (becoming a notice-registered national securities exchange by submitting Form 1-N); and have previously submitted rule change applications for equity perpetual futures during the window from mid-to-late September to early October, completing the 45-day review period.
Currently, only four platforms in the entire U.S. have completed the full application process and are expected to receive first-batch approval.
a. Kalshi (KalshiEX LLC): As a trailblazer in prediction markets and derivatives, Kalshi submitted its equity perpetual application to regulators at the end of September after securing the first BTC perpetual contract in May. According to its filing documents, Kalshi initially plans to cover 58 popular U.S. stock contracts including Apple, Tesla, and Nvidia. Its rules set a minimum initial margin of 15.50% (equivalent to a maximum leverage of approximately 6.5x), offer a trading window of 23 hours per day, five days a week (6 PM ET Sunday to 5 PM ET Friday), with funding rates settled daily based on observed values during regular U.S. stock trading hours.
b. Coinbase (Coinbase Derivatives, LLC): Coinbase Derivatives filed with the SEC and CFTC on September 18. Coinbase's proposal adopts a cash-settled design with no physical equity delivery, with trading hours from 8 PM ET Sunday to 5 PM ET Friday. Funding rates are calculated hourly and settled in cash through margin accounts, with a maximum leverage of approximately 6.7x under the 15% statutory minimum margin for security futures.
c. Kraken (Bitnomial Exchange, LLC): Kraken submitted its rule change simultaneously on September 18 through Bitnomial, a derivatives exchange under its parent company Payward. As a key partner for Kraken in the U.S. regulated derivatives market, Bitnomial set a 15.25% customer margin floor for unhedged positions. Through this channel, Kraken and other mainstream U.S. retail platforms will be able to rapidly distribute onshore U.S. stock perpetual products to compliant users.
d. Crypto.com (Nadex / OG.com): North American Derivatives Exchange (Nadex, now also operating as OG.com Markets under Crypto.com's North American derivatives system), after receiving SEC confirmation of its Form 1-N filing, formally submitted an application to the CFTC on September 24 to add "Rulebook Chapter 16," specifically establishing cash-settled perpetual single-stock futures (Perpetual SFPs) trading and real-time funding rate pricing mechanisms. Notably, Robinhood has recently designated OG.com as its clearing infrastructure partner for prediction markets, indicating considerable spillover potential for this license.
It should be emphasized that obtaining approval does not mean any stock can be listed without restriction. Exchanges must still comply with previously submitted listing standards, including the underlying stock's free float size, trading volume, pricing reliability, and the market's resilience to manipulation. Simply put, regulators have opened the door, but which specific stocks can become underlying assets for perpetual futures will be screened by exchanges according to their rules.
The Next Wave: Lighter and Hyperliquid Poised to Enter
In addition to the four centralized licensed institutions above, crypto-native decentralized perpetual futures exchanges (Perp DEXs) are also actively pushing toward compliance, seeking a share of this trillion-dollar pie.
Among them, Lighter has the clearest progress.
During the Q3 investor call held on October 21, Lighter founder Vladimir Novakovski stated that the team plans to apply to the CFTC for Designated Contract Market (DCM) status in November, while also applying for Derivatives Clearing Organization (DCO) registration. The former corresponds to the trading venue, while the latter handles post-trade clearing and risk management.
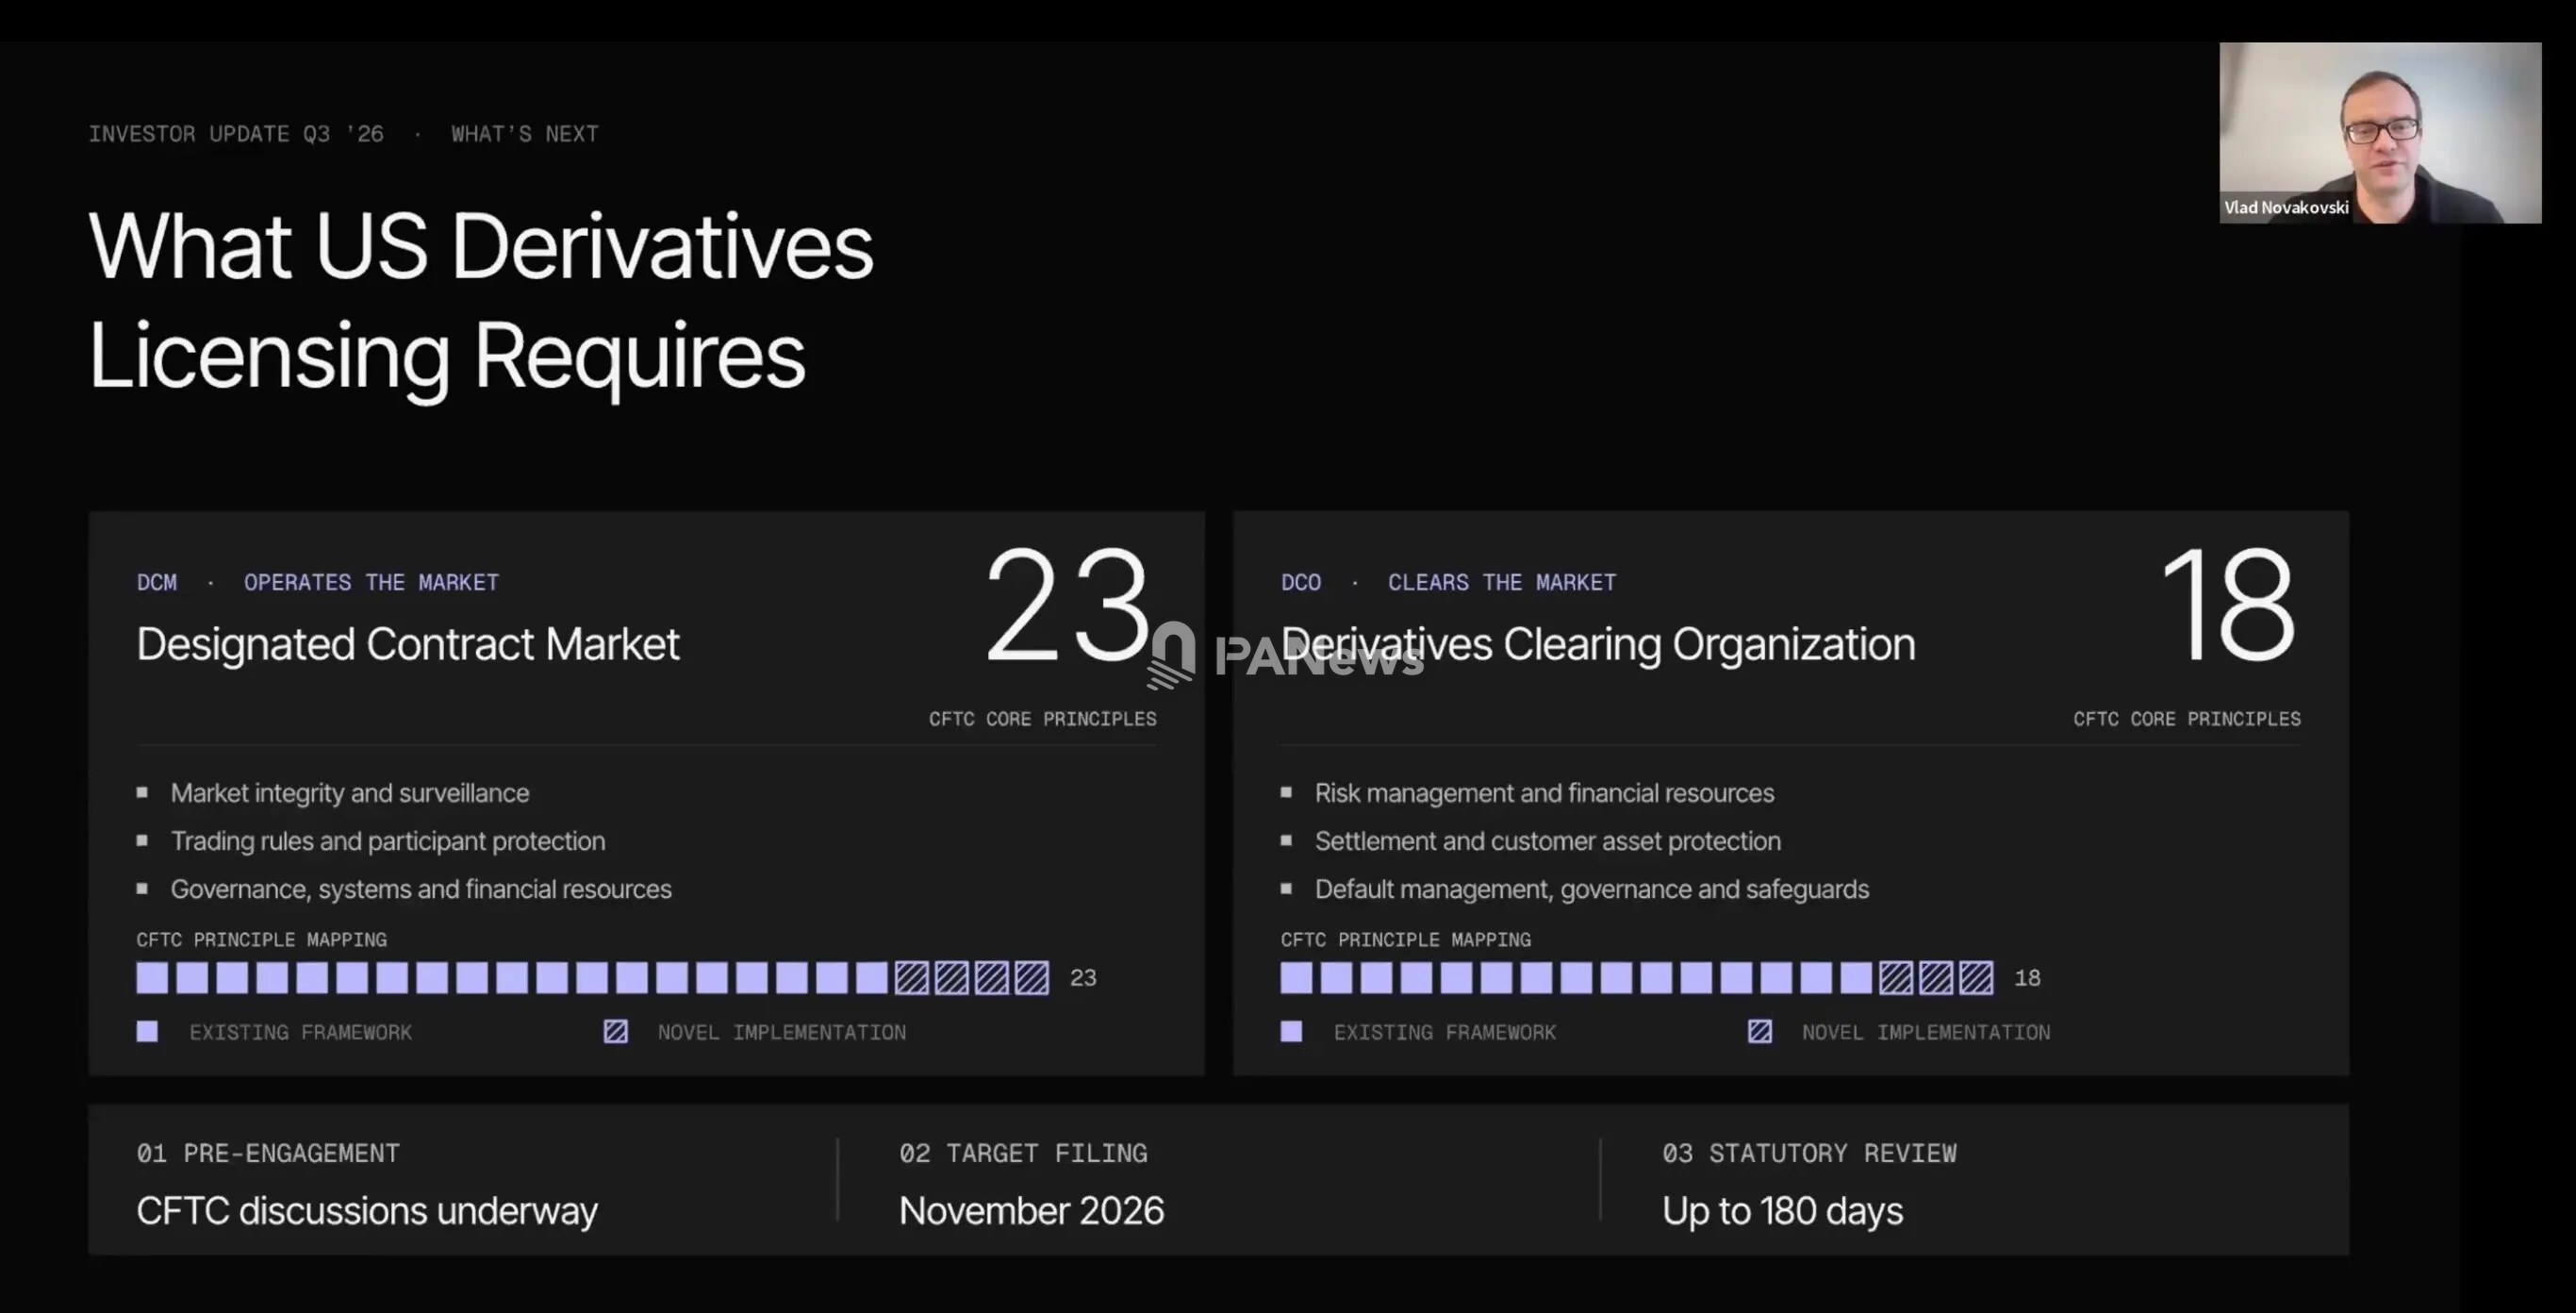
Vladimir stated at the time: "After submitting the application, regulators have a statutory review period of up to 180 days. Because we have already engaged extensively with the CFTC in the earlier stages and completed all preparatory work, we expect the subsequent review process to proceed very smoothly."
Hyperliquid is also making moves, though its path appears slightly different.
In August of this year, Trump publicly stated that CFTC Chairman Selig was pushing for Hyperliquid to enter the U.S. market in a fully compliant and legal manner. The Hyperliquid Policy Center, a policy advocacy group closely associated with Hyperliquid, subsequently submitted comments to the SEC and CFTC arguing that perpetual contracts with futures characteristics should be classified as security futures, thereby allowing exchanges regulated by both agencies to participate in this market.
On October 29, Intercontinental Exchange (ICE), the parent company of the NYSE, announced a partnership with TradeXYZ, a HIP-3 market in the Hyperliquid ecosystem, to establish a regulated perpetual futures market and clearing system based on Hyperliquid in the United States. This proposal still requires regulatory approval, but it offers another possibility — Hyperliquid does not necessarily need to convert its existing DEX directly into a U.S.-licensed exchange; it could also establish an independent compliant market through partners while continuing to provide underlying infrastructure.
Wall Street Strikes Back at Lightning Speed, Demanding CFTC Revoke Approval
However, just as the CFTC opened the door to equity perpetual futures, Wall Street's counterattack has already arrived.
On November 3, the Capital Markets Alliance (CMA), a lobbying group backed by Cboe Global Markets, Citadel Securities, and the Healthy Markets Association, filed a lawsuit in the U.S. District Court for the Southern District of New York seeking to vacate the CFTC's approval of equity perpetual futures.
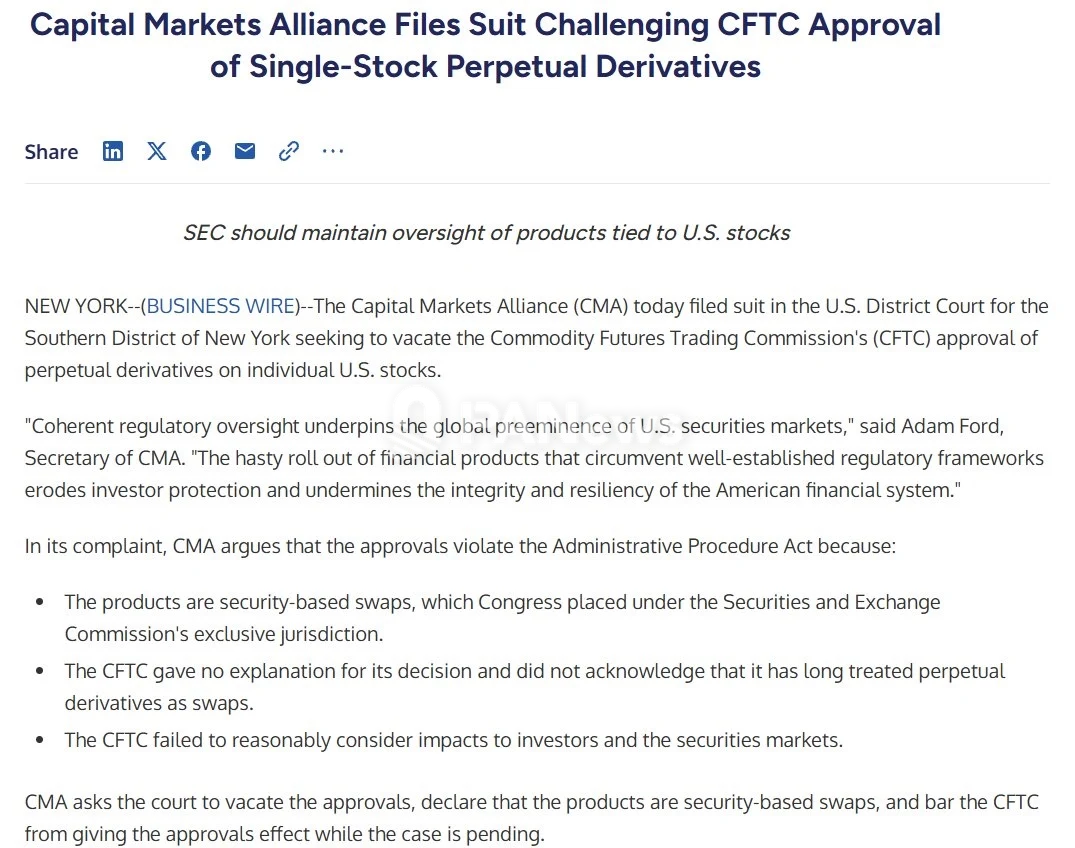
The CMA's core argument is that because perpetual contracts have no expiration date, they do not meet the statutory definition of traditional "security futures" and are legally本质 "securities-based swaps." Under U.S. law, single-stock swap products fall under the SEC's exclusive jurisdiction, and the CFTC has no authority to unilaterally approve them.
Additionally, the CMA alleges that the CFTC's decision violates the Administrative Procedure Act (APA), arguing that the CFTC bypassed formal rulemaking and comprehensive review procedures by hastily launching the product through a 45-day auto-effectiveness mechanism. CMA Secretary Adam Ford criticized the move, stating: "Rushing to launch financial products that circumvent well-established regulatory frameworks undermines investor protection and damages the integrity and resilience of the U.S. financial system."
Beyond the CMA filing suit, the Securities Industry and Financial Markets Association (SIFMA) and Nasdaq have also recently submitted opposition letters to the SEC, warning that equity perpetual futures face thin liquidity during overnight trading hours, making them highly susceptible to price manipulation and cascading retail liquidations. They called on the SEC to exercise its statutory authority to emergency-vacate the four exchanges' rule changes within the 60-day window following CFTC approval.
Wall Street's sensitivity is easy to understand — for traditional options and futures giants like Cboe, zero-days-to-expiry (0DTE) options and traditional stock options are core profit drivers. Once "equity perpetual futures" — which require no rollovers, are intuitive to trade, and support near-round-the-clock trading — become widespread on platforms like Coinbase, Kraken, and Kalshi, traditional options markets and market makers' order flow will face serious diversion.
A Confrontation Destined for the Regulatory History Books
The confrontation of November 3 is destined to go down in the annals of U.S. financial regulation. On one side is a historic opening by regulators, attempting to bring the "perpetual futures" mechanism — proven successful in crypto markets — into U.S. stocks and pull offshore liquidity back onshore. On the other side, Wall Street incumbents like Citadel and Cboe are raising the banner of securities law and building a defense line in federal court.
Over the next 60 days, whether the CFTC and SEC can withstand pressure from Wall Street, and whether the federal court will issue a temporary injunction, will directly determine whether Coinbase and Kalshi can successfully ring the first "opening bell" for U.S. stock perpetual futures — and whether on-chain newcomers like Lighter and Hyperliquid can truly embrace their own "Wall Street moment."