



Author: Zhou, ChainCatcher
Circle released its Q3 2026 earnings before the U.S. market opened on November 4, with both revenue and earnings per share beating market expectations — the company's first solid report card after two consecutive quarters of revenue misses.
But the beat was driven primarily by one-time revenue from the ARC token presale for Arc, the company's native blockchain. Meanwhile, Circle disclosed that it had cut about 5% of its workforce.
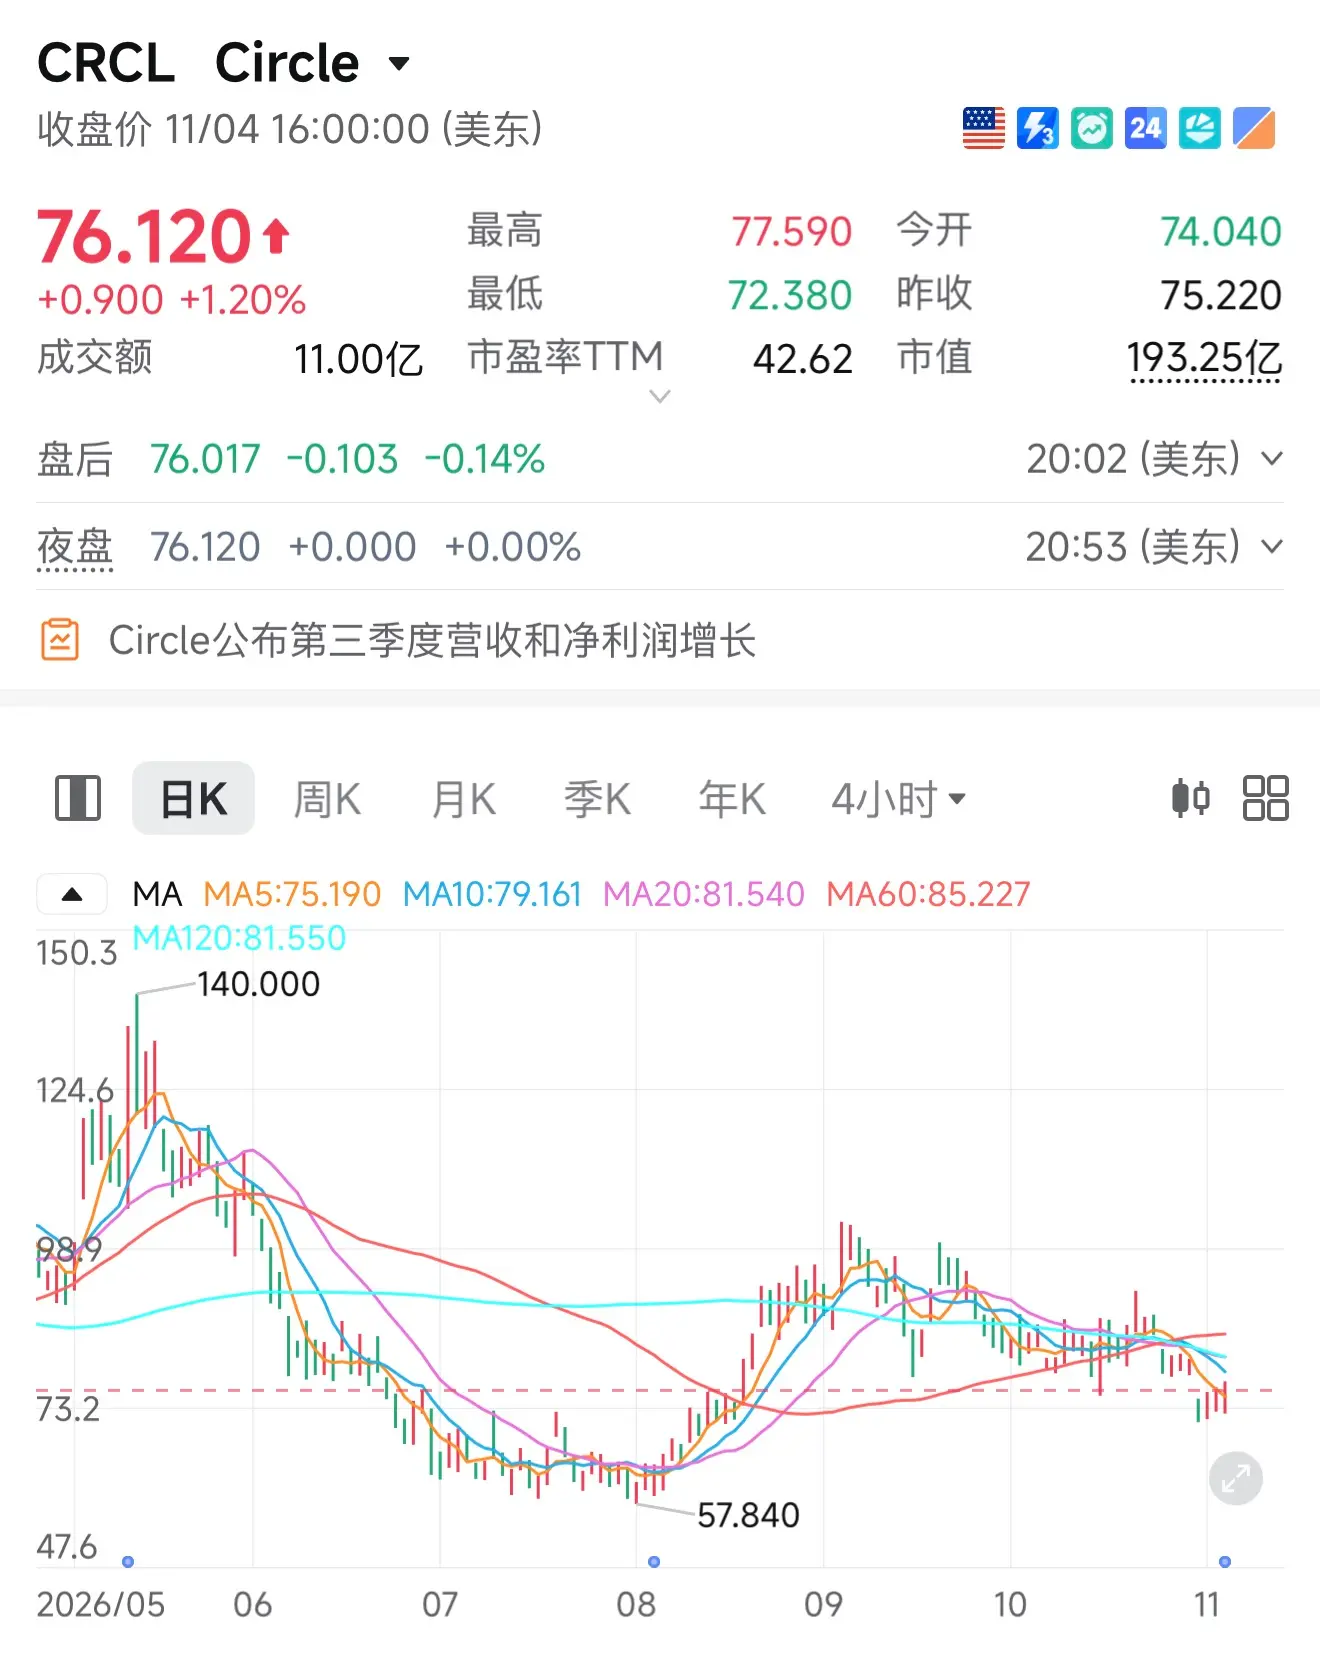
After the report, Circle's stock rose in premarket trading before reversing course, eventually closing up slightly at $76.12, with a total market cap of nearly $20 billion.
1. The Beat Was Largely Carried by the ARC Presale
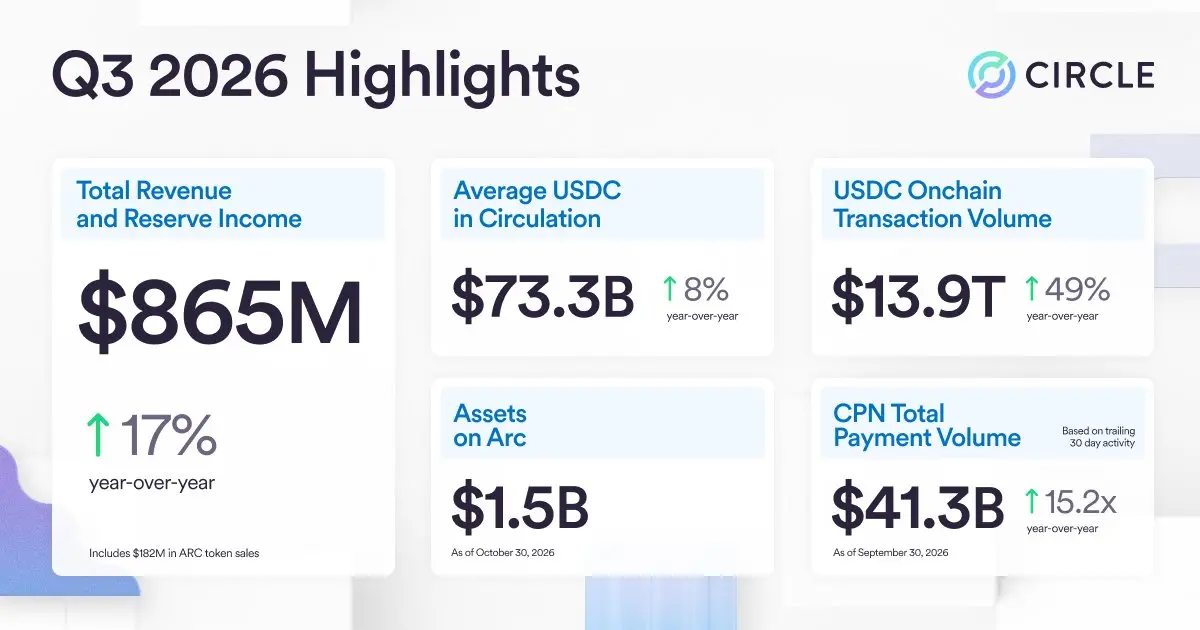
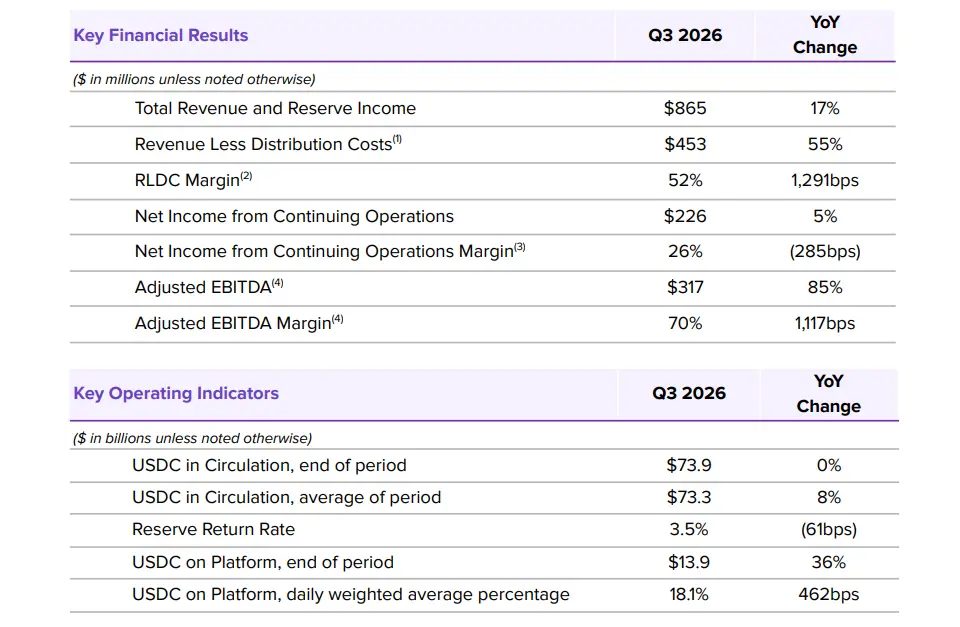
Circle's Q3 total revenue and reserve income came in at $865 million, up 17% year-over-year. Net income from continuing operations was $226 million, up 5% year-over-year. Adjusted EBITDA was $317 million, up 85% year-over-year. Diluted earnings per share were $0.84, versus market expectations of $802 million in revenue and $0.40 per share.
The beat came mainly from other revenue. Other revenue for the quarter was $207 million, up 627% year-over-year, of which $182 million came from the ARC token presale.
The ARC presale was completed in two rounds, raising approximately $242 million in total. CFO Jeremy Fox-Geen explained on the earnings call that presale revenue is recognized based on performance milestones, and with token delivery completed and the Arc mainnet live, about 75% was recognized in Q3.
This revenue carries no corresponding distribution costs, making its profit contribution more pronounced. Revenue less distribution costs, or RLDC, reached $453 million, up 55% year-over-year, with the RLDC margin rising from 41% in Q2 to 52%. The adjusted EBITDA margin was 70%, or 50% excluding ARC.
2. Excluding ARC, Core Revenue and Profit Declined Year-over-Year
Based on the reported figures, excluding presale revenue, Circle's Q3 revenue was approximately $683 million, down about 8% year-over-year and also below the prior two quarters. Adjusted EBITDA was approximately $135 million, down about 21% year-over-year, and pre-tax profit was approximately $46 million, the lowest so far this year.
The main culprit was lower reserve income. Q3 reserve income was $658 million, down 8% year-over-year, as the reserve return rate fell 61 basis points year-over-year to 3.54%, with only part of the decline offset by an 8% increase in average circulation.
Other businesses failed to pick up the slack. Excluding the presale, other revenue was just $25 million, down 11% year-over-year, which Fox-Geen attributed to fewer blockchain integration projects monetized during the quarter.
Margins also came under pressure. Excluding the presale, the RLDC margin was 39.7%, down about 150 basis points from Q2. The net reserve margin fell about 80 basis points quarter-over-quarter to 37.8%, which Fox-Geen said was the first full quarter of the revenue-sharing arrangement with Hyperliquid.
Even including presale revenue, net income grew only 5% year-over-year, mainly because the year-ago quarter included roughly $61.3 million in income tax benefits, creating a high base.
3. USDC Circulation Stagnant as Circle Ramps Up Distribution to Meet Competition
The reserve return rate tracks interest rates, and what Circle can actively pursue is circulation scale — but that metric was also lackluster. At the end of Q3, USDC circulation stood at $73.9 billion, flat year-over-year, with average circulation for the quarter also below Q2.
Meanwhile, total stablecoin supply grew 8% year-over-year to about $274 billion, while USDC's market share fell to 27%, down 183 basis points year-over-year — a notably larger decline than in Q2.
At the end of June, Open Standard, together with Visa, Mastercard, Stripe and more than 140 other institutions, announced the launch of Open USD, a yield-sharing stablecoin, sparking concerns about USDC's distribution advantage.
CEO Jeremy Allaire said on the call that Circle will continue to increase distribution investment, acknowledging that there is a trade-off between partner incentives and circulation growth.
Binance is the latest example. The two sides signed a new five-year agreement, with Binance also investing $100 million in Circle. Specific economic terms were not disclosed, and Fox-Geen said the renewal involves no upfront fees. Regarding Binance's recent security incident, Allaire said Binance had recorded about $2.5 billion in net inflows over the past 24 hours.
As for flat circulation, Allaire attributed it to weakness in the crypto market and stressed that usage continues to grow. According to him, USDC accounted for 79% of stablecoin transaction volume with about 27% of supply share, up from 66% a year earlier. On-chain transaction volume for the quarter was $13.9 trillion, up 49% year-over-year, while minting and redemptions totaled $208 billion, a quarterly record.
Circle is maintaining its multi-year target of 40% compound annual growth in circulation, and Fox-Geen expects usage growth to drive circulation back up over the long term.
4. About 5% of Staff Cut; CFO to Step Down at Year-End
In the same quarter that core revenue declined, Circle carried out layoffs. The company disclosed in the notes to its financial statements that it cut about 5% of its workforce in Q3 and recorded $9.1 million in restructuring charges, mainly cash expenses such as severance.
Officials said the adjustment was intended to align the organizational structure with the company's operating model and strategic priorities. According to Circle's annual report, the company had about 1,100 employees as of the end of 2025, implying the layoffs affected roughly 55 positions.
The layoffs did not lead to cost contraction. Fox-Geen said adjusted operating expenses grew year-over-year, mainly due to investment in Arc and AI-related infrastructure, as well as marketing spending including the Chelsea sponsorship. Q3 marketing expenses doubled year-over-year to $11.3 million, while IT infrastructure costs rose about 90% year-over-year.
Circle announced in September that CFO Jeremy Fox-Geen will step down by year-end, and the company is searching for a successor.
5. Arc Completes Genesis Mint of 10 Billion ARC; Shift to PoS to Monetize Through Staking
Among new businesses, Allaire called Arc Circle's biggest platform bet since USDC. The Arc mainnet went live on September 16, operated by 11 founding validator nodes, with more than 100 institutions and applications onboarded, including financial institutions such as BNY and HSBC and Visa, as well as DeFi protocols like Aave and Uniswap. As of late October, on-chain assets stood at about $1.5 billion.
During Q3, Circle completed the genesis mint of 10 billion ARC, becoming the first publicly listed company to mint a network token for a new L1 blockchain. Circle holds 25% of the total, and Arc plans to transition to PoS in 2027.
Fox-Geen outlined three monetization paths for Arc, all of which flow into other revenue. Staking rewards are expected to be the primary recurring revenue source, with Circle staking its ARC holdings and earning rewards as a validator after PoS. The company may also selectively sell ARC, with proceeds recognized directly in profit. ARC distributed to ecosystem participants is recognized as revenue at market value, with an equal amount recorded as distribution cost.
He also noted that under U.S. accounting standards, the value of Circle's ARC holdings is only recognized upon sale or distribution and is not currently reflected in the financial statements.
According to Circle's SEC filing, ARC held by second-round presale investors is locked up for at least one year after Arc transitions to PoS, and cannot be freely transferred until 2028 at the earliest. The risk disclosure also indicates that Circle may need to refund presale proceeds if key milestones are not met.
Against the backdrop of the Binance hack, Allaire also pitched security as a selling point for Arc. He argued that Arc, operated by known institutions, better meets financial institutions' security requirements than permissionless public chains.
6. CPN Payment Volume Nearly Triples in Three Months; Set to Contribute Meaningful Revenue in 2027
CPN's annualized payment volume, calculated on a trailing-30-day basis, reached $41 billion at the end of Q3, up more than 15x year-over-year and nearly 3x from the end of June. As of October 30, that figure had exceeded $58 billion.
In September, Circle announced the acquisition of Singapore-based cross-border payment platform Tazapay for $400 million in Class A shares, with the deal expected to close in 2027. Tazapay has annualized payment volume exceeding $25 billion, about 60% of which already involves stablecoins.
Allaire said Asia is the most active region for Circle's platform, and the company is engaging with the Hong Kong government and is confident about entering Hong Kong's offshore stablecoin regulatory framework.
Fox-Geen revealed that the company has begun charging fees on some CPN traffic and expects CPN to contribute meaningful revenue in 2027 once Tazapay is integrated. Allaire stressed, however, that Circle's goal is to lower the unit cost of payments and that it will not replicate the fee structures of the traditional payments industry.
7. Guidance Unchanged; Q4 Margins to Dip on Binance Incentives
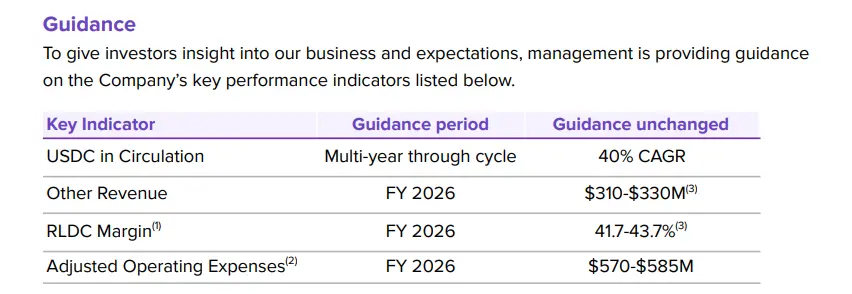
Circle maintained all of its full-year guidance. Full-year other revenue guidance is $310 million to $330 million, with an RLDC margin of 41.7% to 43.7%, both including recognized ARC presale revenue.
On that basis, Q4 other revenue excluding ARC would be approximately $30 million to $50 million, above the $25 million in Q3, and Fox-Geen expects it to recover as blockchain integrations increase.
On margins, the RLDC margin for the first three quarters was about 45.5%. If the full year lands within the guidance range, and assuming Q4 revenue of roughly $700 million, the Q4 RLDC margin would be approximately 29% to 38%, below the roughly 40% level in prior quarters.
Fox-Geen confirmed the Q4 margin decline in response to a Goldman Sachs analyst's question. He said that excluding ARC, the full-year RLDC margin will be near the midpoint of the original 38% to 40% guidance, and working backward shows the Q4 decline, driven by Binance incentive arrangements being fully reflected in a quarter for the first time.
Q4 is also the first quarter in which both the Hyperliquid revenue-sharing arrangement and the renewed Binance partnership are fully reflected. Fox-Geen described both partnerships as investments in distribution aimed at driving USDC circulation and RLDC growth over the long term.
On costs, full-year adjusted operating expense guidance remains $570 million to $585 million, still trending toward the high end of the range. That implies Q4 adjusted operating expenses of approximately $149 million to $164 million, above the $139 million in Q3.
Notably, a retail shareholder asked when non-interest income would become a meaningful contributor, given that USDC adoption is clearly outpacing revenue and profit growth. Allaire responded that CPN monetization, the Tazapay integration and Arc's transition to PoS will together drive revenue diversification.