



Source: Wall Street See
The U.S. Treasury quietly revised its forward guidance on bond issuance, removing a key phrase and opening the door to reducing long-term Treasury issuance starting in 2027. This is the latest in a series of moves by Treasury Secretary Scott Bessent to suppress long-end yields.
On Wednesday, the Treasury announced in its quarterly refunding statement that it would keep nominal coupon-bearing bond and floating-rate note auction sizes unchanged for the next several quarters, but removed the word "at least" that had been in place since early 2024. This subtle wording change means the Treasury has left room to reduce long-term bond issuance as early as 2027.
In terms of market impact, the move is one of a series of actions Bessent has been pushing over the past several months. Just two weeks after the August refunding statement, the Treasury unexpectedly sharply expanded its Treasury buyback program, but the move failed to curb rising long-end yields, with the 30-year Treasury yield briefly climbing to its highest level since 2002 last month.
Dealers had been sharply divided on what changes Wednesday's statement would bring, with some institutions expecting limited adjustments to guidance given that yields had already retreated from early-October highs.
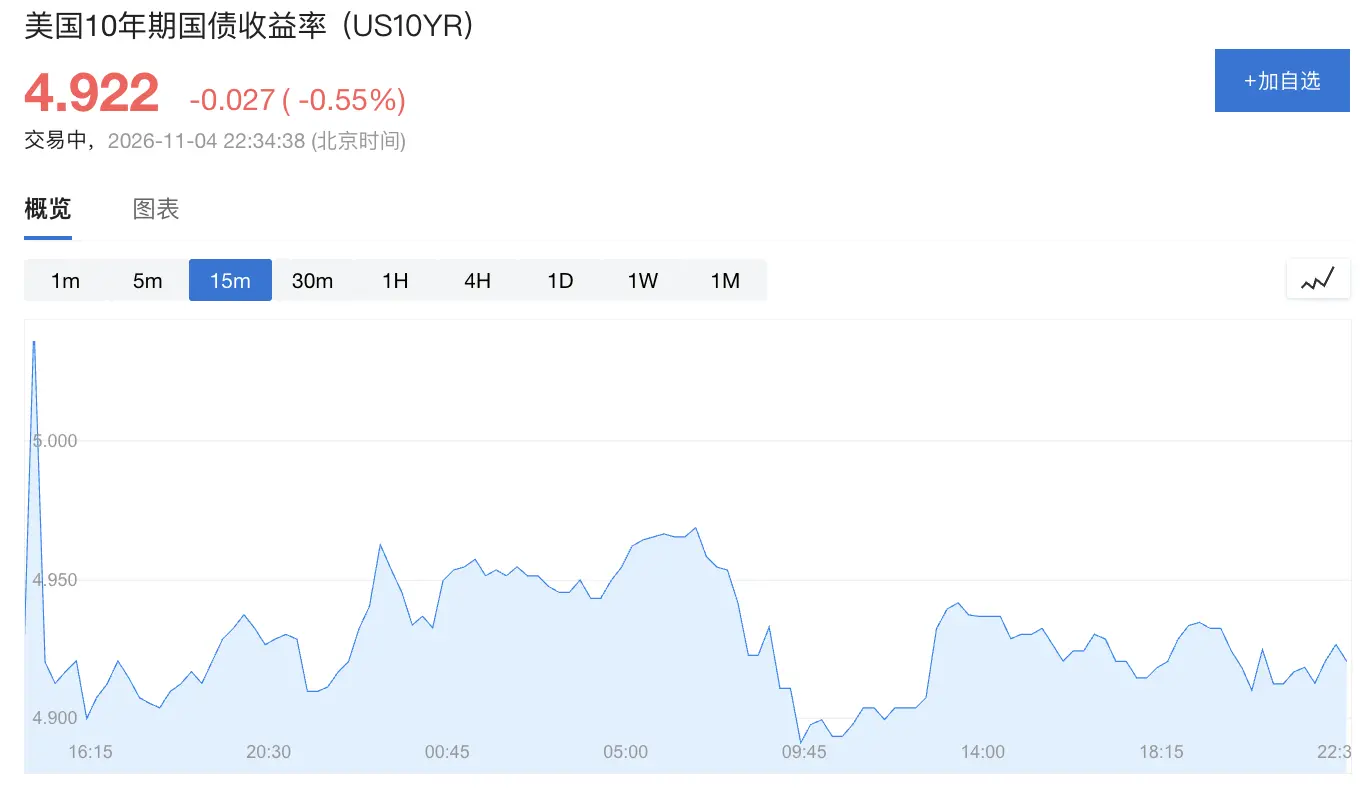
On Wednesday, the 10-year Treasury yield fell 3 basis points to 4.922%.
The Wording Change: Removing "At Least"
The wording adjustment appears minor but is in fact significant.
Since early 2024, the Treasury had consistently said that coupon-bearing bond auction sizes would remain unchanged "for at least the next several quarters," language widely interpreted by the market as ruling out the possibility of reducing supply in the near term. By removing "at least," the Treasury has effectively preserved flexibility to adjust at any time.
As early as February 2025, the Treasury Borrowing Advisory Committee (TBAC)—an advisory group composed of bond investors, dealers and other market participants—had already recommended that the Treasury remove or modify its forward guidance.
In August of this year, TBAC again recommended that the Treasury "consider updating the forward guidance language to preserve operational flexibility through fiscal year 2027."
On Wednesday, TBAC formally recommended in its statement that the Treasury revise its forward guidance language and "emphasized that clear communication and a regularly predictable operating framework are essential to helping market participants adapt to future changes."
Notably, in the previous August 5 refunding statement, the Treasury had already made a preparatory adjustment, changing its assessment language on coupon-bearing bond and floating-rate note size adjustments from "increases" to "changes," laying the groundwork for future supply reductions. The removal of "at least" this time further clarifies that signal.
Buyback Operations: Size Maintained at Triple Level
On bond buybacks, the Treasury said Wednesday that upcoming long-term Treasury buyback operations would have a maximum purchase cap of $6 billion per operation, consistent with recent practice. This size was already triple the original cap.
The Treasury also said it would "continue to assess improvements to buyback operations, including changes to maximum purchase caps, buyback operation scheduling and frequency, bond eligibility criteria and execution processes," hinting at possible further expansion of operations ahead.
However, the expansion of buyback size did not achieve the intended effect of pushing down long-end yields. The 30-year Treasury yield still climbed to its highest level since 2002 last month, indicating that the market's response to the Treasury's series of operations has been relatively muted.
Supply-Demand Imbalance: Weakening Demand for Long-Term Assets from Fixed-Income and Pension Funds
For this quarterly refunding, next week's auction total remains at $125 billion, unchanged for the 11th consecutive time, broken down as follows: $58 billion of 3-year notes on November 9, $42 billion of 10-year notes on November 10, and $25 billion of 30-year bonds on November 12.
The deeper issue lies in the fiscal deficit. The U.S. government's annual fiscal deficit is approximately $2 trillion, driving persistently rising demand for Treasury issuance.
To this end, the Treasury has increasingly relied on short-term Treasury bills maturing within one year. However, short-term bills currently account for a share of total outstanding debt that exceeds historical norms, and because short-term debt must be rolled over at prevailing market rates, the sensitivity of the nation's debt servicing costs to interest rate shocks is rising.
Meanwhile, the Federal Reserve has recently restarted rate hikes for the first time since 2023, with investors expecting further action in the coming months.
On the long-term demand side, officials and market participants alike have noted that in recent years institutional investors such as fixed-income pension funds have shown persistently weakening demand for long-term assets.
In preparing this statement, the Treasury had asked primary dealers through its routine questionnaire about "structural changes" in Treasury investor demand and "how future auction sizes should be adjusted," indicating it is systematically assessing the supply-demand dynamics for long-end bonds.
Since Bessent's predecessor Janet Yellen established the current forward guidance framework, dealers had broadly expected coupon-bearing bond supply to eventually resume growth. This guidance revision marks a fundamental shift in that expectation, and the framework for Treasury-market communication is entering a new phase.
Risk Disclosure and Disclaimer
Markets carry risk; invest with caution. This article does not constitute personal investment advice and does not take into account the specific investment objectives, financial circumstances or needs of individual users. Users should consider whether any opinions, views or conclusions in this article are suitable for their particular circumstances. Invest accordingly at your own risk.