



Source: CICC Research Department
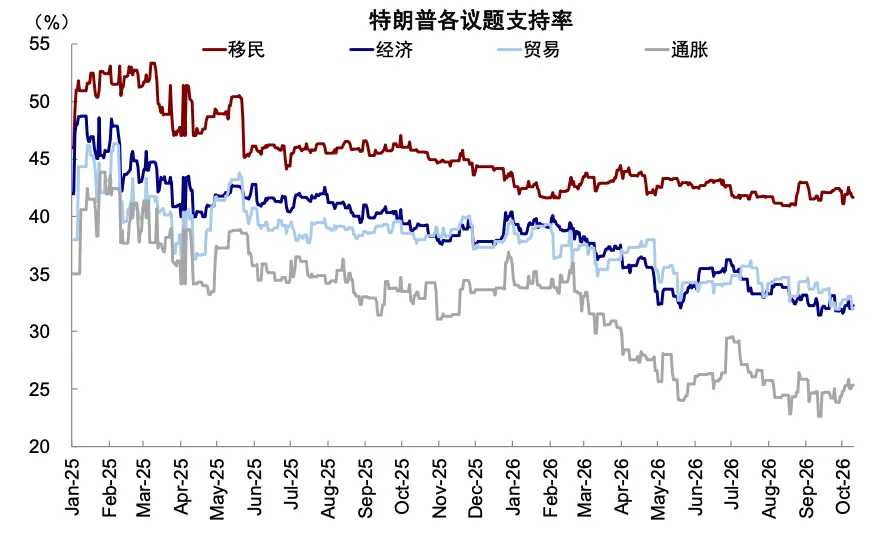
On November 3, the U.S. midterm elections were officially held, and preliminary results indicate that a Democratic sweep is essentially a foregone conclusion. According to data from Polymarket, Kalshi, and others, Democrats are projected to ultimately secure 260 House seats (218 needed for a majority) and 56 Senate seats (51 needed for a majority) (Exhibit 2). The protracted Iran situation and rising inflation have caused many voters to lose patience, and Trump's approval rating had been declining steadily ahead of the midterms, with inflation ranking as the issue on which his approval was lowest (Exhibit 1).
Exhibit 1: The protracted Iran situation and rising inflation have caused many voters to lose patience
Source: Silver Bullet, CICC Research Department
Exhibit 2: The market expects a Democratic sweep of both chambers, with 260 House seats and 56 Senate seats
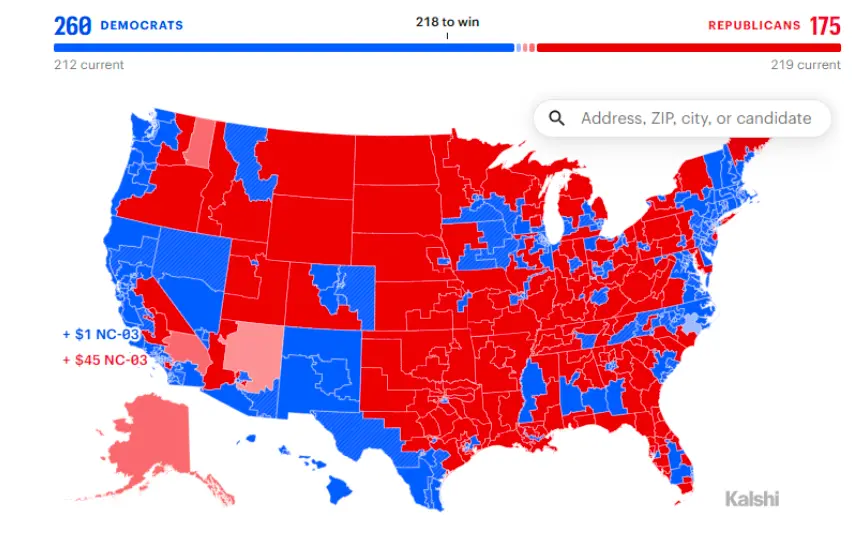
Source: Kalshi, CICC Research Department
The Democrats' advantage has clearly exceeded expectations, particularly with some deep-red states like Texas flipping blue[1], which caught many off guard. This result briefly triggered market concerns about Trump's policy agenda being blocked, increased political brinkmanship, and tighter regulation of AI and cryptocurrencies. As a result, Nasdaq futures at one point fell 2%, while cryptocurrencies and the dollar also weakened. But sentiment subsequently recovered markedly, with the market shifting to trading on the view that a Democratic Congress would constrain Trump's "mistakes" on certain policies.
With substantial uncertainty surrounding both the direction and pace of policy advancement, it seems both the positive and negative market reactions can find justification. In reality, different issues at stake in the midterms can have entirely opposite effects on the same asset.
In our view, the essence of the impact on assets lies in determining whether the dominant force is primarily checks and balances aimed at correcting existing errors (inflation, Iran situation, Fed, tariffs), or primarily obstruction for the sake of opposition (AI, fiscal policy). So what did these midterms change? In which directions is policy advancement more likely? And what does this mean for assets?
How do midterms affect policy? Increased political brinkmanship, more fiscal constraints, and AI facing regulatory constraints
To understand the actual impact of the midterms, one must first understand the boundaries and operating mechanisms of U.S. congressional and presidential power. Simply put, controlling both chambers of Congress does not mean one can "do whatever one wants"—there are still considerable checks and balances and procedural constraints, which means the ultimate results will be concentrated in a few areas.
The Senate and House have different areas of authority. Simply put, the House "controls the purse" (budget, tax, and related issues), while the Senate "controls appointments" (confirmation of presidential nominees). On foreign affairs and trade, Congress has limited say. But the Senate has a "special power" called the filibuster, through which the minority party can make the legislative process extremely lengthy through extended debate, effectively blocking legislation. Therefore, if a party controls only a simple majority in the Senate, such as 51 seats, it will still struggle with many important bills. Otherwise, why has the Republican Party, which currently holds both chambers, been unable to pass the FY2027 budget (which began in October) to this day? But controlling 60 seats is different—a 60-seat supermajority can vote to end a filibuster. So 60 votes is an important "watershed": apart from fiscal budget-related bills that can pass with a simple majority through the reconciliation process, ordinary bills generally require 60 votes to pass. In addition, the president has the power of veto, which would also make Democratic agendas difficult to achieve.
Combining the midterm results with congressional power mechanisms, several points are relatively clear: 1) Trump and his supporters may face investigation pressure. After the 2019 midterms[2], Democrats pushed for Trump's impeachment, though it was largely symbolic (conviction requires a two-thirds supermajority in the Senate). 2) Fiscal brinkmanship will intensify. Implementing the FY2027 budget along the lines Trump envisions will be very difficult—for example, military operations would be affected; but Trump can also veto spending priorities Democrats favor. During this tug-of-war, government shutdowns will increase (though with basically no substantive impact), and debt ceiling risks will rise (currently estimated to be reached in Q2 2027), but the debt ceiling is so important that no one can afford the consequences of default, so it will most likely remain "risky but safe." 3) AI regulation will mainly be determined at the local level, with federal-level legislation very difficult. While the overall direction is as described, the actual outcome depends on the results of bipartisan negotiations and implementation speed, and remains uncertain.
Fiscal policy: intensified brinkmanship makes fiscal expansion difficult; more government shutdown and debt ceiling disruptions
Congress controls America's "purse strings," making it key to fiscal policy implementation and the core battleground of bipartisan contention. Currently, the two parties have significant differences on fiscal issues such as defense and healthcare. Although Democrats could theoretically use the budget reconciliation process after controlling both chambers to bypass the filibuster that requires 60 votes to end, Trump's veto power would still significantly constrain Democratic agendas, ultimately leading to intensified fiscal brinkmanship and making final implementation very difficult.
► Republicans: Fiscal resources tilted toward defense. Trump submitted the FY2027 presidential budget in April 2026, primarily to be implemented through annual appropriations and the budget reconciliation process. According to CBO estimates, Trump plans to increase spending by $117 billion in 2027, of which $98 billion goes to defense (Exhibit 3).
Exhibit 3: Defense spending is a major Trump priority
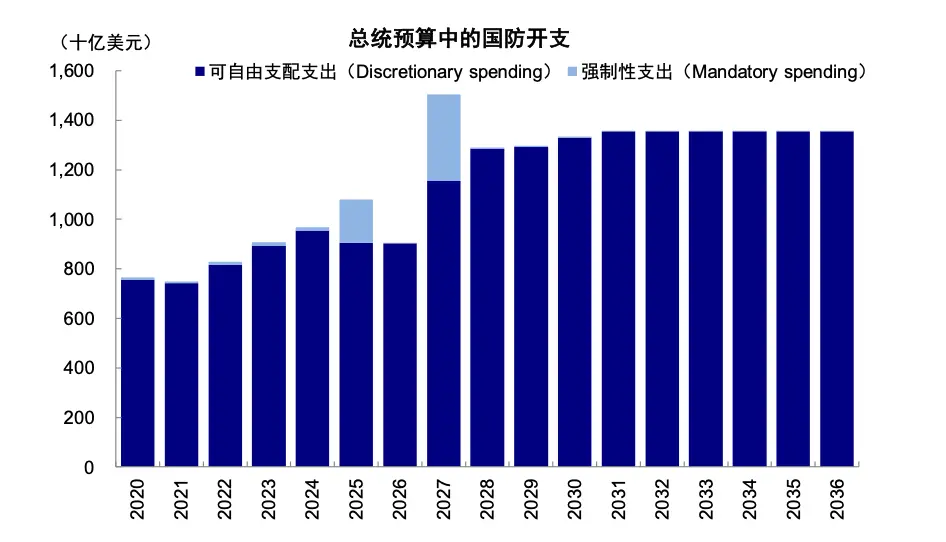
Source: CBO, CICC Research Department
► Democrats: End geopolitical conflicts, strengthen livelihood protection. From the Democratic policy agenda[3], they advocate restoring healthcare coverage (such as ACA and Medicaid), ending military operations against Iran, revoking tariff policies, lowering the cost of living, and strengthening oversight of Trump—clearly different from the policy inclinations reflected in Trump's presidential budget and the "One Big Beautiful Bill."
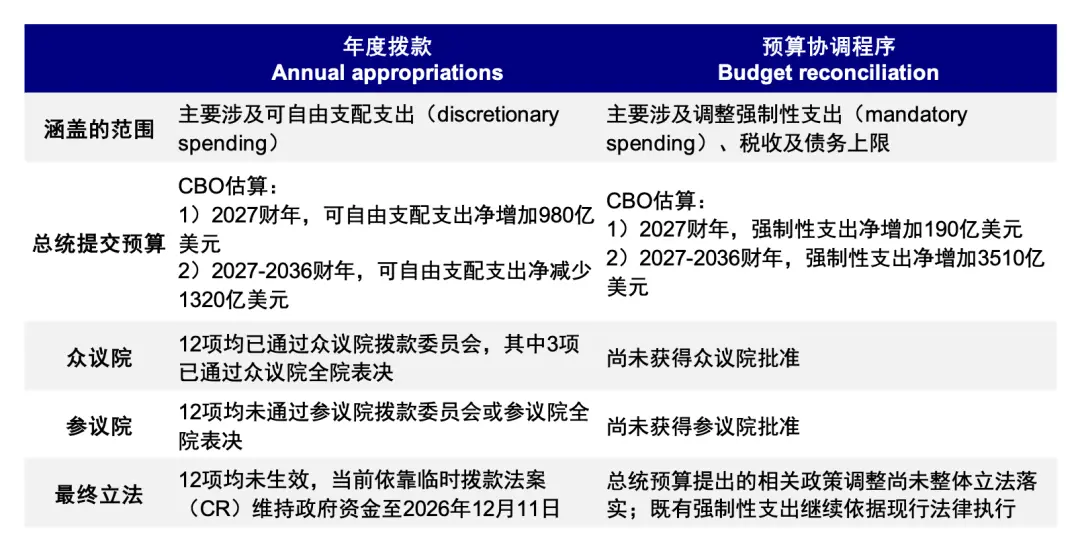
Will the new Democratic-led Congress affect FY2027 fiscal policy? The period from the end of the midterms (November 3, 2026) to the convening of the next Congress (January 3, 2027) is called the "lame-duck session," during which both chambers remain under Republican control. If Republicans can push major FY2027 annual appropriations and new spending proposals through the legislative process (i.e., passed by both chambers and signed by the president) during this period, then even a sweeping Democratic midterm victory would have limited fiscal impact on 2027. However, the current Congress's legislative progress is lagging, and some fiscal disputes may need to be resolved by the new Congress (Exhibit 4).
Exhibit 4: Trump's annual appropriations and budget reconciliation bills are progressing slowly
Source: CBO, CRS, CICC Research Department
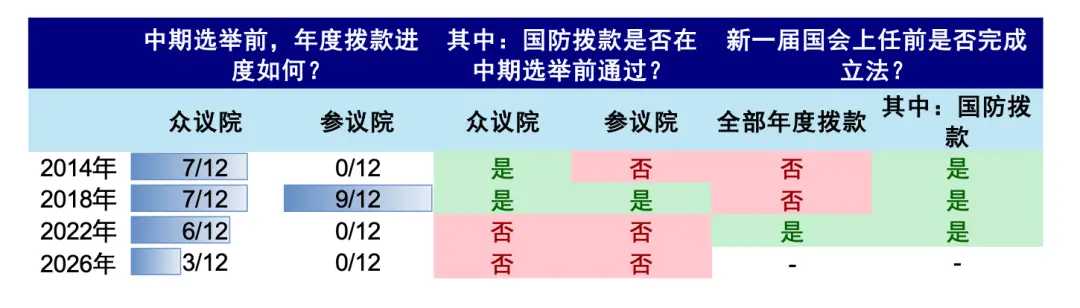
► Annual appropriations: As of before the midterms, only 3 of 12 annual appropriations bills had passed a full House vote, and 0 had passed a full Senate vote—significantly behind the previous three midterm election years (Exhibit 5).
Exhibit 5: Trump's annual appropriations progress lags the previous three midterm election years
Source: Government Shutdown Tracker, CRS, CICC Research Department
► Budget reconciliation: Trump hopes to advance a third round of budget reconciliation legislation (Reconciliation 3.0) to implement his fiscal priorities. But reviewing the previous two reconciliation rounds, from both chambers passing the budget resolution to signing into law, the "One Big Beautiful Bill Act" (OBBBA) took 85 days and the "Secure America Act" took 42 days (Exhibit 6). Currently, even the budget resolution—a prerequisite step for Reconciliation 3.0—has not yet passed both chambers.
Exhibit 6: Reconciliation 3.0 legislative progress is significantly lagging
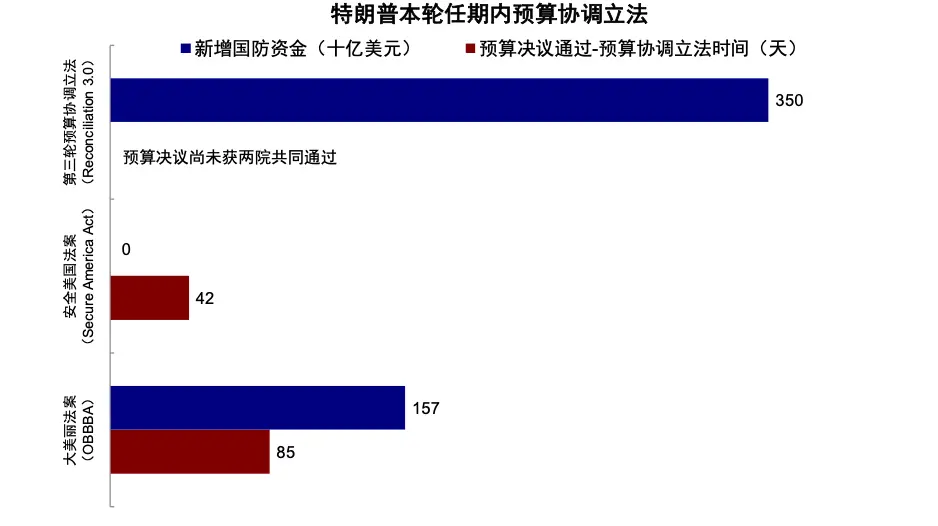
Note: The new defense funding scale in Reconciliation 3.0 is the White House's proposed scale. Source
As bipartisan brinkmanship over fiscal legislation will intensify markedly, we flag rising probabilities of government shutdowns and debt ceiling episodes.
► Government shutdown: A CR extension in December is likely, but shutdown risk rises in H1 next year. The current Congress failed to pass annual appropriations bills before the start of FY2027, and Trump signed a continuing resolution (CR) on September 2, extending existing funding arrangements to December 11. By then, the new Congress will not yet be seated, and Republicans still control both chambers, so passing a new CR smoothly is relatively likely. But if the new CR extends funding into the new Congress's term (the average CR duration is 118 days[4]), then as Democrats take control of Congress, bipartisan fiscal differences could widen further, and government shutdown risk could erupt in H1 next year.
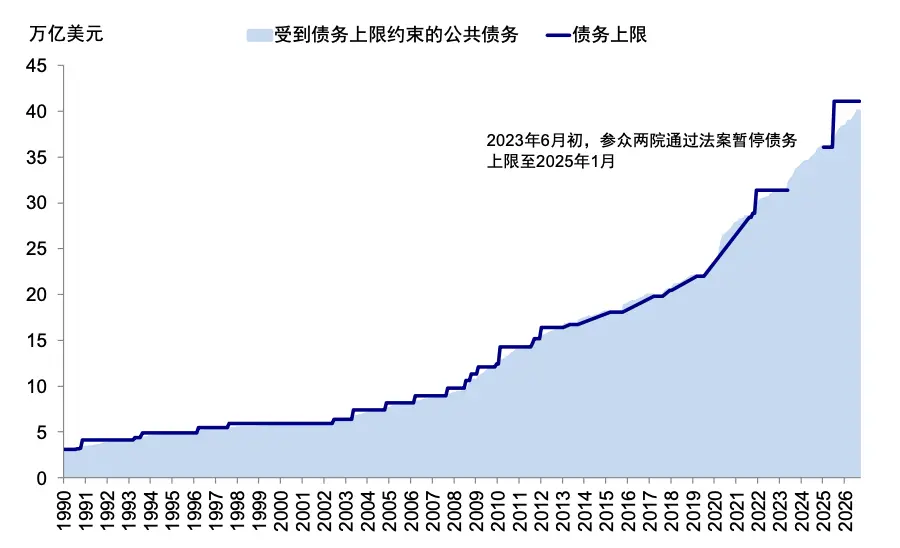
► Debt ceiling: We estimate the U.S. will hit the debt ceiling in Q2 2027, corresponding to reaching the X-date (exhaustion of funds) in Q4 2027. In July 2025, the "One Big Beautiful Bill" raised the debt ceiling by $5 trillion to $41.1 trillion ("Treasuries, U.S. Equities, and Liquidity After the 'Big Beautiful' Bill"). As of October 28, subject-to-limit public debt reached $40.4 trillion, approaching the ceiling again (Exhibit 7). If we assume the FY2027 deficit ratio remains roughly flat and, upon reaching the ceiling, the TGA balance declines 25% from end-2026[5], then the U.S. would hit the ceiling in Q2 2027. According to BPC estimates, after hitting the ceiling, it takes about 6-9 months for funds to be exhausted, implying an X-date around Q4 2027[6].
Exhibit 7: At end-September, U.S. public debt subject to the debt limit reached $39.98 trillion, approaching the $41.10 trillion ceiling
Source: Haver, CICC Research Department
With the two parties checking each other, fiscal implementation resistance rises, and we expect the FY2027 deficit ratio may be flat or expand slightly. Under the scenario of continuing current policies, we expect the U.S. deficit ratio to edge down from 6.18% in FY2026 to 6.14% in FY2027; if all new spending in the presidential budget is implemented, it could rise to 6.52% (Exhibit 8). Considering that defense spending accounts for a large share of the presidential budget (CBO estimates the tilt ratio reaches 84% in the 2027 budget[7]), clearly at odds with Democratic philosophy, we believe fiscal policy is unlikely to be implemented as Trump envisions. But Democrats are similarly constrained, ultimately causing FY2027 fiscal policy to converge toward current policies.
Exhibit 8: In 2027, if current policies continue, the U.S. deficit ratio falls to 6.1%; if the presidential budget is considered, it rises to 6.5%
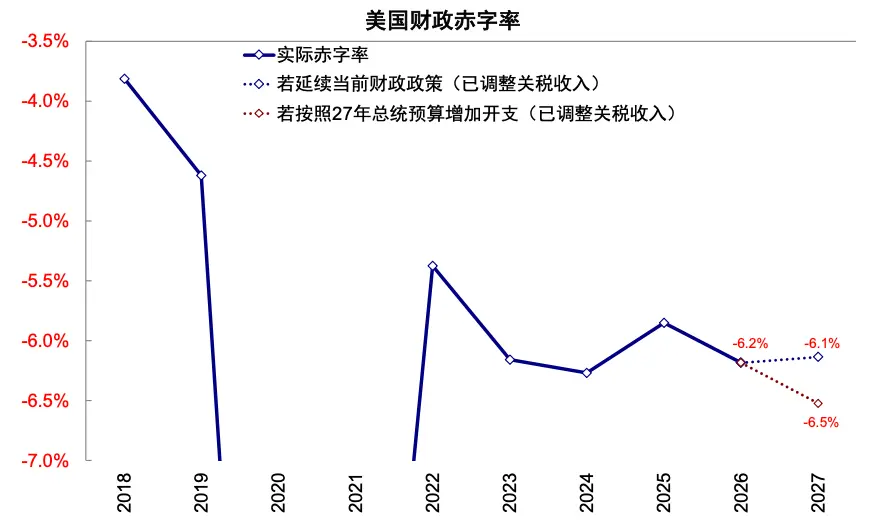
Source: Haver, CICC Research Department
Military: The new Congress can constrain through limiting new military spending and investigations
Congress has limited direct constraints on the president in foreign affairs and military matters. As commander-in-chief, the president enjoys considerable autonomy in directing and executing military operations, and Congress primarily exerts checks through war authorization and legislative restrictions. But in reality, the president can find ways to circumvent some congressional restrictions. In the conflict with Iran, the Trump administration argued that the April ceasefire meant hostilities had ended, so the 60-day deadline under the War Powers Resolution no longer applied[8], and recalculated the deadline after resuming military operations in July[9], thereby bypassing congressional opposition.
The new Congress can check Trump by limiting new military spending. Defense spending is a major priority in the FY2027 presidential budget—Trump wants to increase defense funding by $251 billion through annual appropriations and arrange an additional $350 billion in defense funding through the budget reconciliation process (Exhibit 3). Currently, both legislative processes are progressing slowly, lagging previous midterm election years (Exhibits 5 and 6), and will likely need to be considered by the new Democratic-led Congress.
AI: Democrats also support AI; the disagreement is over regulatory intensity; federal legislation is difficult, but local governments may tighten regulation
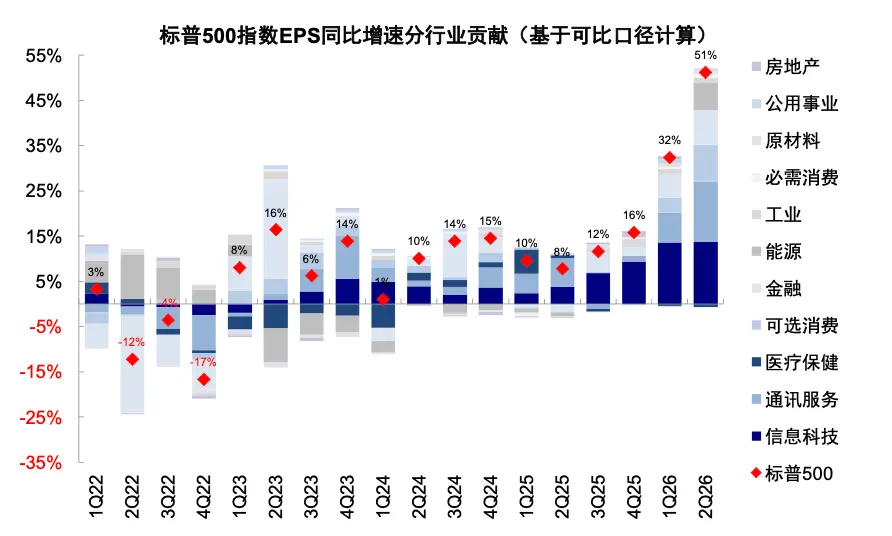
AI contributes significantly to U.S. growth and corporate earnings, and Democrats also support AI development. In Q2, U.S. real GDP grew at a seasonally adjusted annualized rate of 2.2%, with broad AI demand (AI production investment and infrastructure) contributing 28% to U.S. growth, adding about 0.6ppt (Exhibit 9); additionally, AI-related sectors contributed 53% of U.S. equity market gains (Exhibit 10). Therefore, both parties have the willingness to promote AI innovation. In December 2025, House Democratic Leader Jeffries stated that U.S. AI companies should continue to develop and established an "AI and Innovation Economy Committee" to study policies[10]. In February 2026, Democratic and Republican senators jointly proposed the "Future AI Innovation Act," supporting AI R&D and U.S. technological leadership[11].
Exhibit 9: In Q2, U.S. real GDP grew at a 2.2% annualized rate, with AI-related demand contributing 28% of growth
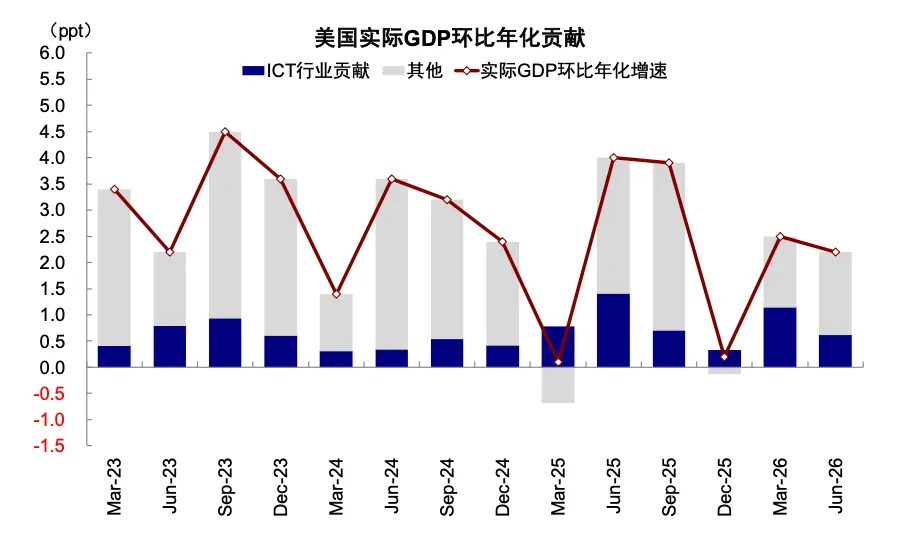
Source: Haver, CICC Research Department
Exhibit 10: In Q2 2026, AI contributed 53% of overall earnings growth
Source: Bloomberg, CICC Research Department
The main disagreement between the two parties is over AI regulatory intensity, and passing federal legislation to strengthen regulation will not be easy for Democrats. In the Trump administration's AI legislative framework, it advocates relying on existing regulatory agencies and industry standards for oversight and opposes establishing new federal AI regulatory bodies[12]. By contrast, Democrats focus more on strengthening regulation—Senate Democratic ranking member Cantwell proposed establishing enforceable frontier model safety standards and requiring covered models to pass independent audits before release[13]. But even if Democrats sweep both chambers, pushing regulatory legislation through remains difficult, because after passing both chambers, the bill could still be vetoed by the president, and overriding a presidential veto requires a two-thirds vote of members present in each chamber[14].
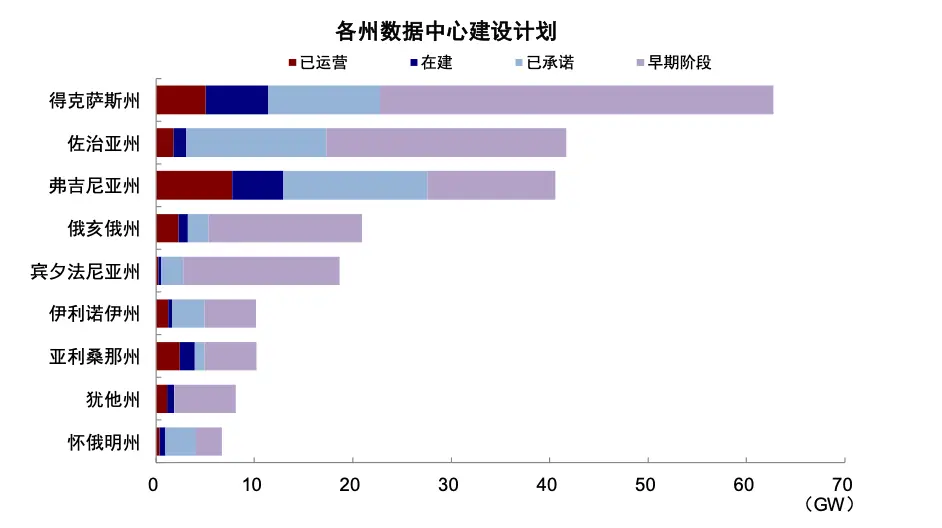
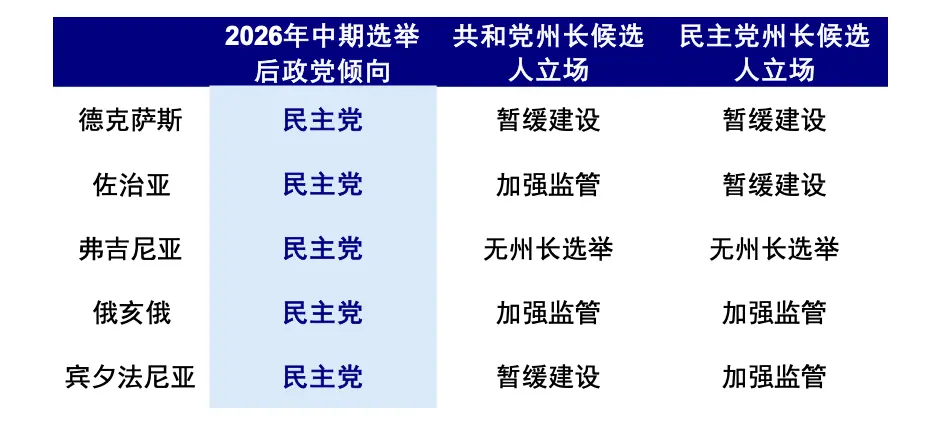
At the local government level, however, gubernatorial candidates from both parties generally favor tightening regulation of AI data centers. According to DC Byte data, the five states with the highest concentration of AI data centers in the U.S. are Texas, Georgia, Virginia, Ohio, and Pennsylvania (Exhibit 11). Among them, Virginia has no gubernatorial election this year; candidates in the other four states all tend to favor tighter regulation of AI data centers, or even pausing construction (Exhibit 12). Based on existing measures, local governments may constrain AI data center construction through electricity costs[15], tax incentives[16], land use[17], and other means.
Exhibit 11: The five states with the highest data center concentration are Texas, Georgia, Virginia, Ohio, and Pennsylvania
Source: BloombergNEF, DC Byte, CICC Research Department
Exhibit 12: Candidates from both parties advocate tightening AI data center regulation, with little difference in stance
Source: Multistate, CICC Research Department
How does a Democratic sweep affect assets? Watch four transmission channels: government shutdown, debt ceiling, fiscal policy, and AI regulation
The same policy has divergent effects on different assets, and short-term and long-term effects may also be opposite. For example, rising political brinkmanship boosts safe-haven demand; constrained fiscal expansion is generally positive for Treasuries, but spending rigidity and default risk would pressure Treasuries and the dollar; blocked personnel appointments are actually conducive to Fed independence; the direction of AI and crypto regulation is clear, but the pace of implementation remains uncertain; an early end to military operations would help oil prices, inflation, and interest rates decline (Exhibit 13).
Exhibit 13: Midterms affect asset performance through different channels
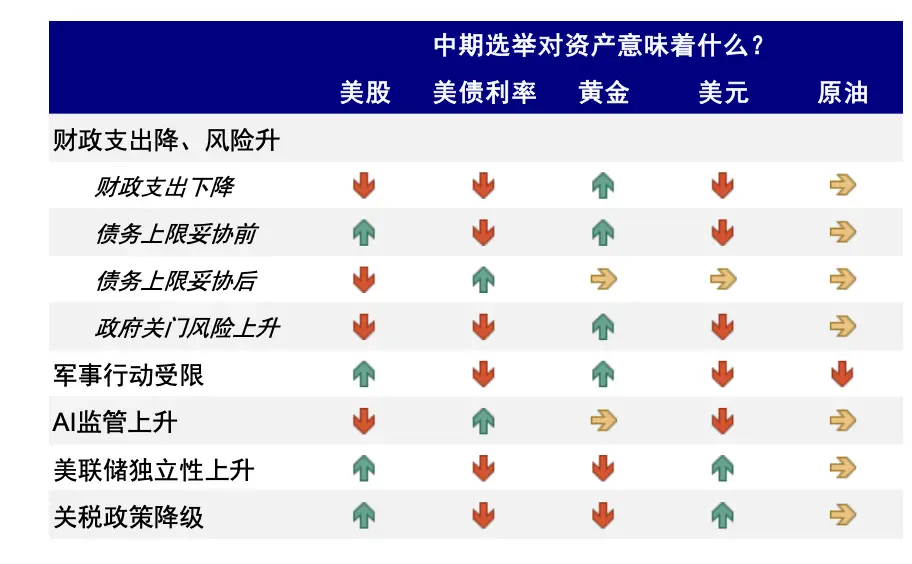
Source: CICC Research Department
Ultimately, the core question for asset pricing is whether the dominant market force is checks and balances aimed at "correcting deviations" (inflation, Iran situation, Fed, tariffs), or disruption driven by "opposition for opposition's sake" (AI, fiscal policy).
We lean toward the view that the former dominates in the short term, which is why U.S. equities mostly rose after the midterms (Exhibit 14)—equities still have support, while Treasury yields and the dollar weakened slightly. But the risks from the latter may rise over time—after all, the closer to the 2028 election, the more intense political brinkmanship will become, especially if AI lacks breakthroughs and the Fed cannot cut rates. If so, U.S. equities, Treasuries, and the dollar would all face pressure.
Exhibit 14: After midterm elections over the past 50 years, U.S. equities have mostly risen
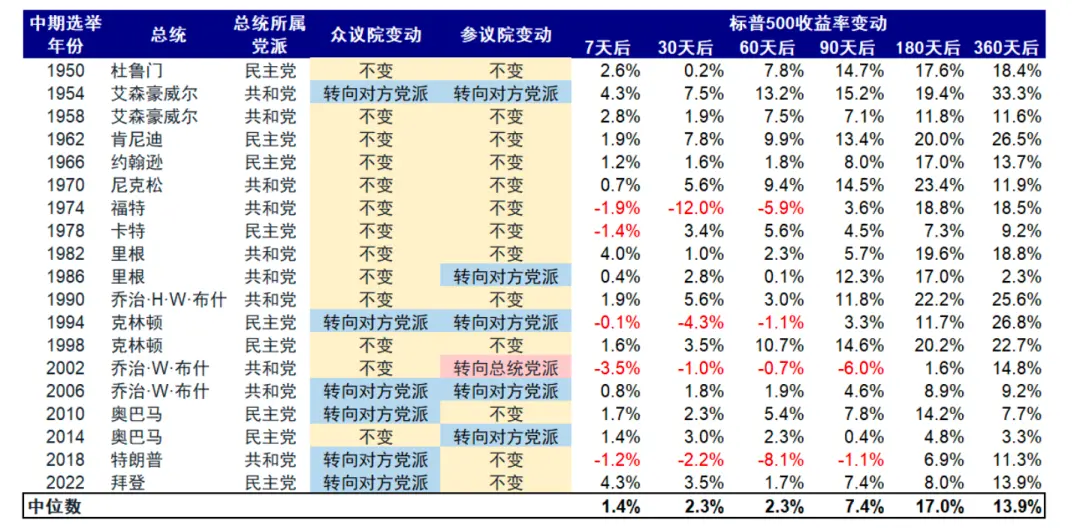
Source: Bloomberg, CICC Research Department
Specifically:
► Government shutdown: Limited market impact, may temporarily boost safe-haven sentiment. Historically, during the past 21 government shutdowns, the median moves in the S&P 500, 10-year Treasury yields, and the dollar index have all been near zero (Exhibit 15). We believe the impact of government shutdowns is limited to sentiment—possibly short-term positive for safe-haven assets, but with no lasting effect.
Exhibit 15: Government shutdowns have limited impact on assets
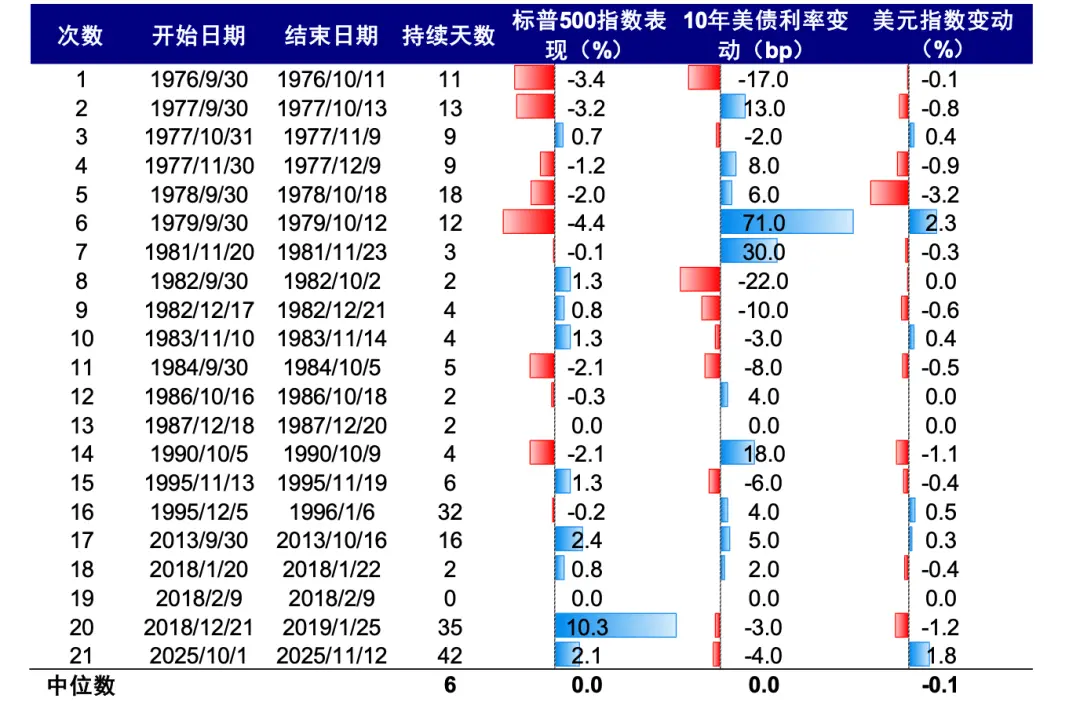
Source: Wind, CICC Research Department
► Debt ceiling: Upon initially reaching the ceiling (Q2 2027), liquidity actually improves, positive for bonds and U.S. equities. At that point, the Treasury will not only stop issuing debt (reducing bond supply) but also draw on TGA cash to cover expenditures, achieving a "liquidity injection" effect (Exhibit 16), providing marginal support for bonds and U.S. equities ("How the Debt Ceiling Can Actually Improve Market Liquidity").
Exhibit 16: The TGA drawdown phase is expected to provide liquidity support
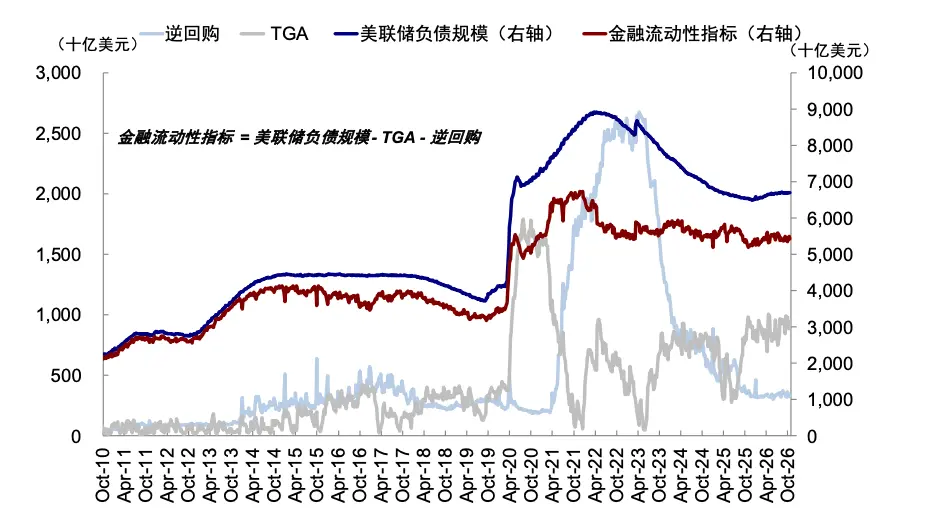
Source: Bloomberg, CICC Research Department
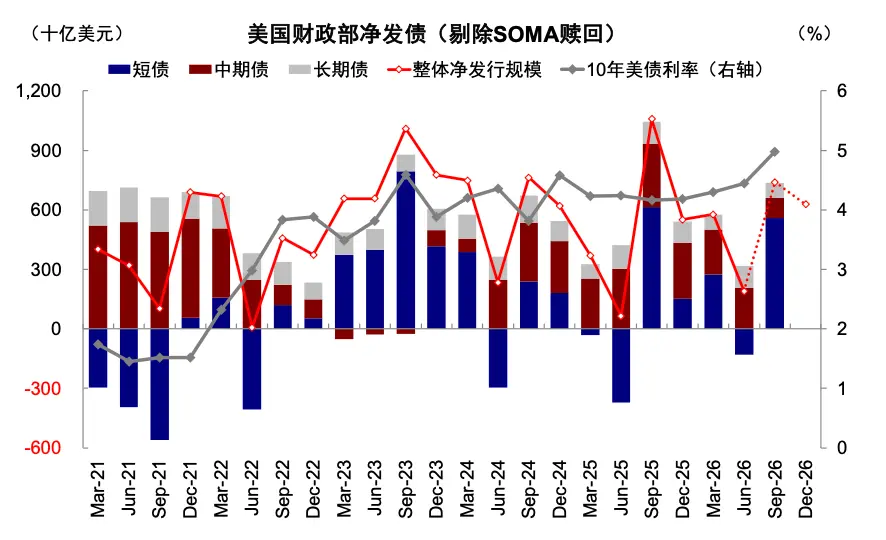
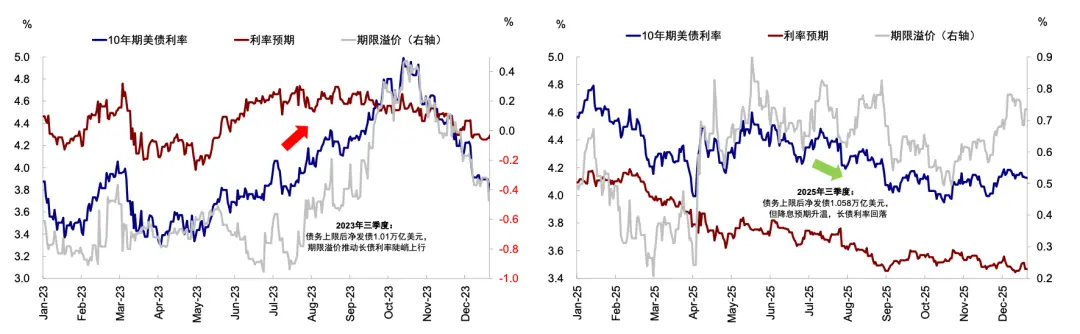
But after the ceiling is resolved (Q4 2027), bond supply and liquidity face temporary pressure, unfavorable for term premiums and U.S. equity performance. After the two parties reach an agreement, the Treasury needs to re-issue debt to rebuild the TGA balance, causing a temporary increase in bond supply and draining some liquidity ("The Debt Ceiling Paradox: Unavoidable Liquidity Tightening"). Looking back at 2023 and 2025: 1) On bond supply, net Treasury issuance in Q3 of both years reached $1.01 trillion and $1.06 trillion, with supply pressure concentrated in the short end—short-term bill issuance reached $794 billion and $613 billion, respectively (Exhibit 18). During the same period, Treasury term premiums rose sharply or remained elevated, with temporary pressure lasting about one quarter (Exhibit 19). 2) On liquidity, within three months after the debt ceiling constraint was lifted, the TGA balance rebounded by $404.1 billion and $447.1 billion, respectively, equivalent to 7-9% of U.S. liquidity at the time (Exhibit 16), marginally weighing on U.S. equities and other risk assets.
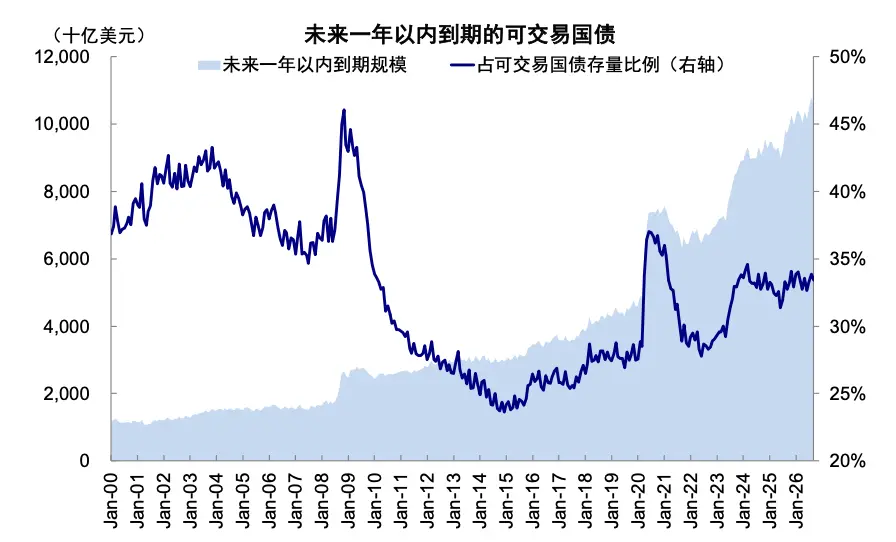
Exhibit 17: As of September 2026, tradable Treasuries maturing within the next year account for about 33.4%, with manageable refinancing pressure
Source: TBAC, CICC Research Department
Exhibit 18: To rebuild the TGA balance, net debt issuance exceeded $1 trillion in Q3 2023 and Q3 2025
Source: Haver, CICC Research Department
Exhibit 19: Due to Treasury rebuilding the TGA balance, after the debt ceiling was resolved in 2023 and 2025, Treasury term premiums rose sharply or remained elevated, with temporary pressure lasting about one quarter
Source: Bloomberg, CICC Research Department
► Fiscal policy: Marginally reduces debt issuance pressure, but unfavorable for traditional demand and cyclical sector earnings recovery. After the midterms, intensified bipartisan brinkmanship may limit fiscal expansion space. Combined with the stable share of tradable Treasuries maturing within the next year (Exhibit 17) and manageable refinancing pressure, we believe Treasury supply pressure may ease. But at the same time, fiscal support for growth will also weaken, especially for traditional demand that is more sensitive to government investment and household purchasing power, potentially constraining cyclical sector earnings recovery.
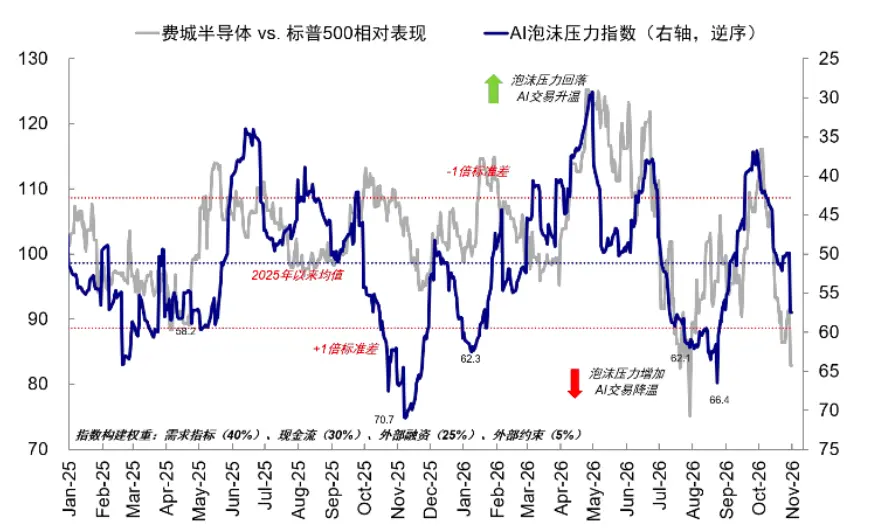
► AI: The key remains AI progress, but local regulation may exacerbate disruptions. As current AI models and applications lack clear progress, market expectations are in a "gap period," compounded by intense capital expenditure continuously squeezing cloud providers' free cash flow, leading to growing concerns about the pace of AI revenue realization and return on investment. Our AI Stress Index has also been deteriorating since end-September (Exhibit 20). If local governments further tighten regulation and raise AI investment costs, it could exacerbate market concerns and trigger temporary disruptions.
Exhibit 20: Our AI Stress Index has continued to deteriorate since end-September
Source: Bloomberg, FactSet, CICC Research Department
Article Source
This article is excerpted from: "Asset Implications of a Democratic 'Sweep'" published on November 5, 2026
Liu Gang, CFA Analyst SAC Registration No.: S0080512030003 SFC CE Ref: AVH867
Hao Yuening Contact SAC Registration No.: S0080125070024