



Original | Odaily Planet Daily (@OdailyChina)
Author | Azuma (@azuma_eth)
Key Takeaways: Circle's record quarterly revenue in Q3 was primarily driven by a one-time $182 million ARC token pre-sale. Excluding this, the core USDC business still faces declining reserve income and flat circulation, placing the company in a transition period between old and new growth drivers.
Key Points:
a. Total revenue and reserve income reached $865 million, up 17% year-over-year, but core reserve income of $658 million fell 8% year-over-year, with the reserve return rate dropping to 3.5%.
b. Other revenue surged 627% year-over-year to $207 million, of which $182 million came from the ARC token pre-sale. Excluding this, recurring other revenue was only $25 million, a notable decline quarter-over-quarter.
c. USDC's average quarterly circulation was $73.3 billion, down 4.2% quarter-over-quarter, with market share at 27%, down 1.83% year-over-year and still well below the 40% CAGR guidance.
d. USDC on-chain transaction volume reached $13.9 trillion, up 49% year-over-year, with 7.3 million active wallets, up 16%, reflecting continued improvement in usage efficiency.
e. USDC held on Circle's own platform reached $13.9 billion, up 36% year-over-year, with its share rising to 18.1%, driving net reserve margin up to 38%.
f. Binance invested $100 million in Circle and expanded strategic cooperation, CPN annualized payment volume reached $41.3 billion, and an agreement to acquire Tazapay was signed.
Before U.S. markets opened on November 4 (Beijing time), stablecoin issuer Circle (NYSE: CRCL) officially released its Q3 2026 earnings report.
According to the report, Circle's Q3 total revenue and reserve income reached $865 million, up 17% year-over-year and a record quarterly high; net income from continuing operations was $226 million, up 5% year-over-year; diluted EPS came in at $0.84, up 31% from $0.64 in the same period last year; adjusted EBITDA was $317 million, up 85% year-over-year.
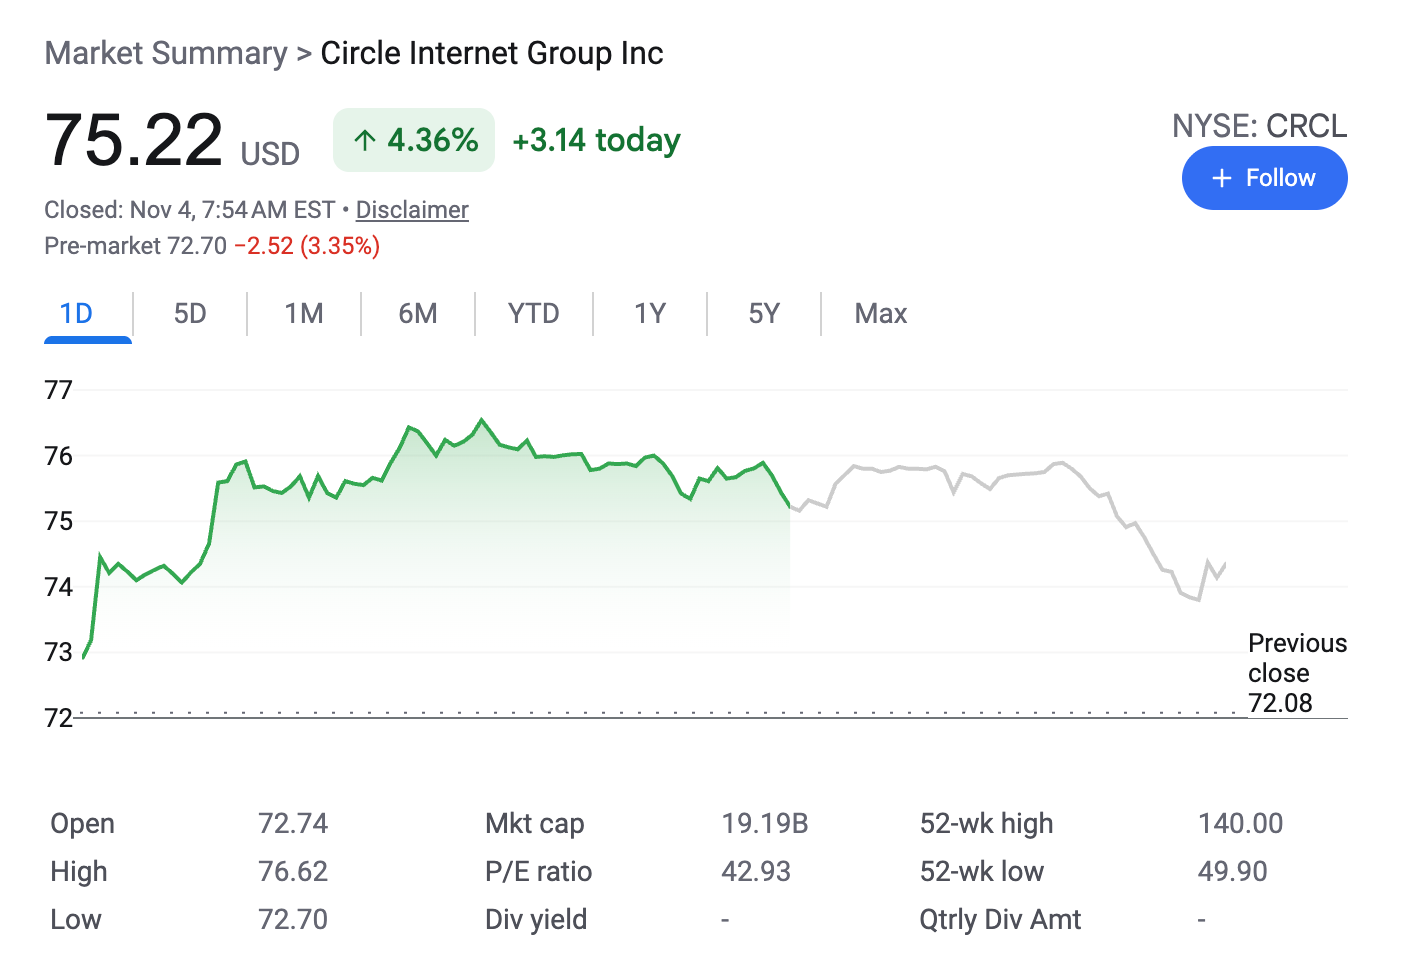
Following the release, CRCL initially rose 3% in pre-market trading, buoyed by multiple record-breaking figures. However, as the market dissected the report more carefully, the stock gradually pulled back and was down 3.35% in pre-market trading as of 20:55 Beijing time.
Core Operating Data: Behind the Record Headline Numbers Lies Some "Accounting Magic"
At first glance, Circle indeed delivered a strong report card in Q3. However, a closer look at the revenue structure reveals that a significant portion of Circle's growth this quarter came from the ARC token pre-sale, while the USDC business itself still faces pressure from declining reserve yield and slowing circulation growth.
Circle's Q3 total revenue and reserve income jumped to $865 million, continuing the recovery trend of recent quarters ($740M ➡️ $770M ➡️ $694M ➡️ $701M ➡️ $865M).
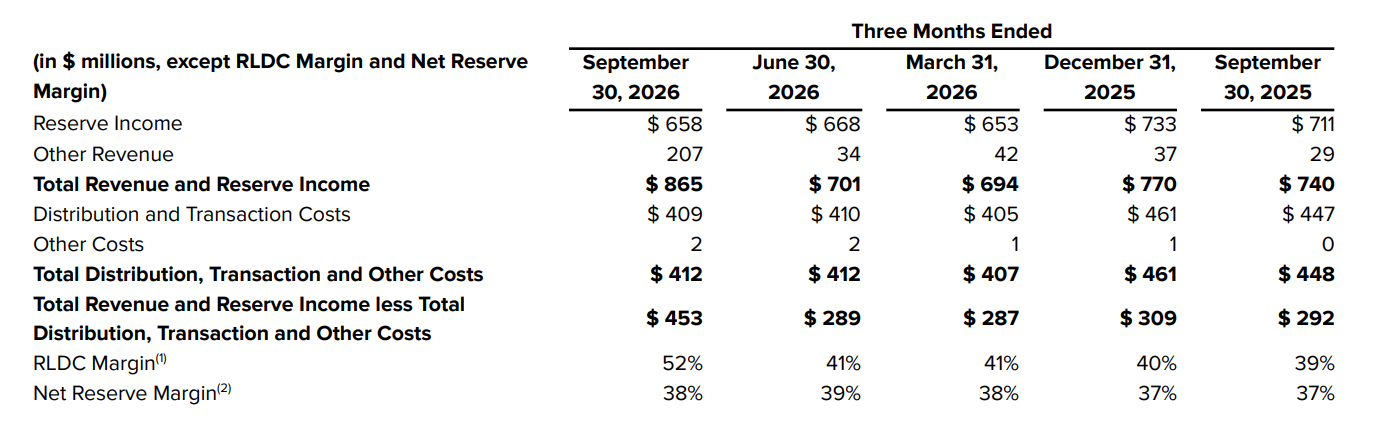
Breaking down the structure, core reserve income came in at $658 million this quarter, down 8% year-over-year and down 1.5% quarter-over-quarter (vs. $668 million last quarter). The year-over-year decline was mainly due to the reserve return rate falling 61 basis points from a high base last year to 3.5%, while the slight quarter-over-quarter decline was primarily dragged by a sequential drop in USDC's average circulation this quarter.
What really drove the record quarterly revenue was other revenue — which surged 627% year-over-year to $207 million this quarter. As we warned in our previous two earnings analyses (see Q1 and Q2 earnings breakdowns), this was mainly due to the formal recognition of $182 million in ARC token pre-sale revenue this quarter. Notably, excluding this one-time token pre-sale, recurring other revenue this quarter was actually $25 million, a notable decline from Q1 ($42 million) and Q2 ($34 million) — the earnings footnotes also acknowledged that this decline stemmed from "a decrease in subscription and services revenue."
Similarly, the surge in RLDC and RLDC Margin in Q3 was largely because the $182 million in ARC revenue, which carries zero distribution cost, was directly included in the numerator — the former reached $453 million this quarter, up 55% year-over-year, while the latter jumped from 41% in the previous two quarters to 52%. Excluding the ARC impact and looking solely at the true profitability of the reserve business, the net reserve margin (i.e., the margin after deducting distribution costs from reserve income) disclosed in the report was 38% this quarter, up 1 percentage point year-over-year and slightly down 1 percentage point from Q2 (39%), remaining broadly stable.
• Odaily note: RLDC refers to revenue less distribution costs, and RLDC Margin refers to the margin after deducting distribution costs from revenue. These two metrics reflect the core business profitability after distribution expenses and are widely regarded as Circle's most critical profitability indicators.
Turning to expenses. Distribution and transaction costs remained Circle's largest expense item at $412 million this quarter, down 8% year-over-year and flat quarter-over-quarter versus Q2 ($412 million).
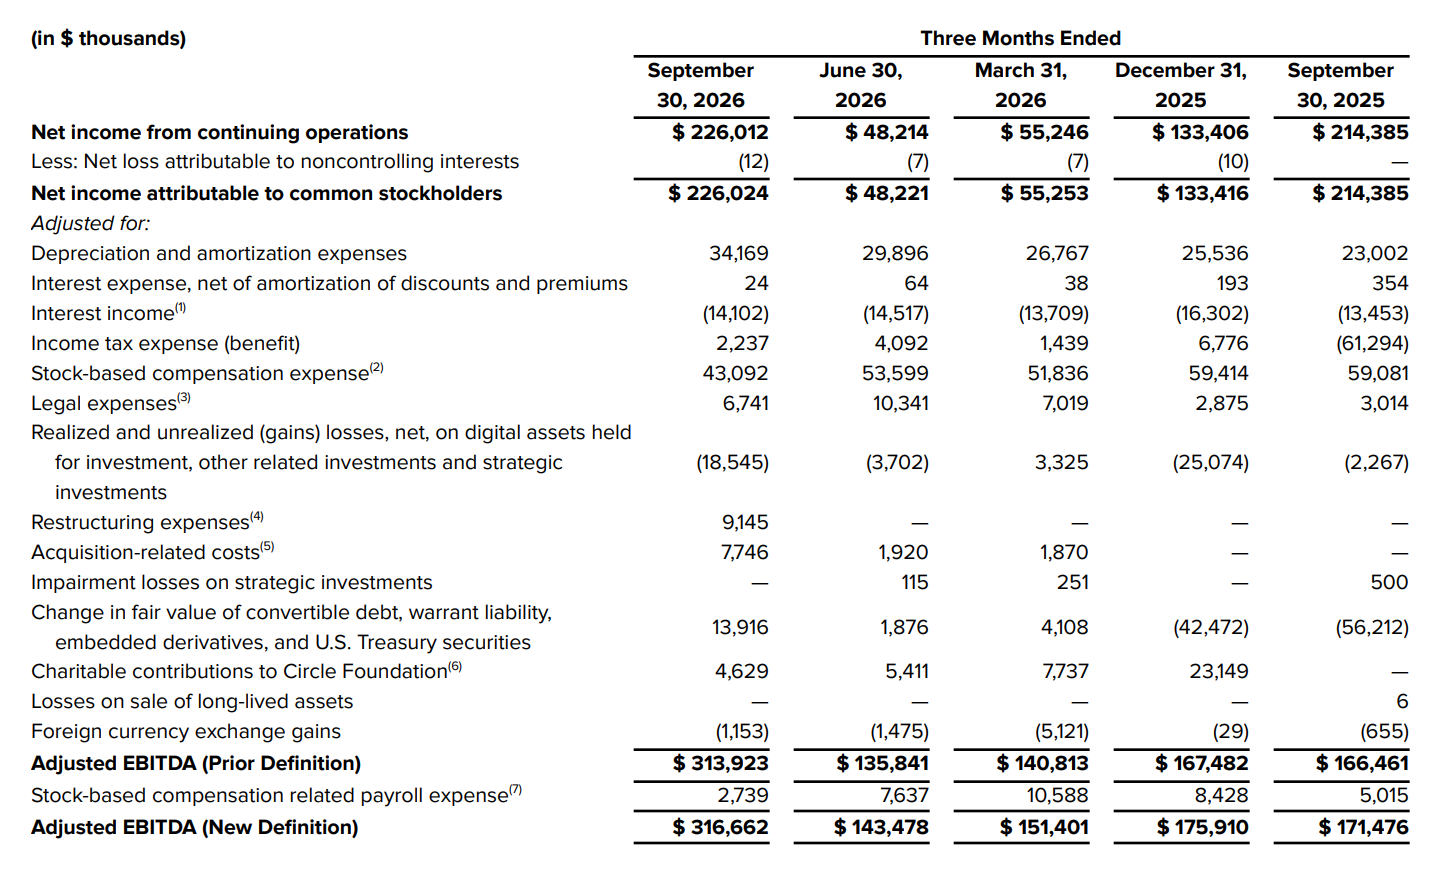
On operating expenses, GAAP operating expenses were $245 million, up 16% year-over-year but down from Q2 ($254 million); adjusted operating expenses, which are more indicative, were $139 million, up 13% year-over-year and down 5.2% quarter-over-quarter (Q2: $146 million).
Breaking down the expense details, IT infrastructure costs nearly doubled year-over-year to $17.92 million, and marketing expenses (including Chelsea FC jersey sponsorship) doubled year-over-year to $11.32 million; however, compensation expenses fell 4% year-over-year to $124 million. The earnings footnotes disclosed that Circle implemented a roughly 5% workforce reduction in Q3, paying $9.15 million in cash severance and restructuring costs, while reversing $5.7 million in stock-based compensation due to forfeited unvested RSUs from departing employees; additionally, $7.75 million in M&A-related legal and professional service fees were incurred this quarter in connection with the Tazapay acquisition.
USDC Circulation Enters a Plateau, but On-Chain Usage Continues to Rise
Looking at Circle's core USDC business, the quarter overall showed characteristics of "average circulation declining, end-of-quarter stabilization, and high on-chain frequency."
As of the end of Q3, USDC's market share among USD stablecoins was 27%, flat quarter-over-quarter but down 1.83% year-over-year. Q3 USDC average circulation was $73.3 billion, up 8% year-over-year but down approximately 4.2% from Q2's average of $76.5 billion. The good news is that USDC's minted and redeemed volumes in Q3 were exactly balanced at $104 billion each, helping end-of-quarter circulation edge up to $73.9 billion (flat year-over-year, up 0.8% quarter-over-quarter). This suggests that the outflow trend from the end of Q2 has stabilized, but overall scale remains in a sideways consolidation phase, still posing considerable challenges to management's unchanged "40% CAGR across cycles" guidance.
In sharp contrast to the flat circulation, USDC usage frequency continues to accelerate. USDC on-chain transaction volume reached $13.9 trillion this quarter, up 49% year-over-year; the number of active wallets holding more than $10 in USDC grew to 7.3 million, up 16% year-over-year. Transaction volume and active wallet growth significantly outpacing circulation growth indicates that the turnover efficiency of existing USDC in payments, cross-border settlement, and on-chain transactions is continuing to improve.
Distribution Structure Improves, Binance Becomes a New Channel
For a long time, high channel revenue-sharing costs (especially interest-sharing with partners like Coinbase) have been the biggest pain point weighing on Circle's valuation. In the Q3 report, distribution and transaction costs fell from $447 million in the same period last year to $409 million (down approximately 8% year-over-year).
It should be objectively noted that the year-over-year decline in absolute distribution costs was primarily because the total reserve income pool shrank 8% year-over-year — as the interest pie got smaller, the absolute amount shared proportionally with external partners naturally decreased. But beyond this passive shrinkage, Circle also made progress on two fronts: own-platform retention and channel dynamics.
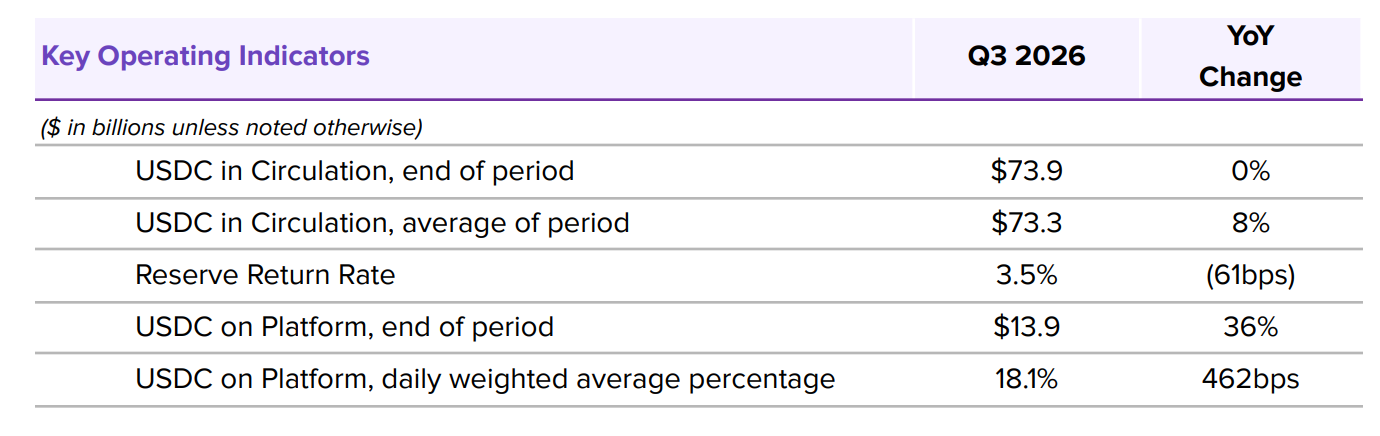
First, growth in funds held on Circle's own platform improved the platform retention ratio. The report showed that USDC held on Circle's own platform climbed to $13.9 billion at the end of Q3, up 36% year-over-year; the daily weighted average share rose 4.62 percentage points year-over-year to 18.1%. Since USDC held on Circle's own platform requires no revenue sharing with external channels, this increase helped Circle raise its net reserve margin from 37% in the same period last year to 38%.
Second, Binance made a strategic $100 million equity investment in Circle, binding a new distribution channel through equity ties. Following the renewal of its agreement with Coinbase in Q2, Circle announced this quarter that Binance had made a $100 million equity investment in Circle, with both parties simultaneously renewing and expanding their strategic partnership, focusing on promoting USDC across Binance's vast global trading platform and emerging markets.
Arc Mainnet Goes Live — Is the $182 Million Revenue Just the Beginning?
The biggest new business development for Circle this quarter was undoubtedly Arc.
On September 16, the Arc public mainnet went live. Circle called it its most important product launch since USDC, with over 100 institutions and ecosystem builders participating on day one and native USDC integration. The report also noted that during the private mainnet phase, a developer community of over 75,000 Arc House members and 10,000 Architect ambassadors had built more than 1,200 projects on Arc.
On the token side, Circle completed the full initial genesis minting of 10 billion ARC tokens in Q3, officially becoming the world's first publicly listed company to mint a native network token for a new Layer 1 blockchain. The ARC token will serve network security, utility, and governance coordination functions, driving the network's formal transition to a proof-of-stake (PoS) mechanism in 2027. The $182 million in ARC pre-sale revenue recognized this quarter also left a rather conspicuous mark for Arc in Circle's financial statements for the first time.
However, more than a month after mainnet launch, the data disclosed in the earnings report still mainly covers developers and ecosystem builders, which is not yet sufficient to prove that Arc has formed large-scale real economic activity. Future transaction volume, institutional usage, and network revenue will be the key to judging its commercial value.
Payment Network Continues to Expand
In addition to Arc, Circle's payment network CPN reached $41.3 billion in annualized total payment volume this quarter, a notable acceleration from Q1 ($8.3 billion) and Q2 ($14.7 billion).
To further strengthen payment execution capabilities, Circle has signed a definitive agreement to acquire Singapore-based B2B cross-border payment platform Tazapay (expected to close in 2027). Tazapay has over $25 billion in annualized payment volume (approximately 60% of which already involves stablecoin transactions), more than 60 banking and fintech partners, and local clearing channels covering over 100 markets. If integrated successfully, this will further enhance Circle's payment network footprint across Asia-Pacific, Latin America, and emerging markets.
After Stripping Away the "Accounting Magic," How to Assess Circle's True Quality?
Overall, Circle's Q3 earnings report clearly reflects the company's current "transition period between old and new growth drivers."
On one hand, the recognition of $182 million in ARC token pre-sale revenue made this quarter's total revenue ($865 million), RLDC Margin (52%), and adjusted EBITDA ($317 million) look extremely impressive on paper. But if you strip away this "one-time token gain" filter, USDC circulation stuck in the $73–74 billion range, reserve income down 8% year-over-year, and the sequential decline in recurring subscription and services revenue excluding ARC remain unavoidable realities that Wall Street must confront when examining its fundamentals.
On the other hand, Circle is also responding to market skepticism through concrete business actions — USDC held on its own platform exceeding 18%, Binance taking a $100 million equity stake, CPN annualized transaction volume reaching $41.3 billion, and the Tazapay acquisition closing the loop on cross-border clearing... For investors, when the "one-time accounting windfall" from ARC pre-sale revenue gradually fades over the coming quarters, whether the aforementioned payment network and public chain ecosystem can truly take over and contribute sustainable recurring non-interest income will determine the ultimate direction of Circle's valuation center in the secondary market.