






Guest Columnist: BiyaPay
How are BTC's rally, short covering, and derivatives expectations combining to drive the altcoin market? Is this just short-term capital rotation, or the beginning of a new altcoin cycle?
Bitcoin moves first, altcoins follow.
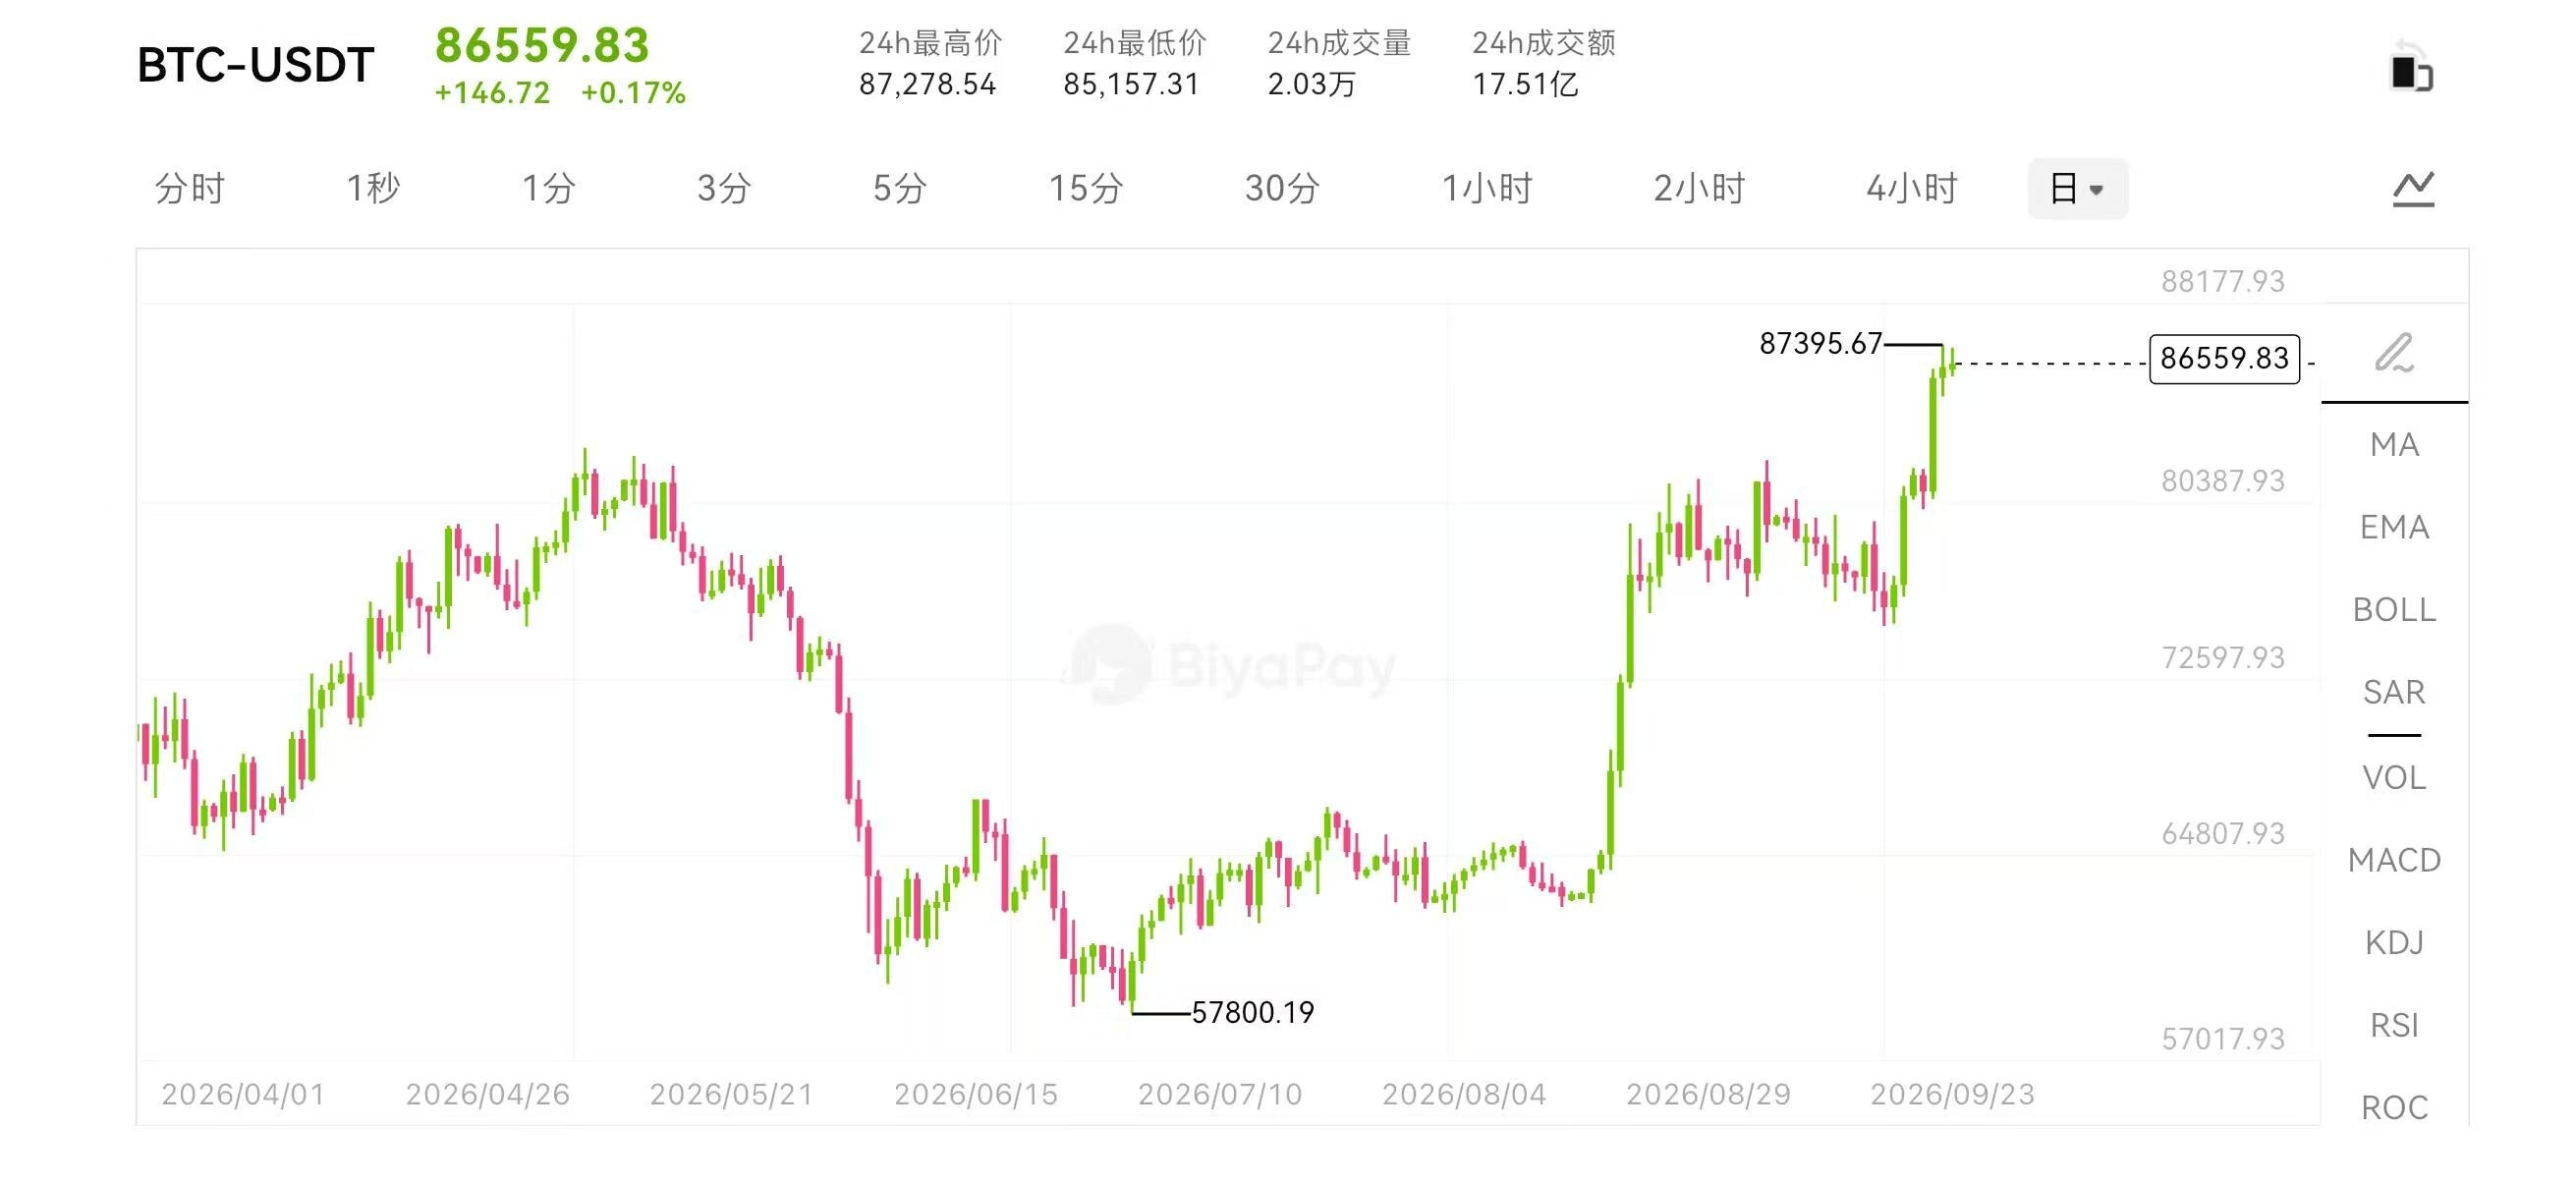
According to data from BiyaPay, a global one-stop asset allocation platform, Bitcoin briefly broke through $87,000 on September 21, hitting a new high since late January. Capital then began rotating into assets with higher beta — BCH posted notably larger gains, and UNI climbed back to around $10. By September 22, CME announced plans to launch Bitcoin Cash (BCH) and Uniswap (UNI) futures contracts on October 19, though the listing still requires regulatory review.
With these factors stacking up, BCH and UNI quickly became the market's focal point. That raises the question: why did these two tokens attract capital at the same time? Does this signal a restart of the altcoin market, or is it simply a short-term spillover driven by BTC's breakout, derivatives news, and short covering?
What Signal Is CME Sending to the Market?
What CME plans to launch are not spot products, but standard futures and Micro futures. The BCH standard contract corresponds to 250 BCH, while the Micro contract corresponds to 25; the UNI standard contract corresponds to 10,000 UNI, while the Micro contract corresponds to 1,000. CME states that these products are primarily designed for price discovery, risk management, and providing market participants with a richer set of institutional-grade trading tools.
This means what the market is really pricing in is not "how much BCH or UNI CME will buy," but rather that these two assets are entering a more regulated derivatives trading framework. Futures allow institutions to participate through hedging, directional trading, and cross-market arbitrage, but they do not automatically generate equivalent spot buying pressure.
From this perspective, CME's move is more like adding a new channel for trading and risk management to the market. Institutional derivatives in crypto have historically been concentrated in assets like BTC and ETH. Now that more high-liquidity altcoins are entering this framework, it shows that the ways institutions participate in crypto markets are still expanding.
But a boundary needs to be drawn here: a planned launch does not equal an official listing, and a futures listing does not guarantee increased spot demand. What's truly worth watching going forward is whether the contracts launch on schedule, and the trading volume, open interest, and spot market performance after listing.
BCH's sharper rally this time is also related to its own market structure. Compared to BTC, BCH has a smaller market size and thinner trading depth, so its price tends to be more elastic when major news hits. After CME announced plans for BCH futures, the market refocused on the availability of institutional trading and risk management tools for the asset — and that expectation can easily get amplified in short-term trading.
But this does not mean BCH's fundamentals have fundamentally changed in a short period. Whether this rally can translate into a sustained move still depends on real participation after the contracts officially launch, and whether the spot market can continue to absorb capital.
UNI's logic is different. UNI is the governance token of the Uniswap ecosystem, and its price is influenced not only by the broader crypto market but also by DeFi activity, on-chain liquidity, protocol development, and market expectations. CME's plan to launch UNI futures means the market gains more mature price risk management tools, and it also raises attention on UNI's institutional trading and liquidity.
However, the futures product itself will not directly change Uniswap protocol fundamentals, nor will it automatically enhance UNI's governance value. So UNI's rally this time is better understood against two overlapping factors: the catalyst from CME's product news on one hand, and the improvement in overall risk appetite following BTC's breakout on the other.
After BTC's Breakout, Capital Starts Seeking Higher Beta
If you only look at BCH and UNI, it's easy to interpret this rally as driven by a single news catalyst. In reality, BTC had already completed a notable rally before altcoins started moving.
On September 21, Bitcoin briefly broke through $87,000 intraday, hitting a new high since late January. US spot Bitcoin ETF flows also improved significantly during the same period, with net inflows reaching approximately $999 million on September 21 — one of the largest single-day net inflows since October 2025.
Institutional players also made new moves. Strategy disclosed that as of September 20, the company had purchased an additional 950 BTC, bringing its holdings to 846,000 BTC. Based on the announcement data, the purchase amount was approximately $75.7 million.
Meanwhile, BTC's rapid rally was accompanied by large-scale short liquidations. Market statistics showed that crypto short liquidations at the time approached $920 million, with BTC short liquidations exceeding $550 million. Forced short covering creates additional buying pressure, which can further accelerate the rally when the market is already strong.
This created a fairly clear transmission path: BTC rallied first, market risk appetite improved, capital began seeking higher-beta assets, and BCH and UNI happened to get a news catalyst from CME futures products — further amplifying their price reactions.
This is also why BCH and UNI's rallies this time cannot be fully attributed to sudden major changes in the two projects themselves. Macro liquidity, BTC's trajectory, market positioning, and specific news are all jointly influencing prices.
Is the Altcoin Market Back, or Is This Just a Short-Term Spillover?
At this point, it's too early to simply label this rally as a "full-scale altcoin comeback."
More precisely, what we're seeing is capital spilling over into higher-beta assets after BTC's breakout, while the news of CME launching BCH and UNI futures has further raised market attention. The combination has pushed some altcoins to significantly outperform BTC.
What's truly worth watching next is not how much more BCH and UNI can rise, but whether prices can hold after the news hype fades. If the rally is mainly driven by short-term leverage and sentiment, altcoins will typically see even larger swings once BTC weakens again.
Whether CME's contracts launch on schedule is another key observation point. The currently announced date is October 19, but it still needs to pass regulatory review. The real market impact will need to be verified after listing through trading volume, open interest, and institutional participation.
Macro liquidity also cannot be overlooked. The dollar, US Treasury yields, US spot Bitcoin ETF flows, and US equity risk appetite all affect the valuation environment for the entire crypto market. If liquidity tightens again, altcoins will typically see faster drawdowns than BTC.
When observing this kind of cross-market activity, I use BiyaPay to simultaneously track BTC, ETH, and changes in US equities, Hong Kong stocks, and fiat-related assets, then combine ETF flows, interest rates, and risk appetite to find explanations. The platform uses USDT as its core funding entry point, connecting digital assets, US and Hong Kong stocks, and fiat currency exchange through a single account. It also supports converting digital currencies like BTC and USDT into fiat currencies such as USD and HKD to bank accounts. Putting different markets into the same observation framework makes it easier to judge whether capital is continuously spreading into higher-beta assets, or whether this is just a short-term rotation after BTC's breakout.
Especially when Bitcoin, the dollar, US Treasury yields, and tech stocks are all moving at the same time, looking at any single token in isolation makes it easy to mistake macro liquidity shifts for a project's independent rally. BCH and UNI's rally this time is a typical example: there's the news catalyst from CME derivatives products, but also the combined effects of BTC's breakout, short covering, and improved overall risk appetite.
Final Thoughts
So rather than rushing to judge whether "the altcoin market is back," it's better to first observe whether capital rotation can be sustained.
If institutional trading channels like CME gradually improve, BTC remains relatively strong, and spot capital is willing to continue spreading into higher-beta assets, then the altcoin market may have a chance to evolve from a rapid sentiment spillover into a more sustained market repricing. Conversely, if BTC weakens again, macro liquidity tightens, or trading volume drops significantly after the news catalyst fades, this rally could also revert to a BTC-dominated market structure.
For now, BCH and UNI look more like two representative samples of this market spillover. What they tell the market is that after BTC's rally, capital is once again searching for higher-beta trading opportunities, and the institutional derivatives market is gradually covering more altcoins.
As for whether this is a new full-scale altcoin cycle, it will take time and capital flows to verify.