






Core Thesis: According to Morgan Stanley's research report, the top five cloud vendors could reach $1.4 trillion in capital expenditures by 2028, with available computing capacity expanding to 120GW. However, cost per GW is being driven up by factors such as memory and electricity. META is listed as a top pick, and whether it can translate its massive computing power into revenue from ads, APIs, and more is key to validating returns.
Key Elements:
a. The 2028 capital expenditure forecast for the top five cloud vendors has been raised to $1.4 trillion (from $1.2 trillion in 2027), with global AI infrastructure investment expected to approach $3 trillion.
b. Available computing capacity is projected to increase from 30GW in 2025 to 120GW in 2028, with META rising to 21GW and Amazon reaching 35GW.
c. Per-GW construction costs are rising due to higher memory, electricity, and data center shell-external costs. For instance, GB200 costs around $35 billion, and Vera Rubin about $49 billion.
d. META is listed as a top pick in the AI internet space, with its AI monetization paths (e.g., API, advertising upgrades, subscriptions) expected to contribute approximately $10 to 2028 EPS.
e. Under META's API business model assumptions, every 100MW of GB300 capacity could generate around $8.59 billion in revenue and $1.91 in EPS incremental gains, but it relies on high utilization rates.
f. Amazon and Google also benefit from the capex cycle, with AWS revenue expected to grow 40% and 36% in 2027 and 2028 respectively, while Google adds the most capacity.
g. Capex deployment faces triple constraints: supply (chips, approvals), regulation (energy policy), and demand (customer willingness to pay). Revenue validation remains the core challenge.
TL;DR
• Morgan Stanley's research estimates that the top five hyperscale cloud vendors could spend $1.4 trillion in capex by 2028.
• Per-GW construction costs are driven up by memory, electricity, and construction, with computing capacity potentially expanding from 30GW to 120GW.
• META is listed as a top AI internet pick, with a $775 price target dependent on the monetization of APIs, ads, and subscriptions.
In a sell-side research report, Morgan Stanley raised its capex estimates for major hyperscale cloud vendors, projecting total capital expenditures of $1.2 trillion and $1.4 trillion for 2027 and 2028 respectively, and continued to rank META as a top AI internet pick with a maintained price target of $775.
These figures fall under the report's model estimates and do not equate to official company guidance. Public versions of Morgan Stanley materials have already noted that global AI-related infrastructure investment could approach $3 trillion by 2028, with data center capex at about $2.9 trillion. The $1.4 trillion figure for the top five platforms is more derived from sell-side breakdown estimates of major cloud and internet platforms.
The most newsworthy change in this report is the continued upward revision of AI infrastructure spending. By 2028, the available computing capacity of major platforms in the model approaches 120GW, roughly four times the 30GW in 2025. Per-GW construction costs have also been raised, as next-generation platforms like GB200, GB300, and Vera Rubin require more memory, electricity, racks, and engineering input.
For investors, the question has shifted from "Will AI giants spend money?" to "How quickly will this spending turn into revenue?" META gets top billing because it faces higher AI capex pressure while also having more direct monetization channels, including advertising, consumer applications, model APIs, and subscription tools.
$1.4 Trillion in Spending Bets on 120GW of Computing Power
The report raised capex expectations for the top five hyperscale cloud vendors by 9% and 10% for 2027 and 2028 respectively, to $1.2 trillion and $1.4 trillion. This scope covers AI infrastructure spending from Amazon, Google, Microsoft, META, and SPCX-related entities.
Capacity expansion is one of the main drivers behind the upward revision. In this model, the available computing capacity of major platforms rises from about 30GW in 2025 to nearly 120GW in 2028. By 2028, Amazon's total is estimated at around 35GW, Google adds the most capacity in 2027 and 2028, while META climbs from about 3.5GW at the end of 2025 to 14GW in 2027 and 21GW in 2028.
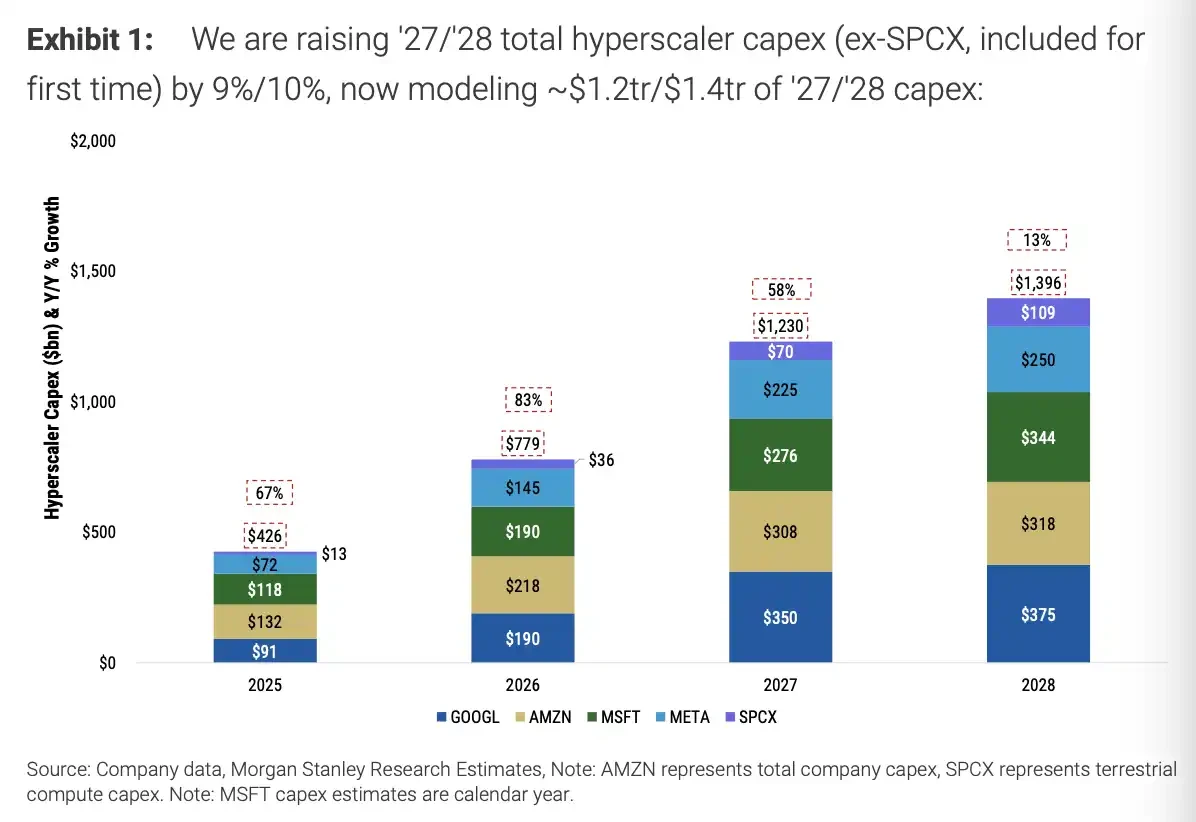
Capex forecasts for the top five hyperscale cloud vendors: a total of $1.4 trillion in 2028, up 9% and 10% from prior estimates for 2027 and 2028.
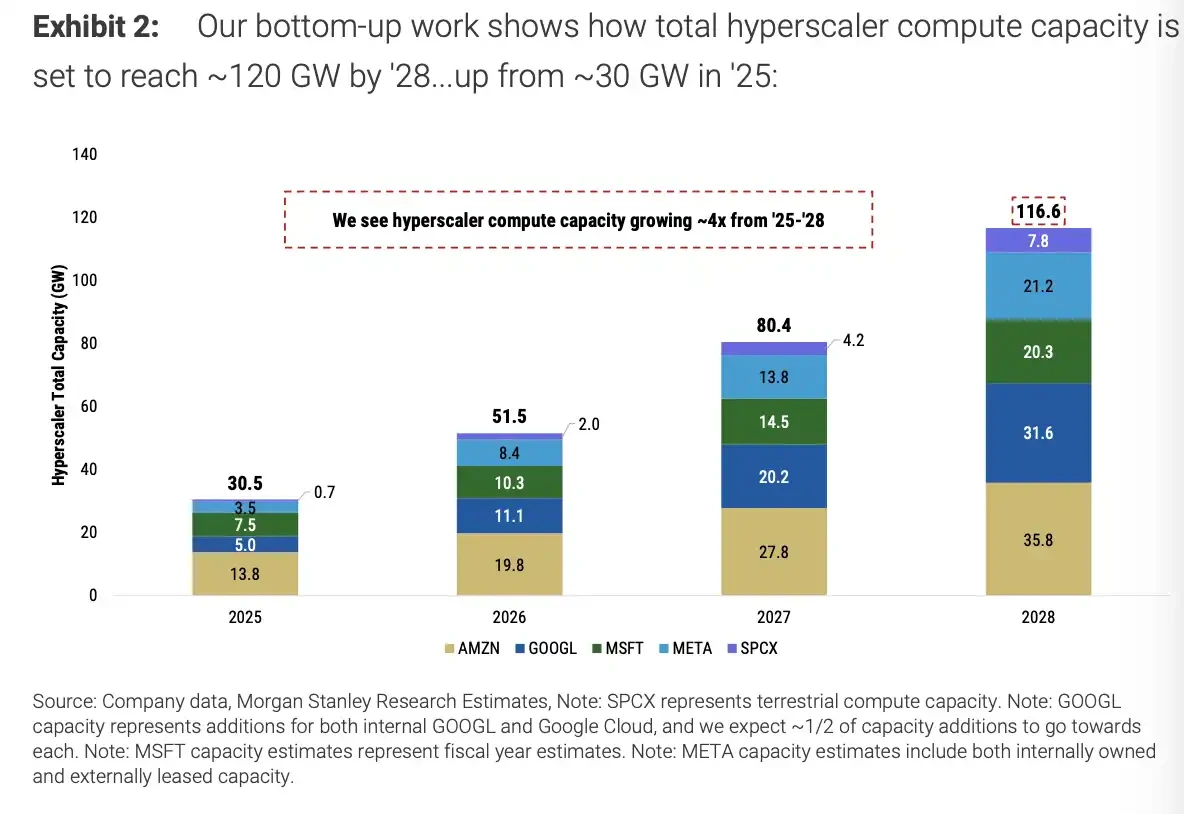
Available computing capacity rises from about 30GW in 2025 to nearly 120GW in 2028, with META reaching 21GW and Amazon totaling about 35GW.
META's capex estimates need to preserve measurement differences. In the report's model, META's capex for 2027 and 2028 is raised to $225 billion and $250 billion respectively. Some publicly reported secondary sources citing the Morgan Stanley estimate put META's total for 2027-2028 at around $380 billion, which may involve different scopes such as total capex, AI infrastructure, gross amounts, or off-balance-sheet financing.
Such differences don't change the main narrative: AI data center spending continues to weigh on free cash flow, depreciation, and short-term EPS, and will determine whether future cloud, advertising, search, API, and enterprise tool revenue materializes. Whoever can turn more computing power into chargeable products will have an easier time justifying today's capex.
Per GW Is Getting More Expensive, Memory and Electricity Raise the Bar
The upward revision in spending isn't just about "building more data centers" but also about "per GW costing more."
In the report's bottom-up cost model, the per-GW construction cost for GB200 is about $35 billion, up 16% from prior assumptions. GB300 is around $39 billion, up 19%. Vera Rubin is about $49 billion, up 20%. Google's TPU v7 is about $27 billion, and Amazon's Trainium3 is around $21 billion.
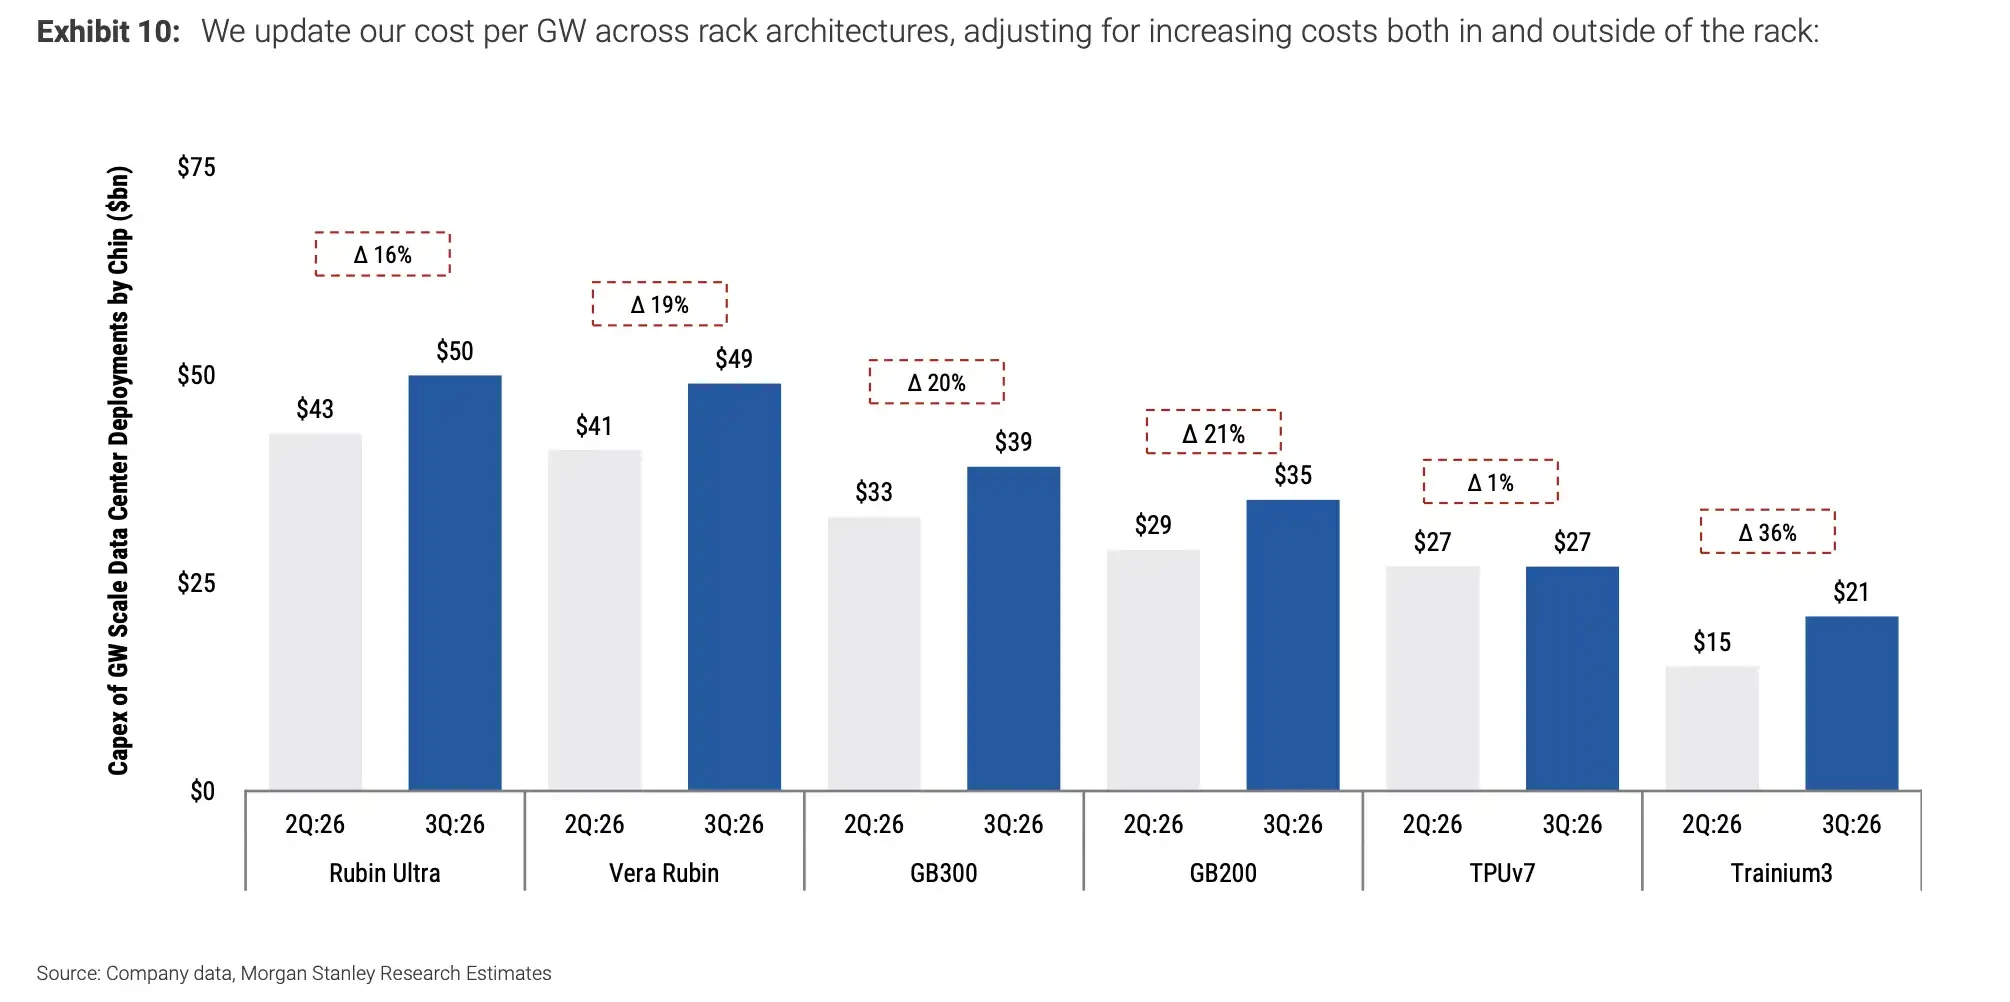
Updated GPU and ASIC GW-scale data center deployment costs: GB200 at about $35 billion, GB300 at about $39 billion, and Vera Rubin at about $49 billion.
Cost pressures come from two main areas. The memory share in high-end AI systems continues to rise, and data center shell-external costs such as electricity, land, cooling, power distribution, and construction are also increasing. The report assumes these costs rise from about $10 million/MW to about $11 million to $19 million/MW.
This is also why the spending curve for AI giants is unlikely to decline in the short term. While improved chip supply can ease some pressure, electricity access, rack systems, construction, skilled labor, and local approvals will still lengthen project timelines. Some projects could take up to three years to complete, and the larger the capex, the faster revenue needs to prove returns.
META's Focus Shifts to How AI Generates Revenue
META is listed as a top pick largely because its AI revenue options are more concentrated than most internet companies.
The report breaks down META's potential upside into areas like Meta AI search, new cloud services, API revenue, subscription tools, and advertising upgrades, collectively contributing about $10 to 2028 EPS. In the base case, META's 2028 EPS is $33.41. If some options materialize, EPS could see further upside.
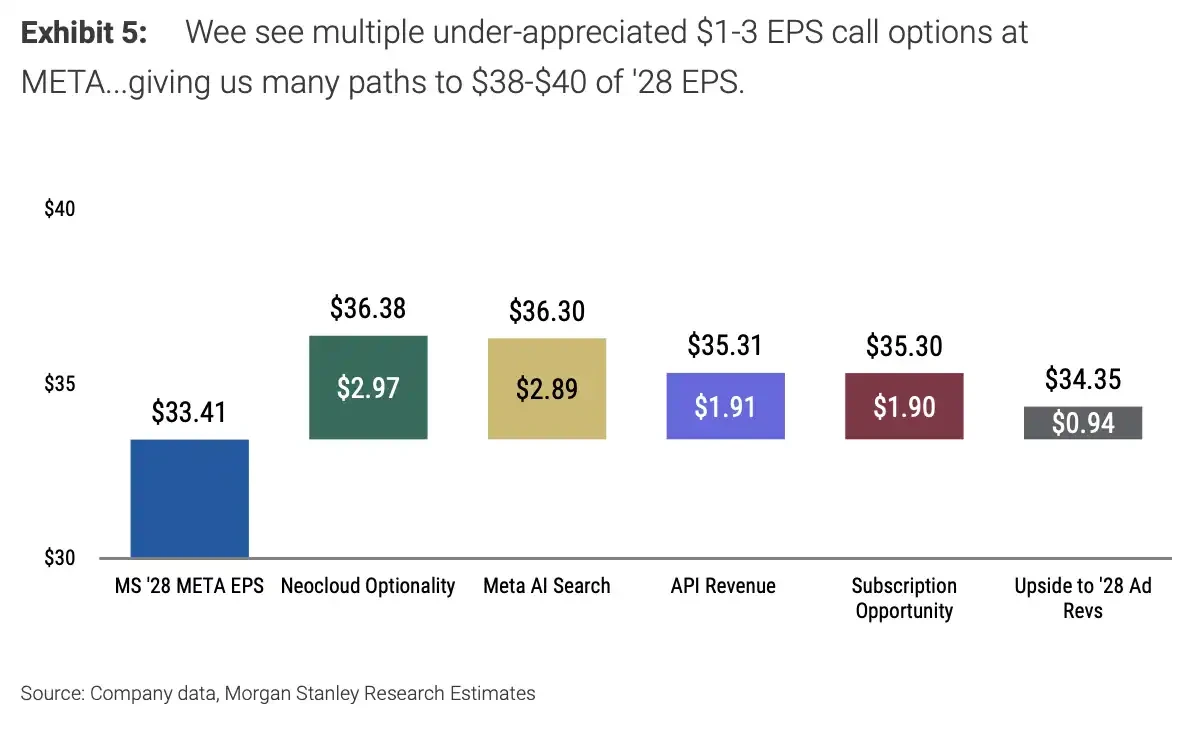
Cumulative contribution of META's five AI upside options to 2028 EPS: base EPS of $33.41, with total upside of about $10.
This estimate doesn't fully align with some publicly reported secondary sources mentioning "four products or catalysts" or "2028 EPS upside of $1 to $3," and is better viewed as a scenario analysis from this report. What actually lands on the financial statements depends on product adoption, pricing power, and compute utilization rates.
APIs are the most straightforward entry point. On July 9, Meta announced the public preview of the Meta Model API. Third-party sources like Artificial Analysis indicate that the Muse Spark 1.1 API input and output prices are $1.25 and $4.25 per million tokens respectively, lower than some frontier competitors.
The report's model further assumes that every 100MW of GB300 capacity used for APIs, corresponding to about 53,300 GPUs at 75% utilization, could generate roughly $8.59 billion in revenue, $640 million in incremental EBIT, and contribute about $1.91 to 2028 EPS. This estimate depends on high utilization and sustained demand; low prices alone help attract customers but don't guarantee profitability.
Subscription tools are also a potential entry point. The model assumes that 25% of META's 15 million advertisers pay about $200 monthly for tools like business agents and coding assistants, contributing about $8 billion in revenue and roughly $2 to 2028 EPS. Whether advertisers continue to pay ultimately depends on whether these tools deliver higher conversion rates, lower production costs, or superior automation.
Amazon and Google Benefit, But Revenue Validation Must Follow
Amazon and Google are also key players in this capex upgrade cycle, though they serve more as background reference points in this narrative.
For Amazon, the report raises its AWS revenue growth outlook, projecting 40% and 36% growth in 2027 and 2028 respectively. It also estimates that AWS's backlog increased by about $110 billion sequentially in Q2 to approximately $475 billion. Since Amazon has not yet released corresponding official Q2 results, this backlog figure should be viewed as a sell-side forecast. Official filings have confirmed that AWS sales grew 28% year-over-year in Q1 2026, OpenAI added a $100 billion multi-year commitment, and cash capex continues to rise.
Google's strength lies in its full-stack capabilities with the Gemini model, TPU, and cloud business. The report's model shows Google adding the most capacity among major platforms in 2027 and 2028. A short-term pressure is that compute resources may still constrain product scaling, especially when search, cloud services, and model APIs compete for the same computing power.
These threads point to the same real-world issue: AI spending has entered the trillion-dollar territory, and the market will increasingly ask directly, "How much revenue does each dollar of capex generate?" Cloud services, AI search, APIs, advertising tools, and enterprise subscriptions will all become entry points for validating returns.
Massive Spending Must Navigate Electricity, Approvals, and Real Demand
This round of capex upgrades has clear boundaries.
The first constraint is supply. Chips, HBM memory, rack systems, electricity access, and skilled labor all affect construction speed. From planning to operation, AI data centers must pass through local approvals, grid upgrades, and construction cycles, and cannot linearly follow model assumptions.
The second constraint is politics and regulation. Large data centers' demands for electricity, water, and land may spark local resistance. Around the 2026 U.S. midterm elections and the November 2028 presidential election, energy policies and local approval timelines could also shift.
The third constraint is demand. META's APIs, subscriptions, and advertising upgrades remain upside scenarios, with revenue realization requiring real customer payments and sustained usage. Lower prices than competitors help attract customers, but long-term profitability depends on usage volume, gross margins, and tool ROI.
The $1.4 trillion in capex paints a picture of a high-cost growth curve. The giants are pre-emptively locking in AI computing power, and the market will continue to press for when this computing power translates into revenue and profit. META's $775 price target rests on the gradual realization of AI monetization, with the hardest step being turning the model's EPS upside into real cash flow on financial statements.