






Special Column Author: Tiger Research
Core Thesis: In jurisdictions where regulation is not yet mature, financial institutions should proactively choose to enter overseas markets or adopt on-chain native platforms to accumulate operational experience early, rather than passively waiting for domestic legislation.
Key Elements:
a. As of the first half of 2026, the RWA tokenization market has reached a size of $25 billion to $36 billion, with significant efficiency gains, but many regions lack frameworks that grant distributed ledger records legal effect.
b. Financial institutions face three strategic choices: waiting for legislation (low risk but potential to miss opportunities), using regulatory sandboxes (limited experimentation), or entering mature overseas markets (allows accumulation of first-mover advantages).
c. Cross-border RWA business requires preparation in six areas: establishing an overseas base, license compliance, asset definition, investor scope, settlement currency and payment process, and operational arrangements (e.g., custody, on-chain governance).
d. Hong Kong, Singapore, and the U.S. are major pioneer markets: Hong Kong offers a complete regulatory chain and policy subsidies; Singapore has strict but clear regulations; the U.S. enables efficient issuance through platforms like Securitize.
e. On-chain native paths (e.g., Ondo, Plume) allow institutions to bypass jurisdictions and quickly access markets via compliant platforms, but structural design is more complex and relies on platform differences.
f. Using Hong Kong as an example, a mid-sized brokerage can complete the entire process from evaluation to issuance within 6 to 12 months by leveraging existing subsidiaries, choosing the DigiFT platform, and utilizing the Regulation S exemption.
Key Takeaways
This article is from Tiger Research. The RWA market is growing rapidly, but many jurisdictions still lack the supporting regulatory framework. Financial institutions in these regions must make a strategic trade-off among three options: waiting for domestic legislation, using regulatory sandboxes, or entering overseas markets directly.
Cross-border RWA business demands a high level of precision. Before entry, institutions must prepare thoroughly across six core areas, covering jurisdiction selection, licenses, asset definition, investor scope, and design of settlement and operational arrangements.
The core goal is to accumulate real operational experience by choosing a path that fits their specific situation. The two main paths are: directly entering jurisdictions with mature regulations, and adopting the technical path of on-chain native platforms.
1. Wait, Experiment, or Go Abroad
As of the first half of 2026, the market size for tokenization of real-world assets (RWA) has grown to approximately $25 billion to $36 billion. It shows clear efficiency improvements, including automated interest payments and redemptions, shorter settlement cycles, and broader customer reach, attracting continued attention from institutional investors.
However, financial institutions still face practical obstacles in regulatory vacuums. While tokenization is not explicitly prohibited, the legal framework needed to give distributed ledger records legal effect has not yet been formed, thus lacking adequate protection for investor rights. In response, financial institutions choose among three broad directions: waiting for domestic legislation helps with risk management but carries a significant risk of missing early market positions; using regulatory sandboxes allows limited experimentation but is restricted to areas like fragmented investments and cannot expand to standardized securities issuance; entering overseas markets first means issuing digital bonds in jurisdictions with established regulations, building a track record locally, and securing an early competitive position through experience gained abroad.
The RWA market is inherently global, so building operational capabilities under different regulatory environments is crucial. There are indeed practical constraints to overseas expansion, but it is precisely for financial institutions whose home regulations are still blank that there is more reason to gain first-hand experience in overseas markets before their peers.
2. Tokenization Is Not Magic
Cross-border RWA business is not the result of a series of isolated decisions. The choices are interconnected, with the outcome of each step determining the options for the next. Tokenization is not magic; it's the process of moving existing financial instruments onto a new type of infrastructure, and this process demands a higher, not lower, level of precision than traditional issuance.
Before deciding to enter, financial institutions should honestly assess their readiness against the following six requirements.
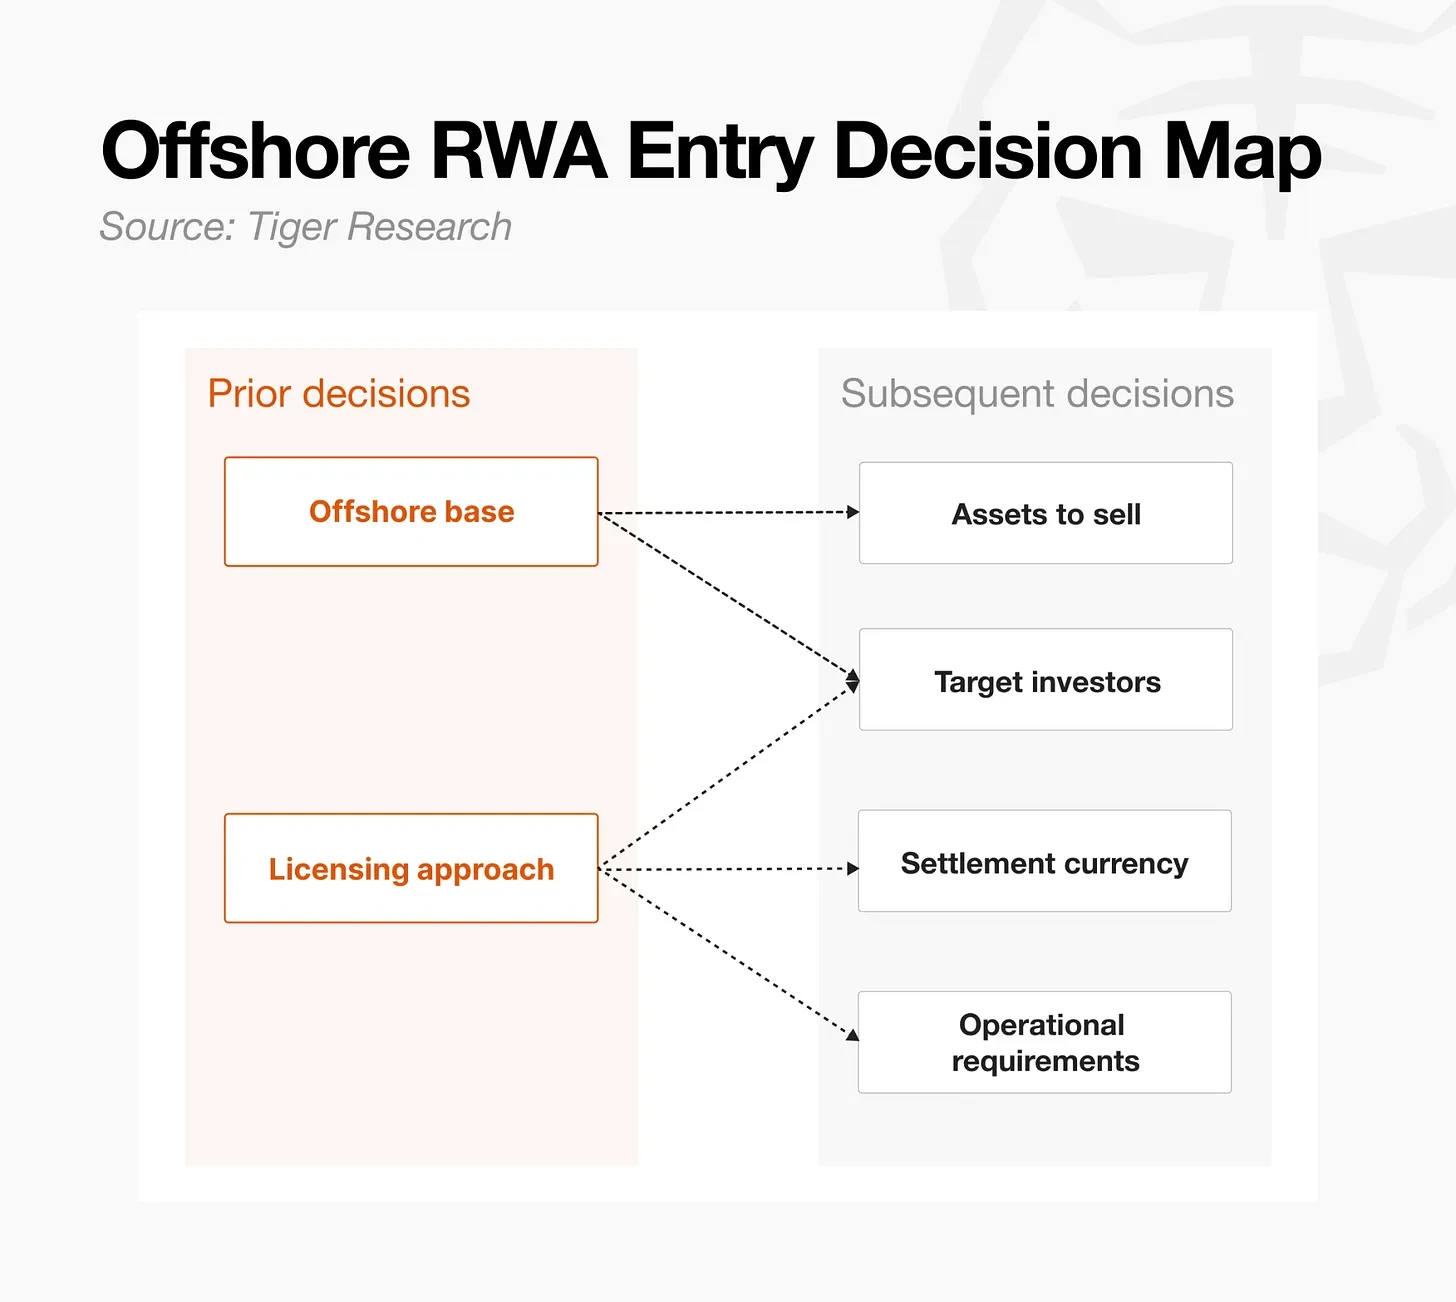
First, establishing an overseas base. Institutions must determine how to utilize key jurisdictions like Hong Kong, Singapore, or the U.S., and whether the path involves existing entities, new entities, or cooperation with local institutions. New entities offer more control but require significant resources; cooperation offers faster entry but limits the depth to which an institution can internalize core capabilities.
Second, licenses. Institutions must meet the licensing requirements of the intended sales jurisdiction. The choice is typically between obtaining a license directly (time-consuming and costly) or piggybacking on an existing platform's license (faster, but requires structuring the issuance according to that platform's specifications).
Third, asset definition. Choosing which asset to tokenize directly determines the height of the entry barrier. Standardized securities like bonds have mature structures and are relatively easy to bring to market; non-standard assets like real estate or trade receivables require significantly more time for legal review and structural design.
Fourth, defining the target investor. A typical approach is to cover all jurisdictions except the U.S. Selling only to non-U.S. investors can rely on the offshore exemption under Regulation S; once U.S. investors are included, additional requirements like Regulation D are triggered, significantly increasing structural complexity. Additionally, many STO and RWA platforms restrict sales to accredited or institutional investors, so the sales strategy must be determined in sync with the investor scope.
Fifth, settlement currency and payment process. Institutions must decide whether to accept settlement in local currency, USD, stablecoins, or wholesale CBDC. This is not just a currency choice but a key variable that determines investor accessibility, custody structure, and ultimately revenue. For example, accepting stablecoins introduces exchange needs and potential additional costs.
Sixth, other operational requirements. Depending on the structure, there are other considerations including blockchain selection, custody, on-chain operations, and post-issuance governance. Specifically, institutions must confirm who controls operations like interest payments and redemptions, register management, and the ability to force-transfer or freeze tokens in case of events. These correspond to the operational requirements of traditional financial instruments.
Tokenization is not magic. The work is not done once the structure is designed; the business truly begins when the securities are sold and investors are in place.
3. Where to Operate
Jurisdiction selection is a strategic decision that requires balancing regulatory fit and operational efficiency.
For institutions that already have an overseas presence, the most efficient starting point is to evaluate their existing jurisdictions. If the primary goal of an overseas tokenization strategy is to accumulate first-hand experience early, starting from scratch in a completely new jurisdiction means a very high time and capital barrier.
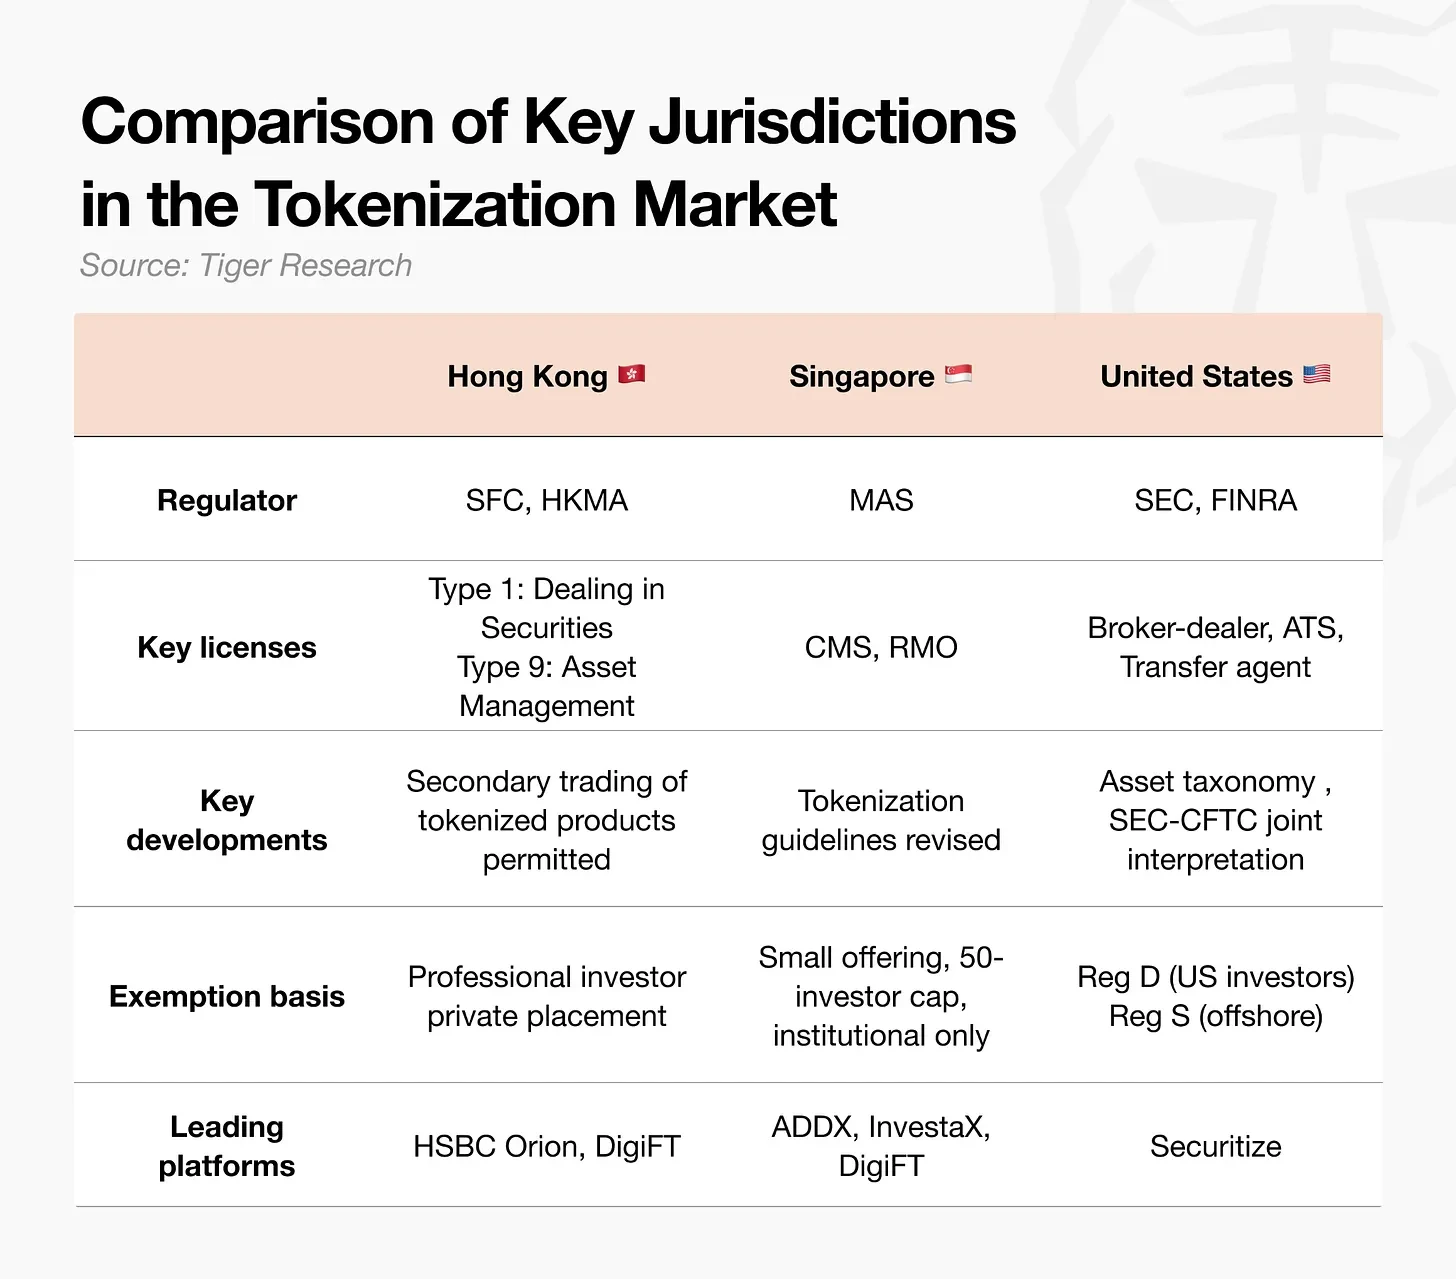
Hong Kong: Regulatory Completeness and Enforceability
Hong Kong is the most advanced pioneer market. Security tokens are regulated under the existing Securities and Futures Ordinance. A circular issued by the Securities and Futures Commission (SFC) in April 2026 allows licensed virtual asset exchanges to conduct secondary trading, completing the full chain from issuance to circulation. Infrastructure like HSBC Orion is already live, and policy support is ample, including subsidies from the Hong Kong Monetary Authority (HKMA) for issuance costs. Institutions need to be aware that if legislation introducing new licenses for virtual asset dealers and custodians proceeds as planned in 2026, they must pay attention to compliance with transitional provisions.
Singapore: Precise Framework and Regulatory Clarity
Singapore strictly applies the Securities and Futures Act under the principle of "same activity, same risk, same regulation." The Monetary Authority of Singapore (MAS) revised its tokenization guidelines in December 2025, providing clearer guidance. The Variable Capital Company (VCC) structure facilitates asset segregation, making it particularly suitable for fund structures. However, even for services to overseas clients, Singapore imposes strict licensing requirements, leading to a high entry barrier.
United States: Regulatory Clarity and Efficient Listing Path
A joint interpretation by the SEC and CFTC in 2026 clarified the asset classification framework. The cost of applying for a license directly as an issuer remains high, but efficient issuance is possible through vertically integrated platforms like Securitize: using the Regulation D exemption for accredited U.S. investors and the Regulation S exemption for overseas investors. BlackRock's BUIDL fund is the most representative case of this path.
Each of these jurisdictions has mature platforms that can accelerate local market entry. These platforms are licensed operators offering a suite of services, including regulatory coordination, capital raising access through in-platform investor networks, and operational infrastructure covering the full lifecycle from issuance to settlement. When evaluating entry into a specific jurisdiction, it is strategically more efficient to directly engage with leading local platforms to test business viability than to review extensive regulatory documents first.
4. Bypassing Jurisdictions
The previous section discussed the direct path: establishing a legal and physical presence and obtaining necessary licenses within a specific jurisdiction. This section discusses a fundamentally different approach: the on-chain native path, which designs issuance and circulation around the on-chain environment from the outset.
Instead of investing the time and capital required to set up a physical base, this path involves partnering with or borrowing the structural logic of on-chain platforms that have built-in compliance capabilities, thereby lowering the entry barrier through such infrastructure. The territorial path from the previous section answers "where to operate," while the on-chain native path answers "how to structure the transaction."
Representative examples are as follows. Ondo Global tokenizes U.S. securities through a bankruptcy-remote Special Purpose Vehicle (SPV) established in the British Virgin Islands, minimizing friction with U.S. securities regulations by using the offshore exemption under Regulation S. Ondo also operates its own secondary market, Ondo Global Markets, which directly handles trading of the issued tokens. Plume Nest operates a regulated on-chain vault via its Bermudan subsidiary, KDAB (Kimber Digital Assets Bermuda), which holds a Class M DABA license from the Bermuda Monetary Authority. Access to the Plume Nest platform is restricted to investors who have passed KYB and KYC checks. Additionally, an affiliated company is registered as a transfer agent with the U.S. SEC, providing a second layer of assurance for ownership register management and distribution. Due to the platform's decentralized design, tokenization outside this regulated structure is also possible, but this path is not suitable for regulated financial institutions.
The on-chain native strategy is substantially similar to territorial tokenization in practice, but differs significantly in execution. Its primary advantage lies in speed of entry and breadth of coverage: institutions are no longer confined to a specific base but can reach the market faster using proven infrastructure. Another advantage becomes prominent when compared to territorial platforms: the closed ecosystems of territorial platforms may restrict secondary market liquidity, while on-chain native platforms designed for scalability can organically connect with DeFi liquidity pools.
However, the complexity of structural design is a risk that requires careful consideration. The open nature of these platforms allows for a wider range of products but lacks the mature regulatory guidance that exists for territorial paths in core structural decisions like issuance design. The structural differences of these platforms vary by platform rather than by jurisdiction, potentially creating an operational burden for traditional financial institutions. Therefore, assessing whether local counterparts to these platforms exist in the target region is a necessary preparatory step.
5. Don't Wait for Regulation; the Market Won't Wait
Large financial institutions in the U.S. are already leading the market, either building their own platforms or directly accumulating experience on top of Canton, Solana, and Ethereum. For financial institutions in regions still facing regulatory gaps, launching an overseas RWA business means redesigning the entire value chain locally, from establishing a base to issuance and distribution, with a preparation period typically ranging from six months to over a year.
The following hypothetical case illustrates the process: A mid-sized brokerage, "Company A," already has a presence in Hong Kong. It plans to tokenize short-term investment-grade bonds and sell them to overseas institutional investors.
Step 1: Assess Existing Base and License Status. Company A uses its existing entity (its Hong Kong subsidiary) to avoid the time and cost of setting up a new one. Whether its existing license covers tokenization activities is a separate issue. Local legal counsel assesses the scope of the existing authorization. If necessary, Company A makes a preliminary inquiry to the regulator (in this case, the Hong Kong SFC) to confirm whether a variation of license conditions or additional filings are required.
Step 2: Choose Platform and Infrastructure. To shorten the time required for self-applying for a license, Company A considers conducting business through a mature platform like DigiFT. Supplier due diligence covers the platform's license validity, supported asset types, custody partners, and investor restrictions. During the contracting phase, legal review covers the issuance structure designed to fit the platform's specifications, allocation of responsibilities, and applicable law.
Step 3: Compliance and Product Design. This phase finalizes the product structure of the bonds to be tokenized, including the underlying asset, investor rights, and applicable law. The standard practice is to use the Regulation S exemption to sell to overseas institutional investors outside the U.S. Legal opinions regarding compliance with local securities laws are obtained for each target jurisdiction. Company A must also ensure that its logic for excluding domestic residents is legally sound under securities law before proceeding to the drafting and approval of issuance documents.
Step 4: Design Custody Structure and On-Chain Operations. Company A establishes a dual custody arrangement, with a global custodian bank holding the underlying assets and specialized infrastructure handling the on-chain tokens. Relevant legal opinions are obtained from external counsel. Operational details are also finalized, including interest payment schedules, settlement currency (USD or stablecoins), and redemption mechanisms.
Step 5: Issuance, Execution, and Verification. Company A carries out the actual issuance and sale according to the finalized structure. It then confirms that operational processes like interest payments and redemptions function as designed. The structural design is just the starting point; the business is completed only when investors are in place and the sale is finalized.
This overseas tokenization strategy is not limited to the direct path of "establishing a base in a specific jurisdiction." Paths like the on-chain native approach, which can more flexibly bypass jurisdictional boundaries, mean the space of viable options is effectively open. Legal review will be the most time-consuming and costly hurdle in any scenario. However, waiting for a complete regulatory framework is not the only answer. The ability to quickly outline a feasible path and accumulate experience through execution is more critical than any other factor, for this reason: the essence of a tokenization business lies not in the technical design, but in the successful completion of the entire sales process.
No one can predict when regulation will ultimately arrive, and the market will not wait. The time to act is now.