






Special Columnist: MSX Research Institute
Core Thesis: Micron Technology's upcoming earnings report is more than just a quarterly performance check; it's a stress test for the bull case logic of AI memory. The core tension lies in the fact that market expectations have been pushed to extremely high levels. Micron must prove that the supply-demand gap is far from over and that it can continuously raise guidance. Failure to do so could trigger significant stock price volatility and ripple across the entire supply chain.
Key Factors to Watch:
a. Massive Gap Between Market Expectations and Company Guidance: The market's consensus estimate for Micron's third-quarter revenue has already reached $35.5 billion, higher than the company's previous guidance of $33.5 billion. This requires the company to not only beat expectations but also surpass an already highly optimistic market consensus.
b. Sustainability of HBM Supply-Demand Dynamics Takes Center Stage: During the conference call, Micron needs to clarify its HBM4 yield progress, order book visibility for 2027 (including customer lock-ins), and the depth of its partnership with clients like Nvidia. It must prove that the current boom is structural growth, not a short-term product cycle.
c. Is the Ultra-High Gross Margin (Approx. 81% Q3 Guidance) the New Normal?: The market will focus on management's description of the gross margin trajectory. If the outlook is conservative, the logic supporting high valuations could weaken, potentially triggering a "Sell the News" event.
d. When Will New Production Capacity Close the Supply-Demand Gap?: The market is concerned about the pace at which new capacity comes online. If supply release outpaces AI demand growth, the memory industry could return to price competition. Micron needs to prove that demand growth still outpaces supply.
e. Options-Implied Volatility Hits 13%: The market has already priced in a double-digit move in the stock price following the earnings report, reflecting high divergence among investors trading the memory theme and the risk of crowded trades.
On June 23rd, from Korean stocks to US equities, global tech assets experienced a sharp sentiment cool-down.
It started during the Asian session, with the KOSPI index falling nearly 10% in a single day. Samsung Electronics and SK Hynix both dropped over 12%, triggering a market-wide trading halt. This selling pressure quickly spread to US markets in the evening, hitting AI and memory stocks—the best-performing sectors over the past year—hardest, making them the epicenter of this global tech correction.
Peculiarly, this intense market turbulence coincided with Micron Technology's scheduled release of its fiscal Q3 2026 earnings after the close on June 24th, making the timing quite delicate.
On one hand, global AI memory stocks are undergoing a collective pullback, prompting a market re-evaluation of high valuations and crowded trades. On the other, Micron is about to deliver a report card that carries heavy expectations. The convergence of these factors elevates the significance of this earnings report beyond just a single company's quarterly results; it serves as a concentrated stress test for the entire memory investment thesis.
After all, several core narratives driving the sustained rally in global memory stocks—explosive HBM demand, DRAM and NAND price increases, persistent supply tightness, and rapidly expanding gross margins—all require renewed confidence. This makes the question more direct: With stock prices and market expectations already pushed to lofty heights, can Micron still deliver answers that exceed imagination?
In other words, an "in-line earnings report" may no longer be sufficient. The market is truly waiting to see if Micron can once again raise its guidance and prove that the supply-demand gap in AI memory is far from closing.
I. Why is This Micron Earnings Report So Important?
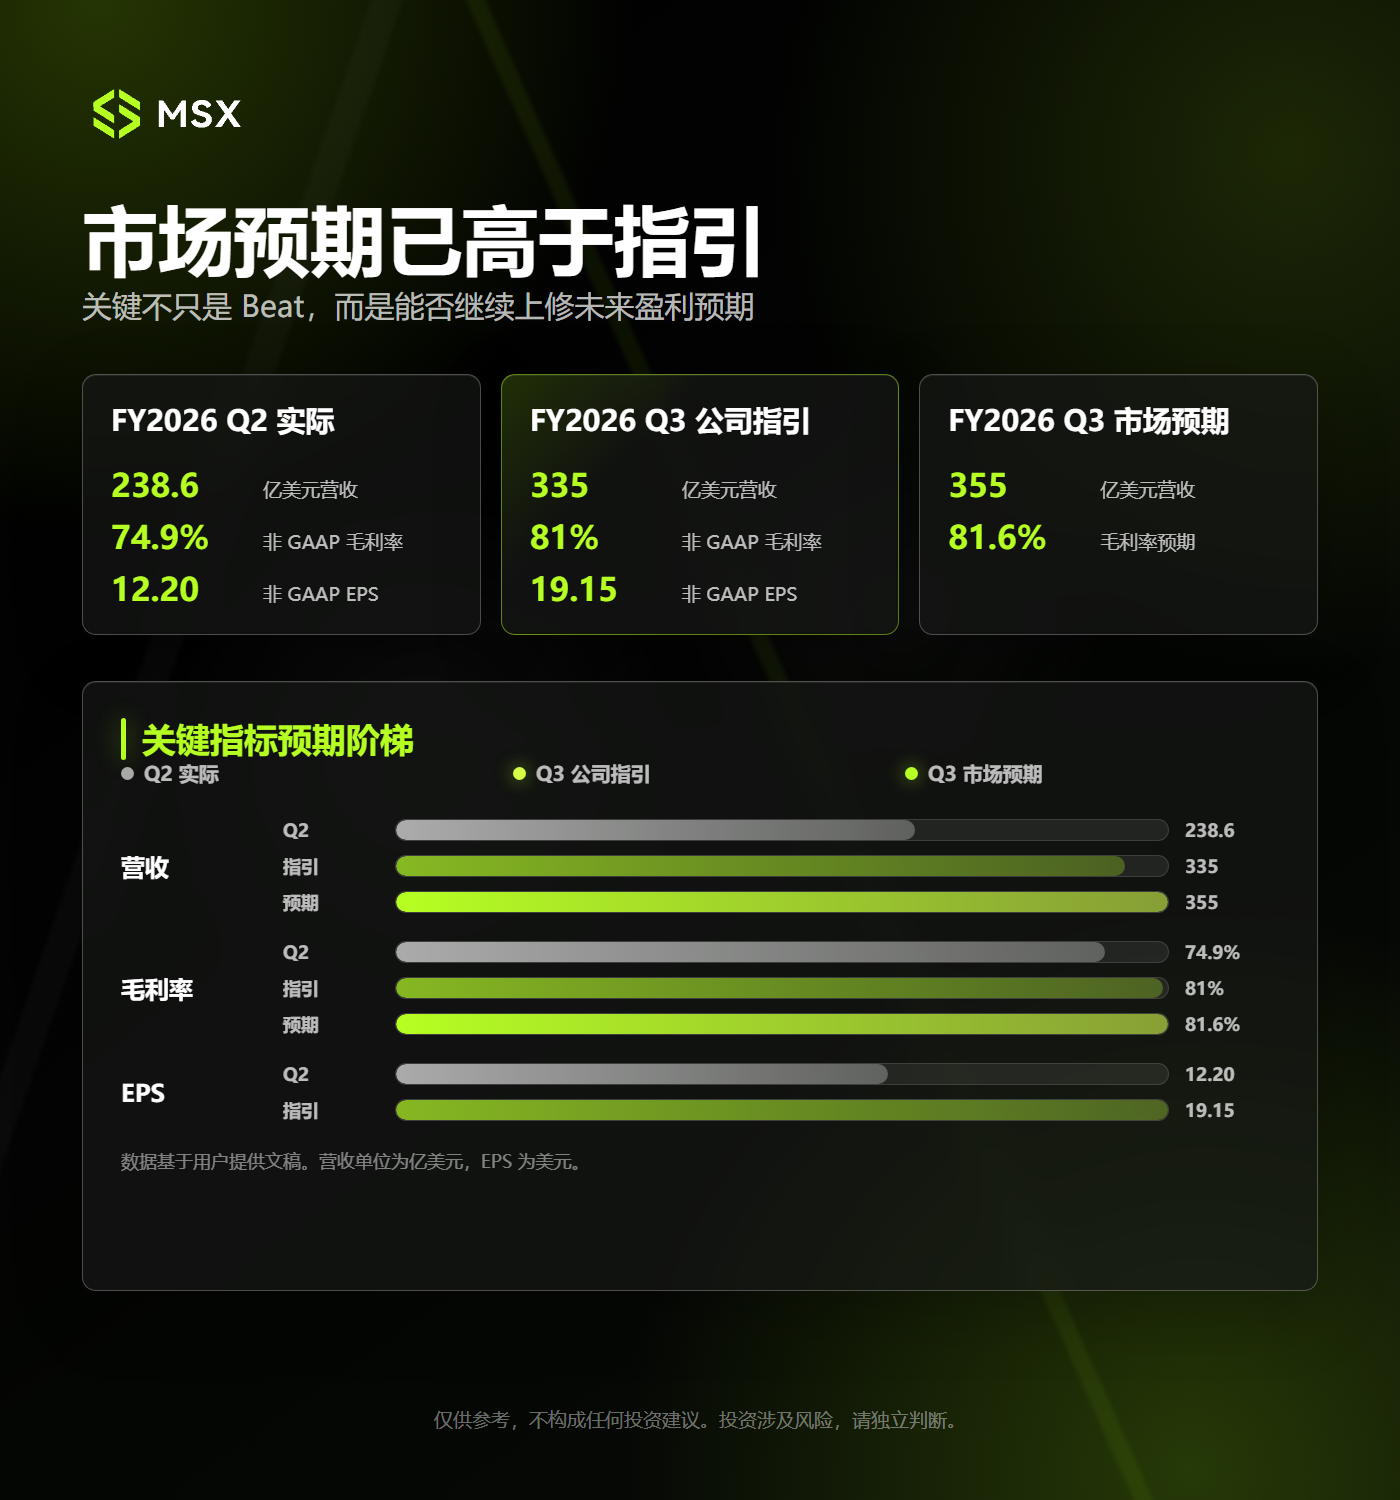
Based on last quarter's data, describing Micron's fundamentals as merely "beating expectations" feels inadequate. In fiscal Q2 2026, Micron reported revenue of $23.86 billion, nearly tripling year-over-year. Non-GAAP gross margin rose to 74.9%, and non-GAAP EPS reached $12.20, both setting company records.
More importantly, Micron's Q3 guidance was aggressively optimistic: revenue guided at $33.5 billion, non-GAAP gross margin around 81%, and non-GAAP EPS of $19.15.
However, the capital market's appetite has grown even faster than the company's guidance. Current market consensus for Micron's Q3 revenue has already climbed to approximately $35.5 billion, above the upper end of the company's prior guidance range. Gross margin expectations are around 81.6%, indicating the market has already priced in another earnings beat.
This creates the biggest contradiction for this earnings report: Micron's performance must not only exceed the company's own guidance but also surpass an already very optimistic market consensus.
Therefore, it's not just about whether revenue and EPS "beat." It's about whether the market is willing to further revise up its earnings forecasts for the coming quarters after the report. Simply put, a "decent" report might not be enough. But if the report is strong enough to justify raising guidance again, then yesterday's sell-off could turn out to be a pre-earnings shakeout.
For a high-expectation stock that has already rallied significantly, the most dangerous situation is often not terrible results, but results that, while good, aren't good enough to support even higher valuations.
This is precisely the pricing environment Micron currently faces.
II. Three Key Questions for Tonight's Memory Bull Market Sustainability
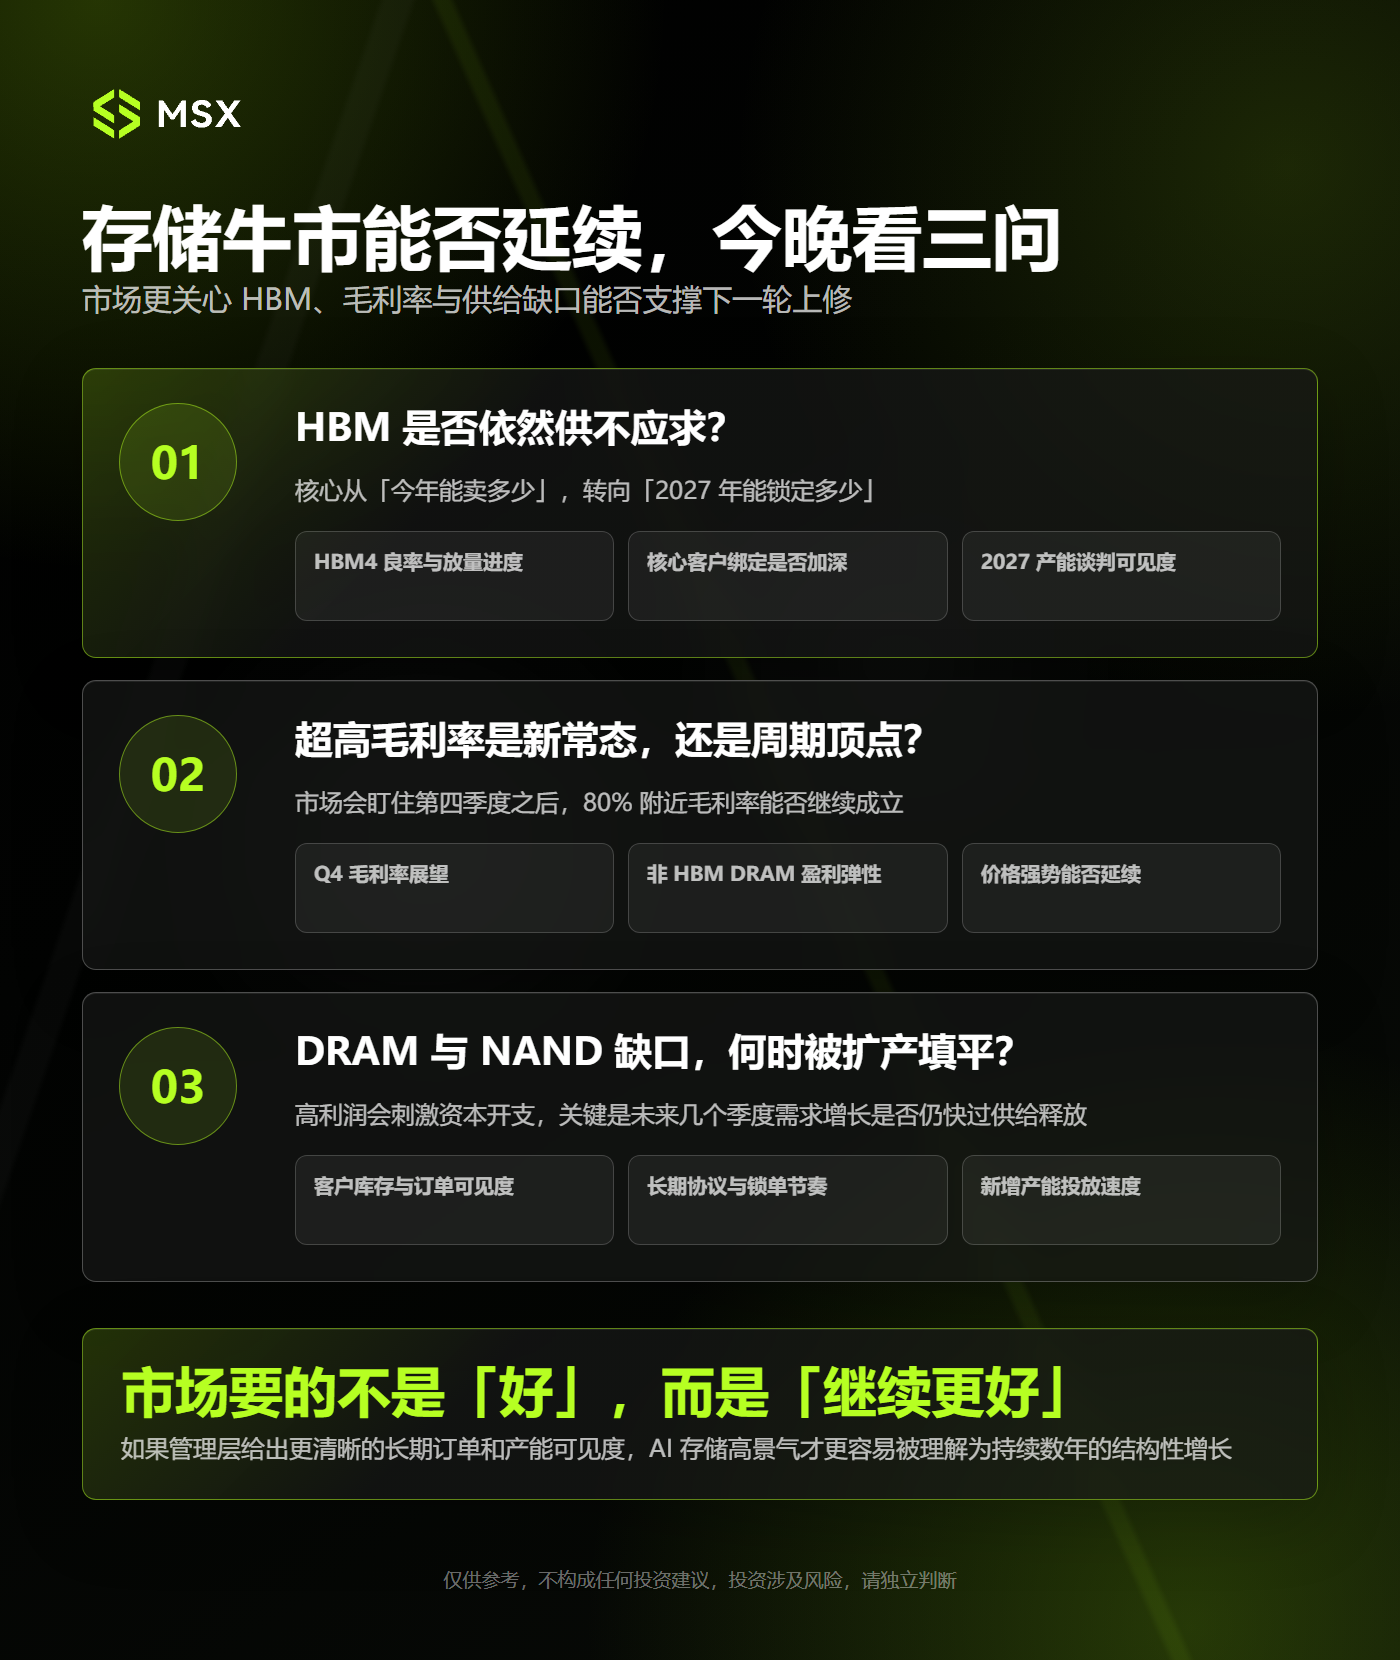
1. Is HBM Still in Short Supply?
Micron's primary growth narrative remains HBM. It's well known that AI servers need more than just GPUs. As the computing power, power consumption, and data throughput of single AI accelerators continue to rise, HBM has evolved from a standard supporting component into a critical factor determining the performance of the entire AI system.
Micron has already started ramping up production and shipments of HBM4, particularly for Nvidia's next-generation Vera Rubin platform. Its HBM capacity for 2026 is largely spoken for. Thus, the market's focus this time will shift from "how much can be sold this year" to "how much can be locked in for 2027."
During the earnings call, investors are likely to seek answers to several questions: Is HBM4 yield and ramp-up progress on track? Is Micron deepening its ties with key customers? How far along are capacity negotiations for 2027? Can subsequent products like HBM4E help close the gap with SK Hynix?
If Micron provides clearer visibility into long-term orders and capacity, the market will more readily interpret the current HBM boom as a multi-year structural growth story rather than a product cycle nearing its peak. Conversely, if management is vague about demand and orders for 2027, the market may begin to suspect that the tightest and most pricing-powerful phase for HBM has already been priced into the stock.
2. Are Ultra-High Gross Margins the New Normal or a Cyclical Peak?
For Micron, profit leverage comes not just from shipment volumes but also from pricing and gross margins. Last quarter, non-GAAP gross margin reached 74.9%, and the Q3 guidance is around 81%. This means for every $100 of revenue, Micron expects to retain over $80 in gross profit.
Such high gross margins are uncommon in past memory cycles. They are driven by a combination of factors: a rising mix of high-value products like HBM, broad-based DRAM and NAND price increases, supply constraints, and a continued product mix shift towards data centers.
Importantly, the factors boosting Micron's profitability aren't limited to HBM. Management has previously noted that some non-HBM DRAM products have also shown exceptionally strong profitability, sometimes even exceeding that of HBM. This suggests the current memory cycle has expanded beyond a single premium niche into the broader DRAM market.
Therefore, the most important aspect of this report isn't just whether the gross margin hits 81%, but how management describes the trajectory for Q4 and beyond. If Micron continues to guide for gross margins above 80%, it signals a persistent supply-demand gap and strong pricing power, allowing the market to raise its earnings power estimates. However, if margins just meet guidance or management's tone turns cautious, a "Sell the News" event becomes more likely.
3. When Will Capacity Expansion Fill the DRAM and NAND Gap?
Every memory bull market eventually circles back to one question: When will supply catch up with demand?
This cycle has persistently exceeded expectations because, on one hand, AI data centers are rapidly consuming more HBM, server DRAM, and enterprise SSDs. On the other hand, memory capacity cannot be simultaneously ramped up quickly.
HBM production, in particular, consumes significant wafer and advanced packaging resources. As manufacturers allocate capacity towards HBM, it inevitably constrains the supply of traditional DRAM to some extent, fueling price increases across the entire product line.
Previously, Micron indicated that in the medium term, it can only satisfy about one-half to two-thirds of customer demand, and some new fabs won't contribute meaningful output until much later. This implies that, at least in the near term, new capacity struggles to rapidly close the gap.
However, the market will also watch the other side: the incentive. Lured by high profits, Micron, Samsung, and SK Hynix are all increasing capital expenditures. If the pace of new capacity release outpaces AI demand growth, the memory industry could still revert to a traditional cycle of price competition and inventory correction.
Therefore, in this call, management's commentary on customer inventories, order visibility, long-term agreements, and the pace of new capacity additions may be more critical than single-quarter shipment numbers. The key will be whether Micron can demonstrate that demand growth continues to outpace supply release for at least the next few quarters.
III. 13% Options-Implied Volatility: What is the Market Betting On?
Beyond the fundamentals, the options market has already provided a different kind of answer.
Based on option pricing around the close on June 22nd, the combined price of at-the-money Call and Put contracts expiring June 26th was approximately $159. Relative to Micron's then stock price of ~$1,211, the options market implied an earnings move of about 13%.
This means that if you buy these options today, you'd theoretically need the stock to move more than roughly 13% after the report to easily cover the premium cost. For investors holding the stock, this also signals that a double-digit gap move following the report wouldn't be surprising.
In other words, the options market isn't pricing in a small move; it's pricing in a very significant reaction to the earnings report.
More importantly, the high implied volatility also reflects the market's current divergence: one camp believes AI memory is still in its early days of insufficient supply; the other camp worries that future growth has already been priced into the stock.
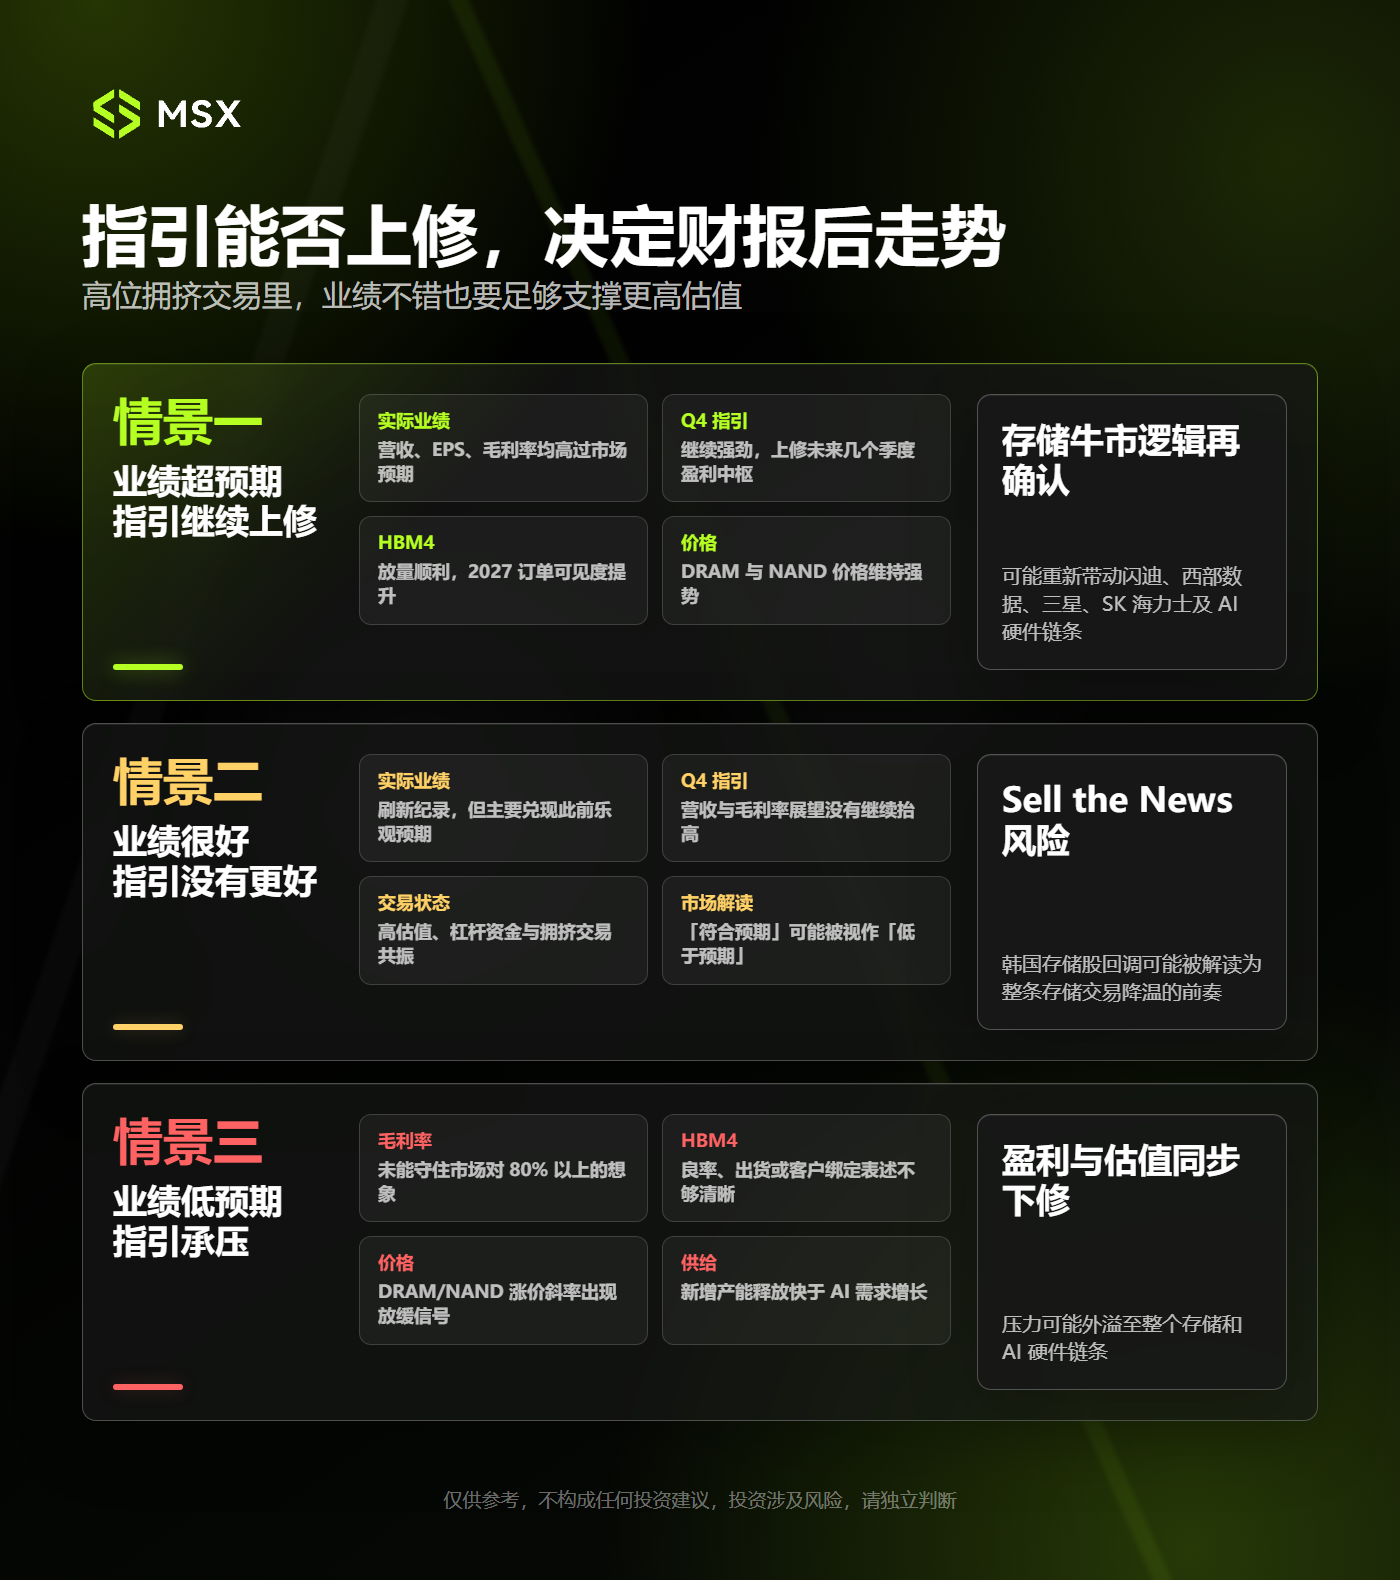
Analyzing the post-earnings scenarios, the MSX Research Institute sees three main possibilities:
Scenario 1: Earnings Beat Expectations, Guidance Raised Further
This is the most ideal outcome. If Micron surpasses current market expectations for revenue, EPS, and gross margin, coupled with strong Q4 guidance, and reinforces the narrative of smooth HBM4 ramp-up, improved 2027 order visibility, and firm DRAM/NAND pricing, then the bull case for memory would be further validated.
In this scenario, a rise in Micron's stock could re-energize the entire memory supply chain, including Sandisk, Western Digital, Samsung, SK Hynix, and some semiconductor equipment and AI server-related names. However, even with a strong report, one must be wary of profit-taking at these elevated levels. As mentioned, the options market already has a large move priced in; a big after-hours gain doesn't guarantee a one-way rally the next trading day.
Scenario 2: Strong Earnings, But Guidance Doesn't Get Even Better
This is arguably the biggest risk for this report. Micron could easily deliver a record-breaking quarter. But if the data merely confirms its previous guidance, or if the Q4 outlook for gross margins and revenue isn't raised further, the market might still choose to sell.
This isn't because Micron's fundamentals suddenly deteriorated. It's because the market had already priced in a "beat." For high-flying, crowded stocks, meeting expectations can sometimes be equivalent to disappointing them.
The recent turmoil in the Korean market reinforces this risk. On June 22nd, South Korean regulators publicly reflected on their rapid approval of single-stock leveraged ETFs for Samsung and SK Hynix. A day later, the KOSPI index plunged nearly 10%, with the two memory giants both falling over 12%.
This pullback doesn't necessarily mean a reversal in long-term AI memory demand. But it serves as a reminder that when high valuations, leveraged money, and crowded trades converge on a single theme, any information falling short of perfection can be rapidly amplified.
Therefore, the decline in Korean memory stocks acts as a pre-Micron stress test. If Micron's results are strong enough, it could restore market confidence. But if Micron delivers merely a "normal good" report, the Korean market correction could be interpreted as a signal that the overall memory trade is beginning to cool off.
Scenario 3: Gross Margin or Forward Guidance Misses Expectations
If Micron reports figures for HBM4 progress, gross margins, product prices, or Q4 guidance that are significantly below expectations, the downside pressure on the stock could be substantial.
The reason is that Micron's current stock price rests on at least three layers of expectations:
• Layer 1: Long-term memory demand driven by AI computing expansion.
• Layer 2: A pricing cycle powered by tight DRAM and NAND supply-demand dynamics.
• Layer 3: Continuous improvement in Micron's market share and profitability in the premium HBM segment.
If any one of these layers cracks, the market could simultaneously lower future earnings forecasts and valuation multiples. The resulting impact wouldn't be isolated to Micron but could spread throughout the entire memory and AI hardware ecosystem.
Conclusion
Based on currently available information, Micron's long-term thesis remains intact. AI servers continue to consume more HBM and DRAM, data center SSD demand is growing steadily, and the traditional NAND market is also recovering. New production capacity is unlikely to come online rapidly in the near term, so supply constraints continue to grant memory makers strong pricing power.
But strong fundamentals don't mean stocks are risk-free. When revenue, profit margins, and stock prices have already set consecutive records, the market's yardstick for evaluating Micron changes. In the past, the company only needed to prove the industry was recovering. Now, it needs to prove not only that this boom can continue, but that it will be even stronger than what investors are already imagining.
Therefore, the real suspense of this earnings report isn't whether Micron can deliver another good quarter. It's whether it can once again expand the market's horizon for future expectations. In a nutshell, Micron no longer just needs to prove the memory bull market is still running. It needs to prove that this cycle's finishing line is farther away than the market currently believes its current price suggests.