






Author: David Hoffman
Translation: TechFlow
If you missed last week's news, I sold my Ethereum.
For someone who has built a career, community, identity, and business around Ethereum, this was not an easy choice to make.
The decision to sell requires a more thorough explanation than a few scattered tweets can provide.
It's best to read this article from Bankless.com.
But if you prefer the less polished reading experience of a native X post, the content is below.
tl;dr
The "ETH is money" thesis hasn't failed... it's just been validated. Ethereum has gotten the price it deserves, and I don't see ETH's value as an asset being reassessed, either up or down.
PS: I'm very bullish on Ethereum. I expect the Ethereum network to perform exceptionally well in the future. But I believe only a small portion of Ethereum's success will be reflected in the price of ETH.
Here's the article content:
ETH Becoming Money Has Always Been a Distant Dream
Money is a coordination game, and coordination is hard.
The Ethereum project itself is a series of coordination challenges across multiple levels, and the "ETH is money" thesis requires all these levels to succeed, and to succeed with confidence.
ETH can only become money if every layer of Ethereum's techno-social stack performs better than its competitors.
Given the ambition of the Ethereum project, achieving its most successful version has always been a daunting challenge. Despite its shortcomings, Ethereum has achieved remarkable results, and its current market cap is well-deserved.
However, the window of opportunity... the hope that Ethereum will be "reassessed" by the market seems to be fading.
Ethereum is money to some extent. But it's not the most perfect form of money we collectively pursued.
Ethereum Is a Coordination Game
A Turing-complete blockchain is such a powerful concept that Ethereum's greatest potential is the entire crypto space, covering everything.
The only obstacle to Ethereum achieving 100% dominance across all domains is coordination.
Ethereum's leadership needs to be decentralized enough, and governance needs "rough consensus" to create credible neutrality, maximizing Ethereum's adoption.
Ethereum's leadership needs to respond to market dynamics and operate like a startup, constantly facing existential threats of obsolescence.
Ethereum's L2s need to operate independently of the base layer and make their own market choices, but they also need to be economically tied to and bound by the broader Ethereum economy and Ethereum brand.
Ethereum's roadmap needs to be executed in a specific order to maximize its momentum and market dominance, effectively suppressing competition and maximizing confidence in Ethereum and ETH.
Key technologies need to be researched and developed fast enough to prove Ethereum's utility to the outside world and maintain its competitive edge.
The "ETH is money" thesis is about creating a revolutionary and powerful financial asset that, through its unique attributes as a superior global store of value, attracts people who are otherwise indifferent. The Ethereum brand and ETH's strength must be robust enough to make baby boomers not only feel safe but, due to Ethereum's dominance, to consider ETH a key part of their retirement portfolios.
To achieve the "ETH is money" goal, every upstream layer of ETH needs to run at peak performance.
Ethereum is not Bitcoin—it chose a difficult path. Bitcoin chose to strip all information from its blockchain to elevate its own status.
Ethereum chose to add everything to its blockchain to maximize the use of its block space. Only by doing this optimally and before its competitors can Ethereum achieve global monetary status.
We've made some progress, and Ethereum has reached its maximum potential market cap share.
I'm afraid the best time to play this game has passed.
The Environment May Never Allow This
Looking back over the years, I see the immense environmental challenges Ethereum has had to overcome.
Layer 1 Assets Are Inextricably Linked to Revenue
Despite the difficulty of evaluating smart contract chains based on fees and revenue... fees and revenue are clearly how smart contract L1 assets enhance their pricing power.
By 2026, we'll have a wealth of data proving all these things are closely related: L1 activity, L1 fees, and L1 native asset price appreciation.
• In 2021, ETH dominated, with the highest market share of L1 revenue.
• In 2024, SOL saw a unique rise in its L1 revenue market share relative to the rest of the industry, establishing its dominance.
• In 2026, NEAR will experience a price revaluation, alongside fundamental growth in L1 revenue and NEAR consumption.
You can also look at assets like BNB and TRX—they're perhaps the highest cumulative revenue projects ever. Their charts look like what I expected ETH's chart to look like, had ETH maintained its dominance in the L1 fee market for longer than just 2022.
The Strong Crypto Version Didn't Work
@0xMakesy put it well:
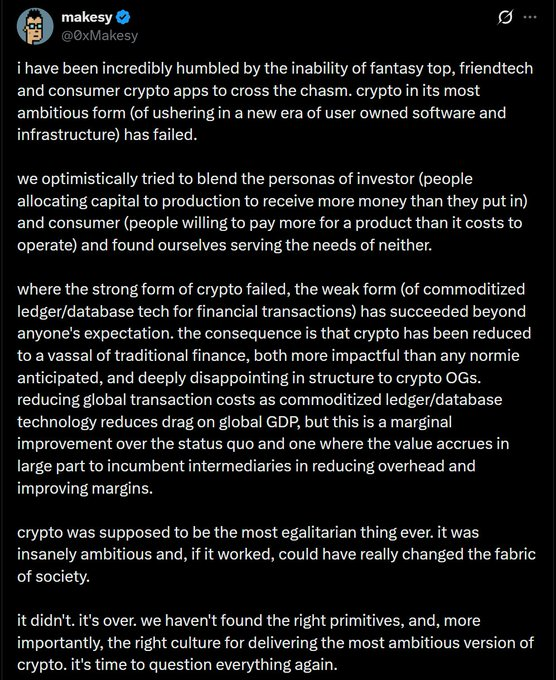
Ethereum represents the strong version of crypto—crypto as an end in itself, self-sustaining and self-perpetuating. DeFi, NFTs, DAOs—we are rebels building an alternative financial system created by and for the people, turning imagination into money.
There's also a weaker version: providing efficient ledger infrastructure for the backend of financial institutions. This weaker version would power the stronger one, channeling demand for internet-native ledgers into inward capital flows—toward crypto, toward Ethereum, and ultimately toward ETH.
Perhaps, if Ethereum had executed better, faster, and more efficiently, and if crypto hadn't attracted so many scammers and extractors, the industry could have earned the influence and respect I've always believed it deserves. But the only period when crypto had a truly positive image in the public eye was from late 2020 to early 2022. Otherwise, crypto has been associated with scams, frauds, get-rich-quick schemes, and being useless to ordinary people.
ETH Is a Currency Dependent on "Strong Crypto"
The moment Ethereum shined as a network currency was precisely when everyone was forced online. The world discovered crypto for the first time, and in that brief window, it was all the rage.
Money is a coordination game, and a currency's value rests on belief. In 2021, the general public believed in Ethereum (ETH): it was cool, disruptive, and widely popular. Bitcoin had these traits too and maintained them better than Ethereum after 2021.
This raises an unsettling possibility: strong crypto may never have reached a stable equilibrium. The monetary system was so distorted during the COVID era that Ethereum's status as money might have benefited from that distortion. If so, Ethereum's standing as money has always depended on the strong crypto system performing better than it actually does.
Ethereum's utility also helps other currencies thrive.
Is Bitcoin money? Is the U.S. dollar money? Is gold money? It doesn't matter—whatever the currency, it gets tokenized on Ethereum.
In 2020, Nick Carter debated the "unbanked" case.
Stablecoins are likely to attach themselves to Ethereum, not as native tokens. At the time, Ethereum's stablecoin total was $3 billion. Now it's $163 billion, a 54-fold increase.
The utility Ethereum provides helps expand the monetary network to encompass all forms of money, which is why the U.S. is so optimistic about crypto and uses it for stablecoins. Ethereum is helping the U.S. maintain dollar dominance, and leveraging this fact is clear U.S. government policy.
Positive spillover effects. Clearly, the value of money far exceeds what the U.S. government sees in Ethereum's stablecoin ecosystem.
Ethereum Is a Giver, Not a Taker
At its core, Ethereum is a giver, not a taker.
It provides the world's most secure block space to L2s at cost.
It tokenizes global assets at cost.
It secures billions of dollars in DeFi at cost.
Ethereum charges no fees for any of its transactions.
That's the nature of open-source software and Ethereum's power. Ethereum offers its entire, critically important value to the world at cost.
Ethereum is noble. Ethereum is good.
Ethereum is the world's most successful nonprofit organization.
Ethereum naturally sees massive adoption. It is, and may be, the most influential open-source software project in human history, with the "nonprofit protocol" being one of its core features.
That's why Ethereum's path to becoming money depends on its sustained, extremely high market dominance.
Eventually, as block space becomes commoditized, fees drop to zero. As long as Ethereum, not a competitor, is commoditizing block space, it can maintain its margins and dominance.
Ultimately, the theory of protocol bloat gives way to the theory of application bloat, and applications capture the remaining profit. As long as these apps are Ethereum apps, not competitors', that's fine for Ethereum.
"ETH is money" is hard to reconcile with "Ethereum is a giver, not a taker." Ethereum's architecture is designed to give everything back to the ecosystem, taking only the minimum needed to sustain the network.
Architecturally, Ethereum doesn't prioritize Ether (ETH)—this is a feature, not a flaw. Ether becomes money only if Ethereum wins the game it's not architecturally designed to win.
If Ethereum can maintain astonishing market dominance, this approach might work.
The "Ethereum is money" thesis asks a lot of Ethereum.
Achieving "ETH is money" requires everything to go right for Ethereum. Its margin for error is much smaller than I initially thought. Ethereum's strong momentum in 2021 and 2022 made "ETH is money" seem inevitable.
In hindsight, Solana's rise in 2021 and the growing anti-Ethereum sentiment were the first major signs that Ethereum's and ETH's coordination game wasn't going as planned.
European financial groups need to be decentralized and allow other power structures to emerge. But they also need to respond to market forces with urgency and drive, like startups facing existential threats of obsolescence.
L2 teams need autonomy in decision-making but must also operate within the larger brand framework of Ethereum and ETH. Technical synchronization between Ethereum and its L2 teams needs to execute faster.
The value of smart contract chains depends on fees. To break free from this model, Ethereum needs to rewrite the rules through overwhelming success.
The Ethereum Is Money Thesis Hasn't Failed
It just hasn't reached its full potential either.
Ethereum made noble choices, opting for the most difficult, most ambitious, and most idealistic path for its future.
It's achieved some incredible victories but also failed at some challenges.
Ethereum's market cap is where it should be.
I'm extremely bullish on the Ethereum network and its ecosystem—Ethereum's architecture is designed to maximize the success of its applications, L2 services, and ecosystem. The "big apps" thesis means Ethereum's apps will capture all the fees, while the rollup-centric roadmap means L2 services will capture 97% of the profits.
As for the Ethereum asset, I find it hard to imagine its structural valuation changing in either direction—up or down.
So I sold my ETH not because I'm bearish on ETH, but because I believe the "ETH is money" thesis has run its course, and I want to allocate my capital to other opportunities I see in the market.