






Original Title: "Powell Exits, Oil Prices Enter, Hawkish Tone Intensifies Fully"
Author: Zhao Ying
Source: Wall Street Insights
Core Thesis: The Federal Reserve kept rates unchanged at its April meeting, but internal hawkish divisions deepened. Coupled with surging oil prices and Powell's term nearing its end, market expectations have shifted from pricing in rate cuts to pricing in rate hike risks. The interest rate environment is entering a complex new phase driven by multiple factors including inflation, energy, employment, and policy communication.
Key Elements:
a. Three dissenting votes against retaining the dovish bias signal a loosening consensus on policy direction within the FOMC, prompting markets to begin pricing in rate hikes rather than rate cuts.
b. The Iran situation pushed Brent crude to $120/barrel. On the day, of the 10 basis point rise in the 2-year Treasury yield, approximately 7 basis points came from the oil price shock, far exceeding the impact of the Fed's decision itself.
c. Powell confirmed this meeting was his last as Chair. The Senate has advanced Kevin Warsh's nomination to be Chair, increasing uncertainty around policy style and communication framework.
d. Goldman Sachs, Bank of America, JPMorgan, and other institutions all believe the bar for rate cuts has been raised. HSBC forecasts no rate cuts in 2026-2027. The market has priced in roughly 10 basis points of rate hikes, the most hawkish level since June 2025.
e. Powell stated that adjustments to policy guidance "could come as early as the next meeting." Future dovish bias will shift towards a more neutral stance, but only on the condition that oil prices stabilize and progress is made on tariff issues.
The Fed held steady, yet Wall Street heard a louder hawkish screech. Three dissenting votes against retaining the dovish bias, inflationary pressures from soaring oil prices, and the end of Powell's chairmanship have collectively pushed the market from a rate-cut trade to a more complex pricing of rate hike risks.
According to Trac Trading Desk, at the April 29 FOMC meeting, the Fed kept the federal funds rate target range unchanged at 3.50%-3.75%. Post-meeting analyses from Goldman Sachs, Bank of America, JPMorgan, and HSBC all point to the same conclusion: what truly matters is not the rate decision itself, but the widening divergence in the statement's language and the loosening consensus on policy direction within the committee.
The deteriorating situation in Iran made oil prices another major theme of the day. BofA noted that the 2-year Treasury yield rose 10 basis points on the day, of which only about 3 basis points occurred after the Fed's decision, while the remaining 7 basis points were primarily driven by an 8% single-day surge in Brent crude to $120/barrel. JPMorgan also believes the Iran situation and risks in the Strait of Hormuz pushed energy prices higher, directly compressing the Fed's room for easing.
The power transition amplified policy uncertainty. Powell confirmed this would be his last FOMC meeting as Fed Chair and stated he would remain on the FOMC as a regular governor after his term ends, with the timeline for his departure uncertain. Meanwhile, the Senate Banking Committee has advanced Kevin Warsh's nomination to be Fed Chair. An era of monetary policy has officially ended, and the policy style and communication framework of the successor are becoming new focal points for the market.
Three Dissenting Votes: Dovish Bias No Longer Solid
The most closely watched signal from this meeting was the division within the FOMC over the statement's wording.
Goldman Sachs economist David Mericle noted that three members—Hammack, Kashkari, and Logan—voted against the language implying a dovish bias in the statement, a result that surprised Goldman. Meanwhile, Miran supported a rate cut, consistent with Goldman's prior assessment.
The dispute centered on the phrase "timing of additional adjustments." In market context, this wording was seen as signaling the possibility of further rate cuts. The three members' opposition to retaining this phrase indicates that some policymakers are no longer willing to continue sending a one-sided easing signal to the market.
Powell acknowledged in his press conference that there had been "intense discussion" around the policy guidance. He said the number of members favoring a shift to more neutral guidance increased compared to March, and the FOMC's central tendency is moving toward a "more neutral" interest rate outlook, though a majority felt the timing wasn't right yet. He even suggested the wording adjustment "could come as early as the next meeting" – the June 16-17 meeting.
HSBC also emphasized that the essence of this division is that the policy direction is no longer one-sided. While the three members supported keeping rates unchanged, they explicitly opposed retaining the dovish bias, effectively signaling to the market that the next move could be either a rate cut or a rate hike.
"Rate Hikes" Return to Pricing, Bar for Cuts Raised
The consensus on Wall Street is that the Fed hasn't formally turned hawkish on rate hikes, but the long-dormant word "rate hike" has officially re-entered the market's lexicon.
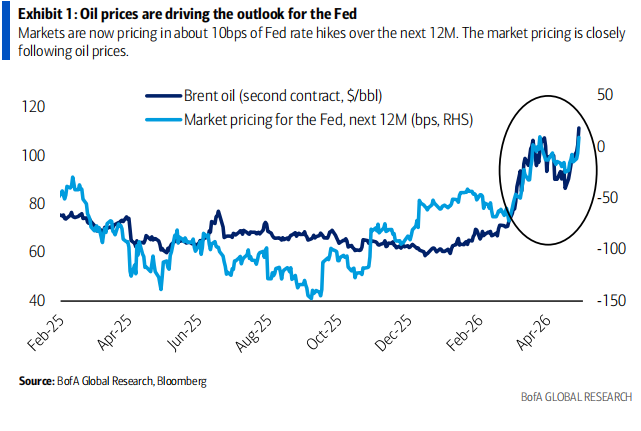
BofA stated that after the slightly hawkish FOMC meeting, combined with record oil prices, the market has now priced in roughly 10 basis points of rate hikes over the next 12 months. The bank noted that this is different from the 2022 rate hike cycle, as the current energy shock also pressures growth, a point Powell hinted at in his press conference.
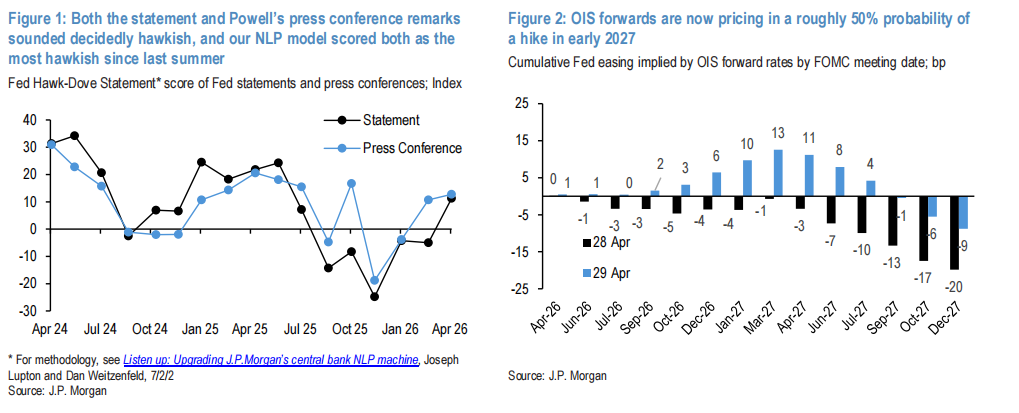
JPMorgan's interpretation was more hawkish. Its natural language processing model showed that the hawkishness score for both the statement and Powell's press conference hit their highest levels since June 2025. The bank stated that money market pricing has rapidly shifted from "nearly one full rate cut by end-2027" to "nearly a 50% probability of a rate hike by early 2027."
Goldman Sachs maintained a more cautious view. It still forecasts rate cuts in September and December but believes the bar for cuts has been significantly raised, barring a significant weakening in the labor market. Goldman said the risk of a prolonged rate pause is rising, but remains highly skeptical of the possibility of rate hikes.
HSBC's forecast was the most aggressive. It predicts the Fed will not cut rates in either 2026 or 2027. HSBC believes rate cuts are nearly impossible unless core PCE inflation falls below 3% and especially 2.5%, and its own forecasts show core PCE remaining above 3% through end-2026 and above 2.5% through end-2027.
Oil Prices Take Center Stage, Iran Situation Dominates Pricing Logic
Unlike previous meetings where the Fed's statement dominated market reaction, energy prices were the core variable for the interest rate market on this day.
BofA pointed out that of the 10 bps rise in the 2-year yield, only about 3 bps could be attributed to the Fed decision itself, with the bulk of the increase coming from Brent crude rising to $120/barrel. The bank believes the main driver of the current Fed outlook is the Iran situation and oil prices, rather than a simple policy reaction function.
JPMorgan also attributed the front-end yield rise and curve flattening to the deteriorating Middle East situation and risks in the Strait of Hormuz. Rising oil prices not only boost inflation expectations but also make it harder for the Fed to signal easing.
In his press conference, Powell explicitly mentioned that with high uncertainty around war and energy prices, most members saw no need to adjust policy guidance now. JPMorgan noted that Powell set preconditions for potential rate cuts, requiring stabilization in energy prices and progress on tariff issues.
Goldman believes that even if geopolitical conflicts end, some FOMC members may remain hesitant about rate cuts if inflation remains closer to 3% rather than 2%. Even if the inflation overshoot stems primarily from tariffs and energy price pass-through, policy easing may not arrive quickly.
Powell's Farewell, Warsh Takes Over as a New Variable
This meeting also marked the end of Powell's tenure as Chair.
BofA noted this was Powell's final FOMC meeting as Fed Chair. Goldman Sachs' report also mentioned that Powell stated he would remain on the FOMC as a regular governor after his Chair term ends on May 15, with the exact timeline for his departure undetermined.
Regarding his reasons for staying, Goldman said Powell indicated he is waiting for relevant investigations to conclude in a transparent and definitive manner, and will leave when he deems appropriate. JPMorgan and HSBC also noted Powell's intention to maintain a low profile and not obstruct the FOMC's operations under Warsh's leadership.
The progress of Warsh's nomination has become a market focus. JPMorgan stated the Senate Banking Committee voted along party lines to approve his nomination. HSBC noted the full Senate vote has not yet occurred, but if smooth, Warsh could officially assume office before the June meeting.
HSBC believes Warsh could bring systemic changes to the policy communication framework. The bank's rates strategists noted that Warsh has expressed skepticism about the Fed's "dot plot" rate projection mechanism. If forward guidance is weakened, bond market volatility could increase, and term premiums on longer-dated yields could face upward pressure.
Rate Volatility and Policy Uncertainty Coexist
For fixed-income investors, the message from this meeting is multifaceted. Front-end yields are pressured by oil prices and hawkish pricing, pushing back rate cut expectations, but rate hikes are not yet the consensus base case for Wall Street banks.
BofA believes that for the investment-grade bond market, the current rise in yields partly hedges the impact of rate volatility. With implied rate volatility still below its March peak, the technical backdrop for investment-grade bonds offers temporary support.
JPMorgan cautioned that the combination of front-end yield pressure, expensive valuations for intermediate-term Treasuries, and uncertainty from the leadership transition means the rate market is entering a more complex phase of trading.
HSBC maintains its "max bullish" stance on a multi-asset basis, focusing on US equities. The bank stated that despite the hawkish repricing of rate expectations, risk assets performed strongly in April, with optimism around AI supply chain earnings remaining a key narrative for multi-asset markets.
Overall, Wall Street's conclusion on this FOMC meeting is: the Fed didn't change rates, but it changed the market's probability distribution for the next move. With Powell exiting, oil prices entering the scene, and Warsh set to take over, investors face not just a simple rate cut timeline, but a new rate environment driven by the interplay of inflation, energy, employment, and policy communication.