






Authored by: Pine Analytics
Compiled by: Saoirse, Foresight News
TAO is currently priced around $275, with a market cap of $2.6 billion and a fully diluted valuation of $5.8 billion. The project has received institutional backing from Grayscale (which filed a NYSE ETF listing application in December 2025) and public endorsement from NVIDIA CEO Jensen Huang. Its token supply narrative is also highly compelling: a fixed maximum supply of 21 million tokens, employing a Bitcoin-style halving mechanism. After the first halving in December 2025, the daily issuance dropped from 7,200 to 3,600 tokens. The number of subnets grew from 32 to 128 within a year, and Templar's Covenant-72B training demonstrated that decentralized compute can produce large language models with baseline competitiveness.
This report does not dispute the above facts. What we aim to explore is: can the network's economic model generate real external revenue sufficient to support its current valuation scale, and how does its competitiveness truly fare against centralized service providers and self-hosted compute?
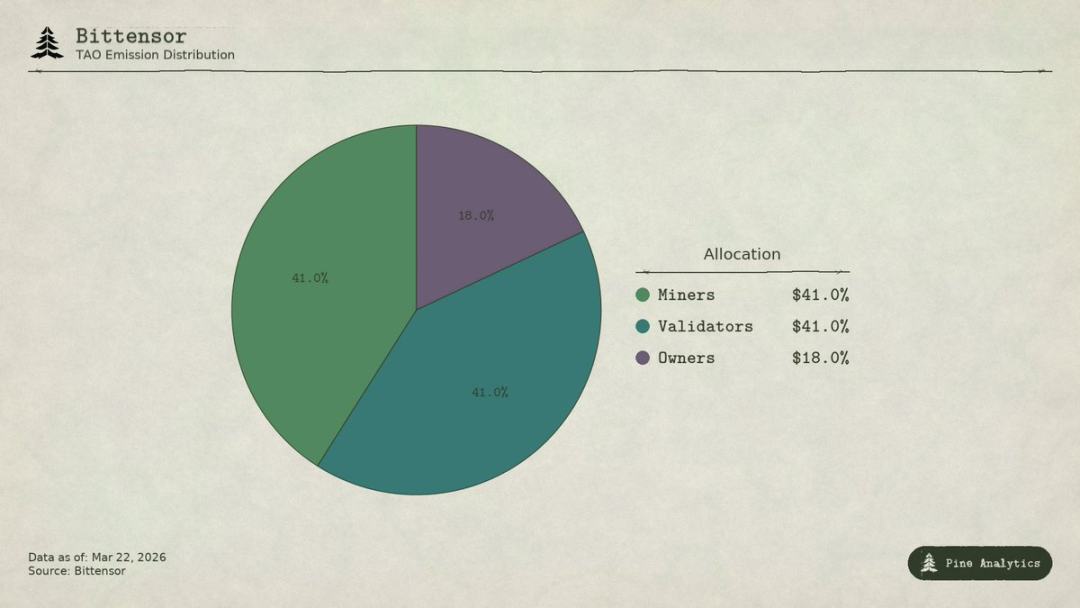
Bittensor (TAO) Token Issuance & Distribution
How Network Value Flows
Bittensor has four main participant types:
Subnet Owners build specialized AI marketplaces, receiving 18% of the subnet's TAO issuance rewards.
Miners perform AI tasks (inference, training, data processing), receiving 41%, totaling approximately 1,476 TAO daily (~$148 million annualized).
Validators score miner outputs, receiving 41%.
Stakers lock TAO into subnet liquidity pools to receive subnet-specific tokens.
Under the Taoflow model, a subnet's reward share is determined by net TAO stake inflow; negative net inflow results in no rewards. The top ten subnets control roughly 56% of total network issuance.
TAO is the universal network token: used for miner registration, validator staking, subnet token purchases, and service payments. In theory, subnet activity should create structural demand for the base token.
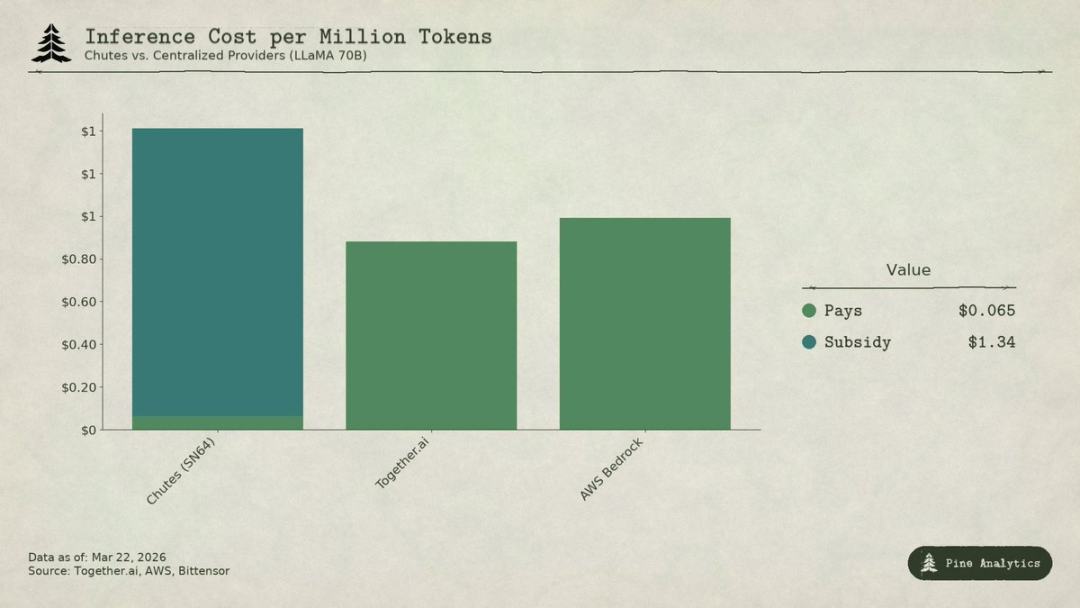
Comparative Analysis: Bittensor Subnet Chutes (SN64) vs. Centralized Provider LLaMA 70B Model Inference Costs
Current State of Demand
Transparent Supply vs. Opaque Demand
Bittensor's supply side is highly transparent: 3,600 TAO are distributed daily via programmed rules, halving is hardcoded, and staking ratio (~70%), distribution proportions, and flow data are all on-chain.
However, the demand side is completely opaque. There is no unified dashboard tracking external revenue per subnet. Actual usage of AI services (inference, computation, training) occurs off-chain and is not recorded on the blockchain. Investors can only infer demand through indirect metrics like stake flow, subnet token prices, and self-reported data from projects. This opacity is structural, not temporary. The blockchain records token transfers, not API calls.
What follows is the most complete picture of demand-side activity as of March 2026.
Chutes (SN64): Low Prices Rely Entirely on Subsidies
Chutes commands 14.4% of total network issuance, the highest of any subnet. Developed by Rayon Labs, it offers serverless inference for open-source models, pricing 85% lower than AWS and 10%–50% lower than Together AI. Its usage metrics lead the ecosystem: over 400,000 users (over 100,000 API users), over 5 million daily requests, 9.1 trillion tokens processed cumulatively, with average daily token generation surging from 6.6 billion to 101 billion over three days. It's also a top inference provider on OpenRouter, with some models outperforming centralized competitors.
However, this low pricing stems not from operational efficiency, but from subsidies.
Based on its 14.4% share, Chutes receives ~518 TAO daily, worth ~$52 million annualized. Its external annual revenue is only ~$1.3–2.4 million (the higher figure is team-reported, unaudited). The protocol's subsidy ratio to this subnet is approximately 22:1 to 40:1. For every $1 users pay, the network must inflate and release $22–40 worth of TAO as subsidy.
Removing the subsidy and reverse-calculating from its ~101 billion daily tokens processed, the cost price would be ~$1.41 per million tokens. Current centralized market prices:
Together.ai's LLaMA 3.3 70B Turbo: ~$0.88 / million tokens.
DeepSeek V3: ~$0.40–0.80.
Smaller models can go as low as $0.18.
This means without subsidies, Chutes' price would be 1.6–3.5x more expensive than centralized alternatives. The purported 85% cost advantage completely reverses. Its low prices are essentially funded by TAO holders through inflation, not structural efficiency from decentralization.
When the next halving arrives (expected late 2026 or 2027), either prices double, miners leave, or the gap between subsidy and revenue widens further.
Some may draw parallels to early internet subsidies for customer acquisition, but companies like Uber, DoorDash, and AWS built switching costs during subsidy periods: proprietary platforms, driver networks, enterprise ecosystems. Bittensor subnets have no such moats: models are open-source, interfaces are standardized, and users can switch providers at zero cost. Once subsidies recede, no lock-in mechanism retains users.
Rayon Labs also operates SN56 and SN19, collectively controlling ~23.7% of total network issuance, none of which disclose external revenue. A single team effectively controls nearly a quarter of the network's incentive distribution.
Targon, Templar & Other Subnets
Targon (SN4) is the highest-revenue subnet, operated by Manifold Labs, offering confidential GPU compute services to enterprises. Estimated annual revenue is ~$10.4 million, corresponding to a $48 million valuation, a P/S ratio of ~4.6x—the most solid valuation within the ecosystem. However, the $10.4 million figure is a forecast cited by multiple reports, not an audited number.
Templar (SN3) completed the Covenant-72B training, with a $98 million market cap, but has zero external revenue. Training API and enterprise sales are in progress, with no paid product launched yet.
The remaining 120+ subnets either have no public revenue or are in early product stages, primarily surviving on token issuance subsidies.
Overall Picture
The total confirmed annual external revenue for the entire network is only ~$3–15 million. The annualized subsidy for Chutes alone (~$52 million) exceeds the upper bound of the entire network's external revenue.
Based on a $2.6 billion market cap, the revenue multiple is ~175–200x; based on the $5.8 billion fully diluted valuation, it's close to 400x. In contrast, centralized AI compute companies have recently raised at valuations of 15–25x forward revenue, and high-growth SaaS rarely sustains above 50x long-term. Bittensor's valuation multiples are 4–10x those of aggressive industry benchmarks.
The vast gap between valuation and demand fundamentals indicates the market prices TAO almost entirely based on supply-side scarcity (halving, staking lock-up), institutional catalysts (Grayscale ETF, exchange listing expectations), and AI sector sentiment—not real economic output. These are indeed price drivers, but they are entirely separate from the logic of "Bittensor as an AI service network creating sustainable value."
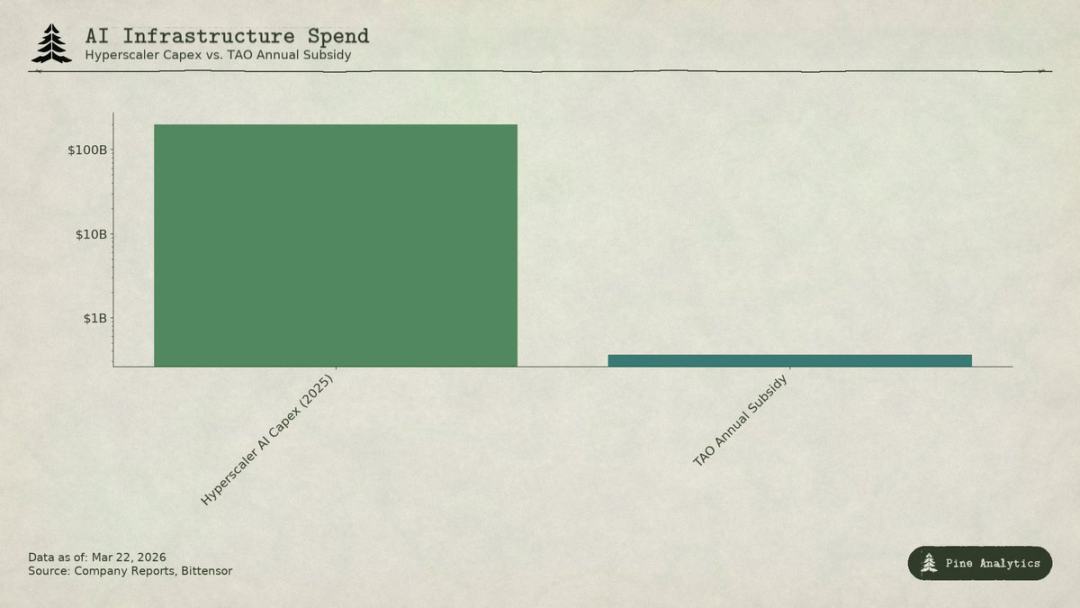
Comparison: Hyperscale Cloud Provider AI Capex vs. Bittensor (TAO) Annual Subsidy Scale
Pricing Dilemma: Squeezed from Both Sides
Subnets face pressure from two directions:
Upper Bound: Self-Hosted Cap
All models on the platform are open-source with public weights. Running a 70B model on a single H100 costs only $40–50 per day in total costs. Tools like vLLM and Ollama make local deployment extremely simple. NVIDIA's next-generation chips will further slash inference costs. Institutions with sufficient volume will find self-hosting cheaper.
Lower Bound: Cloud Giant Pressure
Microsoft, Google, Amazon, and Meta's combined AI capital expenditure in 2025 exceeded $200 billion. They have hardware priority allocation, dedicated data centers, enterprise customer relationships, and can subsidize AI with cash flow from other businesses. Bittensor's entire annual incentive budget (~$360 million) is less than Microsoft's weekly AI infrastructure spend. Specialized service providers also compete on price using VC subsidies on open-source models.
Subnet pricing is compressed into an extremely narrow band, while also bearing decentralization-specific costs: token friction, validator node overhead, subnet owner cuts, network latency, etc.
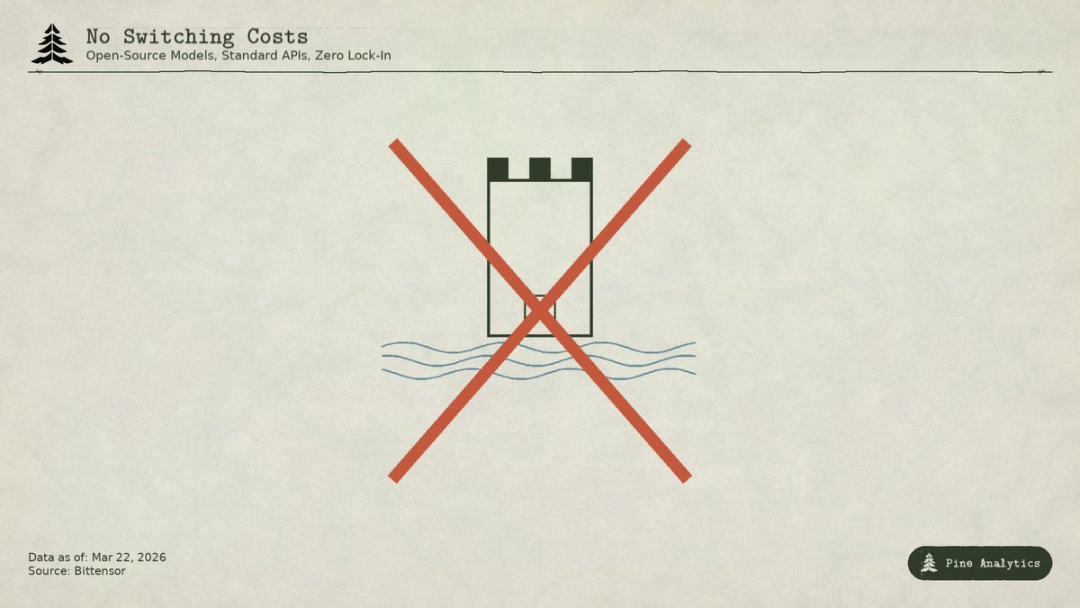
The Moat Problem
Even if a subnet creates a valuable service, the underlying model and methodology are inherently public: Covenant-72B uses an Apache license, and technical papers are published. Any competitor can replicate it without participating in the TAO ecosystem.
Traditional moats (proprietary tech, network effects, switching costs, brand) do not apply:
Technology is open-source.
Network effects belong to TAO, not individual subnets.
Model weights are identical; user switching cost is zero.
The community argues the incentive mechanism is the moat, but this relies on sustained, large-scale token issuance, and each halving continuously shrinks the incentive budget.
What is TAO Actually Trading On?
At a $2.6 billion market cap, TAO's price does not reflect demand fundamentals; $3–15 million in annual revenue cannot support the valuation under any traditional framework. The market is trading on: Bitcoin-like scarcity, Grayscale ETF expectations, AI sector rotation, and the long-term option value of decentralized AI. These are all valid speculative factors, but they stem entirely from the supply side and market sentiment.
If you hold TAO based on scarcity and narrative, you may profit even with weak demand. But if you believe Bittensor will become a genuinely scaled AI service network, there is currently no evidence, and it faces significant structural headwinds. Investors should clearly distinguish their investment thesis.